










Sabrimala Industries to Consider Q2 Results on November 10
Key highlights
- Sabrimala Industries' board will consider Q2 and half-year results on November 10, 2026.
- Sabrimala Industries reported a ₹0.12 crore net profit in the June 2026 quarter.
- The company recorded a ₹0.06 crore net loss in the March 2026 quarter.
- Sabrimala Industries reported FY26 standalone net profit of ₹0.34 crore and total income of ₹0.84 crore.
powered by IRIS
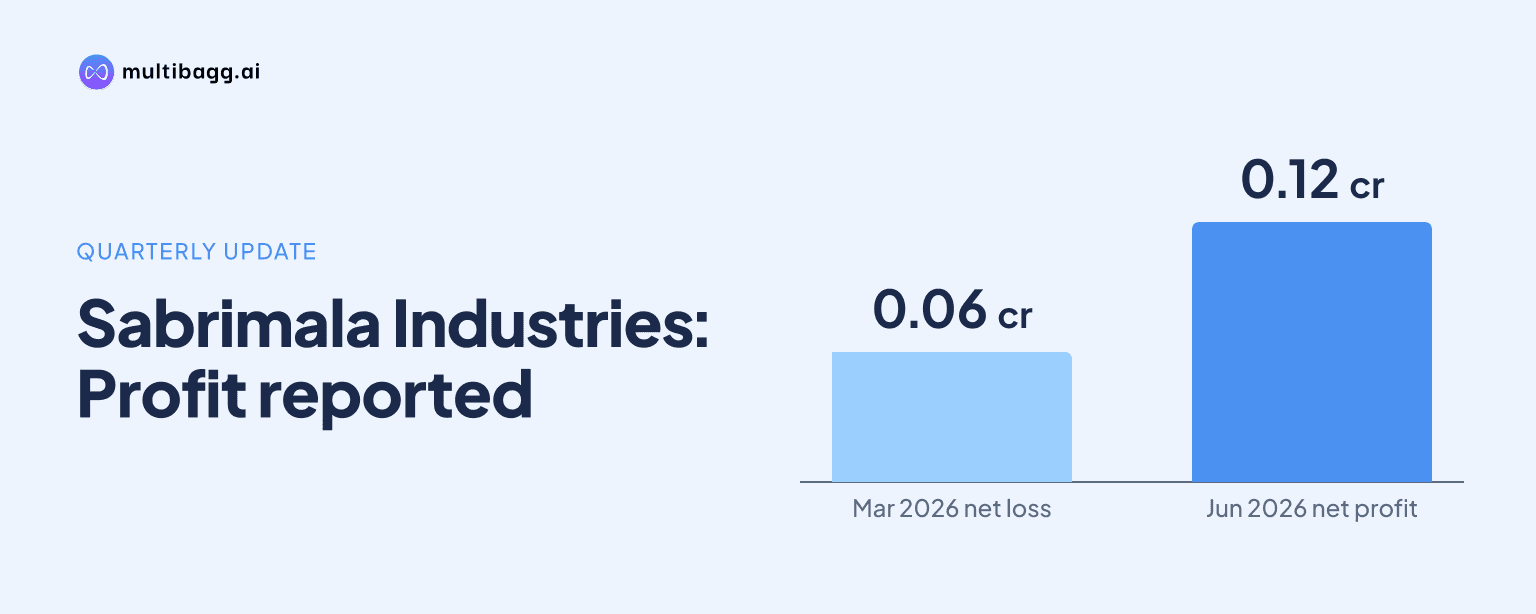
Sabrimala Industries India Limited is scheduled to consider its Q2 results on November 10, following a ₹0.12 crore net profit for the quarter ended June 2026 and a ₹0.06 crore loss in the preceding March 2026 quarter. The board meeting is relevant because it will also consider the company's half-year financial results.
Know Sabrimala Industries India inside out
Results, valuation, peers and who's buying, in one view.
When will Sabrimala Industries consider its Q2 results?
Sabrimala Industries will hold a board meeting on November 10, 2026, to approve its Q2 and half-year financial results, according to the board-meeting intimation dated October 31. The company is among 44 companies scheduled to announce Q2 FY27 results on that date.
The wording in the board-meeting notice refers to approval of Q2 and half-year FY2026 results, while the broader results calendar identifies the event as Q2 FY27. The available information does not resolve that period description difference. Investors will need to rely on the financial statements and board-meeting outcome filed after the meeting for the confirmed reporting period and reported figures.
The upcoming disclosure follows Sabrimala's submission of unaudited standalone and consolidated financial results for the first quarter ended June 30, 2026. The company has also previously filed revised financial results for the quarter and nine months ended December 31, 2025, and a revised Q2 FY26 cash-flow statement after a BSE compliance notification.
What did Sabrimala Industries report in the June 2026 quarter?
Sabrimala reported a net profit of ₹0.12 crore and earnings per share of ₹0.13 for the June 2026 quarter. The reported quarterly revenue was shown as nil or unavailable in the supplied financial data, while the company recorded a net profit of ₹0.12 crore.
This represented a recovery from the March 2026 quarter, when Sabrimala posted a net loss of ₹0.06 crore and a loss per share of ₹0.07. On the displayed quarterly comparison, net profit increased 300% quarter on quarter, based on the movement from a ₹0.06 crore loss to a ₹0.12 crore profit.
The quarterly operating data also showed expenses of ₹0.04 crore in June 2026 and an operating loss of ₹0.04 crore. Profit before tax stood at ₹0.16 crore. Since revenue was reported as zero in the available table, operating-margin and net-margin measures were not provided for that quarter.
How did Sabrimala Industries perform in FY26?
Sabrimala reported standalone net profit of ₹0.34 crore for FY26, compared with ₹0.09 crore in the previous year. Its FY26 total income was ₹0.84 crore, while total expenses were ₹0.38 crore, according to the company's audited annual results summary.
The full-year outcome included a net loss of ₹0.06 crore in the March 2026 quarter. This means the annual profit was generated despite the final-quarter loss, with the June 2026 quarter subsequently returning to a reported profit.
On a consolidated basis, Sabrimala reported FY26 net profit of ₹0.33 crore, versus ₹0.46 crore in FY25. The difference between the standalone and consolidated annual profit figures is small for FY26, but the year-on-year comparison differs by reporting basis. Investors should therefore distinguish between standalone and consolidated results when assessing the company's performance.
Got a follow-up? Ask IRIS
What should investors examine in the November results?
Investors should examine whether Sabrimala's June-quarter profit of ₹0.12 crore was sustained, alongside the reported revenue, expenses, cash-flow disclosures and profit composition. The June-quarter figures showed nil or unavailable revenue in the supplied data, making the detailed results filing important for understanding the drivers of profitability.
The half-year disclosure will provide a broader view than a single quarter. It can show whether the March-quarter loss was an isolated result, whether the June-quarter return to profit continued, and how total income and expenses moved through the first half of the financial year.
The company has faced filing-related revisions before. It submitted revised financial results for the period ended December 2025 and later revised its Q2 FY26 cash-flow statement following a BSE compliance notification. These events make the completeness and consistency of the November filing a relevant point for shareholders.
How does the results date affect the market's assessment?
The November 10 board meeting creates a defined event for investors tracking Sabrimala's financial disclosures. Until the results are approved and filed, no Q2 revenue, profit, margin or earnings-per-share figure has been provided in the available information.
For the company, the results will update the market on operations after FY26, when standalone net profit reached ₹0.34 crore but consolidated net profit declined to ₹0.33 crore from ₹0.46 crore a year earlier. The June-quarter profit of ₹0.12 crore supplies a recent reference point, but it does not establish the outcome for the pending quarter.
The reported absence of quarterly sales in the available data also limits direct operating comparisons. The formal results, notes to accounts and any accompanying exchange filing will be the key documents for evaluating whether income was generated through core operations, other income or a combination of factors.
Conclusion
Sabrimala's November 10 board meeting is important because it will provide the next financial update after a ₹0.12 crore profit in the June 2026 quarter and a ₹0.34 crore standalone profit for FY26. The available figures show a return to quarterly profit after the March-quarter loss, while the broader annual data show different trends for standalone and consolidated profit.
The next item to watch is the board-approved Q2 and half-year filing on November 10, including confirmation of the reporting period, revenue disclosure, expense movement, profit metrics and cash-flow details. The filing should also clarify the period-label difference between the board-meeting notice and the results calendar.