










Sai Parenterals approves Bion majority deal by November 30
Key highlights
- Sai Parenterals approved the Bion majority-control transaction on November 16, 2026, with completion targeted by November 30, 2026.
- Bion reported total income of Rs 47.29 crore in 2025-26, compared with Rs 47.14 crore in 2024-25.
- Sai Parenterals plans to fund SP Analytics with IPO general-corporate-purpose proceeds and debt.
- The filing reports Rs 28.22 crore turnover and Rs 28.75 crore total income for Bion's half-year ended September 30, 2026.
powered by IRIS
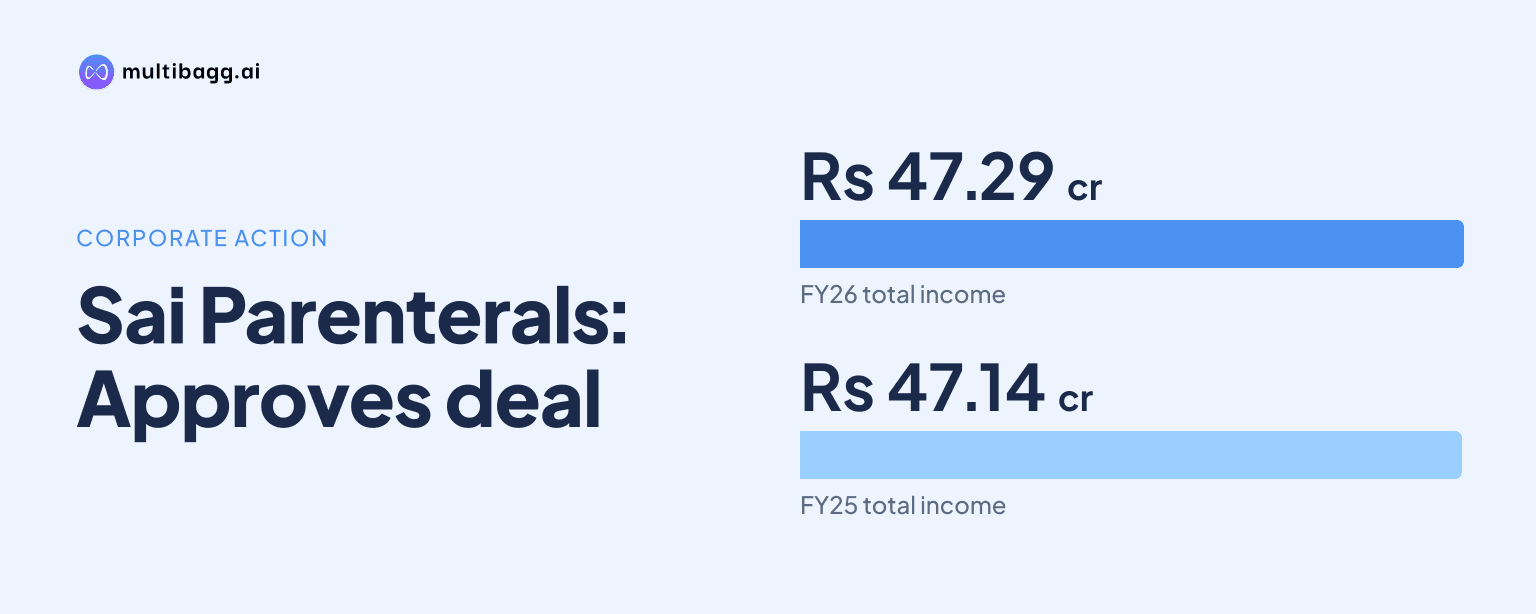
Sai Parenterals Limited approved an all-cash majority-control acquisition of Bion Therapeutics (India) Private Limited through SP Analytics Private Limited, targeting completion by November 30, 2026, for a business that reported Rs 47.29 crore of total income in 2025-26. Sai Parenterals plans to fund SP Analytics with initial public offering general-corporate-purpose proceeds and debt, subject to applicable laws and requisite approvals.
Know Sai Parenterals inside out
Results, valuation, peers and who's buying, in one view.
What has Sai Parenterals approved for Bion?
Sai Parenterals approved the signing of an agreement through its wholly owned subsidiary, SP Analytics Private Limited, to acquire a majority stake and/or controlling interest in Bion. The board made the decision at its November 16, 2026 meeting, held from 5.30 pm to 8.10 pm. The filing describes Bion as a Hyderabad-based branded formulations prescription business in the pharma sector.
The proposed transaction is an all-cash deal rather than a share swap, and Bion would become a step-down subsidiary of Sai Parenterals when the transaction is completed. The filing does not disclose the exact percentage of Bion shares to be acquired, the number of shares, the selling shareholders or the rupee consideration. It says the acquisition price will be based on Bion's valuation by an independent valuer.
How will Sai Parenterals fund the Bion acquisition?
Sai Parenterals plans to provide SP Analytics funding support using proceeds earmarked for general corporate purposes, or GCP, from its initial public offering, or IPO, along with debt. The board approved this funding support on November 16, 2026, subject to applicable laws and requisite approvals. The acquisition disclosure separately states that no governmental or regulatory approvals are required for the transaction.
The announced structure places SP Analytics between Sai Parenterals and Bion, with SP Analytics wholly owned by Sai Parenterals and Bion intended to become its step-down subsidiary. The filing identifies IPO GCP proceeds and debt as financing mechanisms but does not state the amount to be used from either source, the borrowing terms or the final cash outlay. These omissions mean the transaction's funding mix and effect on debt cannot be calculated from the November 16 disclosure.
What financial information has Sai Parenterals disclosed about Bion?
Sai Parenterals disclosed that Bion recorded total income of Rs 47.14 crore in 2024-25 and Rs 47.29 crore in 2025-26, an increase of Rs 15 lakh. For 2026-27, Bion reported total income of Rs 28.75 crore for the half-year ended September 30, 2026. The filing provides no profit, net worth, debt, cash-flow, receivables, product-sales or margin data for Bion.
The 2025-26 total-income figure increased by Rs 15 lakh from 2024-25, while the Rs 28.75 crore reported for the half-year ended September 30, 2026 equals about 61% of the preceding full-year total income. That comparison is not a forecast for 2026-27 because Sai Parenterals did not disclose a full-year target, sales seasonality or an earnings estimate for Bion.
Got a follow-up? Ask IRIS
Why do Bion's half-year figures differ in the announcement?
Sai Parenterals disclosed two different figures for Bion's half-year ended September 30, 2026: Rs 28.22 crore as turnover in the acquisition-details table and Rs 28.75 crore as total income in the background financial table. The difference is Rs 53 lakh. The announcement does not explain whether this reflects the use of turnover rather than total income, a classification adjustment or another factor.
The distinction matters because turnover and total income need not be identical accounting measures, yet the filing does not define or reconcile either measure for the September 30, 2026 half-year. The historical annual comparison uses total income of Rs 47.14 crore for 2024-25 and Rs 47.29 crore for 2025-26 rather than turnover. The Rs 28.75 crore figure is therefore the disclosed measure that is comparable with those two annual total-income figures.
When is the Bion deal expected to close and what remains unresolved?
Sai Parenterals expects the acquisition to be completed on or before November 30, 2026, following the November 16, 2026 board approval. The filing states that no governmental or regulatory approvals are required for the acquisition. It does not provide detailed closing conditions beyond the proposed agreement and transaction structure through SP Analytics.
The filing says the deal is intended to be undertaken on an arm's-length basis, subject to appropriate assessment and valuation where applicable. It also says the transaction will be evaluated under the Companies Act, 2013 and the Securities and Exchange Board of India Listing Obligations and Disclosure Requirements Regulations, 2015, for related-party transaction requirements. Any promoter or promoter-group interest in Bion or its selling shareholders will be disclosed if applicable, but the November 16 announcement identifies no such interest.
Conclusion
Sai Parenterals is pursuing a cash-funded route to add majority control of Bion, a pharma-sector company incorporated on September 5, 2005, to its group through SP Analytics. Bion's disclosed total income increased from Rs 47.14 crore in 2024-25 to Rs 47.29 crore in 2025-26, while the filing leaves an unexplained Rs 53 lakh difference between its turnover and total-income figures for the half-year ended September 30, 2026.
The next disclosed milestone is completion on or before November 30, 2026. Investors should watch for the final acquisition price, the precise stake acquired, the split between IPO GCP proceeds and debt, valuation details, and any disclosure of promoter-group interests or related-party considerations when the transaction is completed.