










Sakthi Finance Q2 profit falls 10% as income declines
Key highlights
- Sakthi Finance reported quarterly profit after tax of Rs 3.38 crore, down from Rs 3.76 crore a year earlier.
- Sakthi Finance's total income declined to Rs 50.48 crore from Rs 52.87 crore in the prior-year quarter.
- Sakthi Finance's GNPA ratio improved to 4.32% at 30 September 2026 from 4.92% a year earlier.
- Sakthi Finance's capital adequacy ratio increased to 21.63% from 18.70% a year earlier.
powered by IRIS
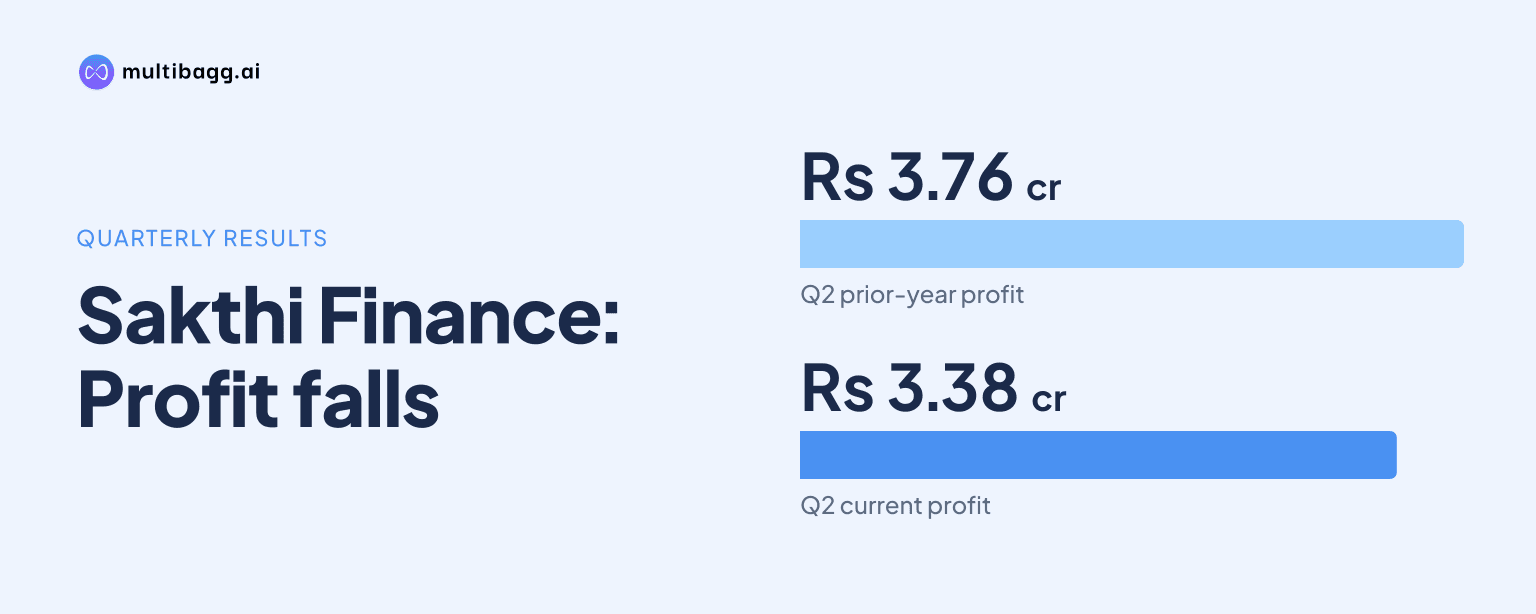
Sakthi Finance Limited reported profit after tax of Rs 3.38 crore for the quarter ended 30 September 2026, down 10% from Rs 3.76 crore a year earlier, as total income fell to Rs 50.48 crore from Rs 52.87 crore despite lower finance costs and lower gross non-performing assets.
Know Sakthi Finance inside out
Results, valuation, peers and who's buying, in one view.
How did Sakthi Finance's quarterly profit change?
Sakthi Finance's profit after tax fell by Rs 0.38 crore year-on-year to Rs 3.38 crore for the quarter ended 30 September 2026, from Rs 3.76 crore in the quarter ended 30 September 2025. It was also below the Rs 4.18 crore reported in the quarter ended 30 June 2026. Earnings per share declined to Rs 0.52 from Rs 0.58 a year earlier and Rs 0.65 in the preceding quarter.
Total income was Rs 50.48 crore in the September 2026 quarter, compared with Rs 52.87 crore a year earlier and Rs 51.20 crore in the June 2026 quarter. Profit before tax was Rs 5.31 crore, down from Rs 5.46 crore in September 2025 and Rs 5.53 crore in June 2026. Sakthi Finance reported no exceptional items in these three quarters.
For the half year ended 30 September 2026, Sakthi Finance recorded profit after tax of Rs 7.57 crore, compared with Rs 7.88 crore in the corresponding prior-year half year. Half-year total income declined to Rs 101.68 crore from Rs 106.62 crore, while profit before tax decreased to Rs 10.84 crore from Rs 11.27 crore. Net profit margin was 7.44%, versus 7.39% a year earlier.
What caused Sakthi Finance's income decline?
Sakthi Finance's interest income declined to Rs 48.26 crore in the September 2026 quarter from Rs 51.48 crore a year earlier, accounting for the largest part of the reduction in revenue from operations. Revenue from operations fell to Rs 50.49 crore from Rs 52.87 crore, while other income changed to a loss of Rs 0.01 crore from income of Rs 0.20 crore.
Bad-debt recovery rose to Rs 0.79 crore from Rs 0.15 crore, and windmill power sales increased to Rs 1.04 crore from Rs 0.85 crore. Fees and commission income was Rs 0.24 crore, compared with Rs 0.20 crore a year earlier. These increases did not offset the Rs 3.22 crore reduction in interest income.
Finance costs fell to Rs 28.41 crore from Rs 31.50 crore, while total expenses decreased to Rs 45.18 crore from Rs 47.41 crore. Employee benefits expense increased to Rs 9.03 crore from Rs 7.95 crore and depreciation, amortisation and impairment rose to Rs 2.13 crore from Rs 1.55 crore. Deferred tax became an expense of Rs 0.86 crore, compared with a credit of Rs 0.05 crore a year earlier.
Did Sakthi Finance's asset quality improve?
Sakthi Finance's gross non-performing assets, or GNPA, ratio was 4.32% at 30 September 2026, down from 4.92% a year earlier and 4.61% at 30 June 2026. GNPA is calculated as gross Stage III assets divided by gross loan assets, so the reported ratio shows a lower proportion of loans classified as Stage III.
Net non-performing assets, or NNPA, were 2.14% at 30 September 2026, compared with 2.17% at 30 September 2025 and 2.21% three months earlier. The provision coverage ratio, or PCR, was 51.56%, down from 57.03% a year earlier and 53.16% at June 2026. PCR measures impairment loss allowance for Stage III assets as a percentage of gross Stage III assets.
Sakthi Finance said its impairment allowances under Indian Accounting Standard 109 exceeded the provisioning required under Reserve Bank of India income-recognition, asset-classification and provisioning norms, including standard-asset provisions, at 30 September 2026. The company therefore said that no transfer to an impairment reserve was required at that date.
Got a follow-up? Ask IRIS
What changed in Sakthi Finance's balance sheet?
Sakthi Finance's loans were Rs 1,072.60 crore at 30 September 2026, marginally below Rs 1,073.10 crore at 31 March 2026. Total assets declined to Rs 1,350.14 crore from Rs 1,433.52 crore. Cash and cash equivalents fell to Rs 64.79 crore from Rs 155.35 crore, while investments increased to Rs 81.14 crore from Rs 60.23 crore.
Debt securities decreased to Rs 746.76 crore from Rs 782.11 crore between 31 March and 30 September 2026. Deposits declined to Rs 198.49 crore from Rs 219.05 crore, and subordinated liabilities fell to Rs 47.78 crore from Rs 86.61 crore. Borrowings other than debt securities rose to Rs 88.05 crore from Rs 80.91 crore.
Capital adequacy was 21.63% at 30 September 2026, compared with 18.70% a year earlier and 20.45% at 31 March 2026. Net worth was Rs 205.92 crore, against Rs 202.35 crore at 30 September 2025 and Rs 204.78 crore at the March 2026 year-end. The debt-equity ratio was 5.04, compared with 6.21 a year earlier.
What debt actions did Sakthi Finance disclose?
Sakthi Finance redeemed public-issue non-convertible debentures, or NCDs, during the September 2026 quarter. Options I and II under the 13 June 2024 prospectus had principal of Rs 16.90 crore and interest of Rs 1.54 crore. Options VII and VIII under the 25 June 2021 prospectus had principal of Rs 47.59 crore and interest of Rs 11.52 crore.
Sakthi Finance also raised Rs 17.53 crore through a private placement of unlisted, redeemable cumulative preference shares during the quarter ended 30 September 2026. It said the proceeds were used for the purpose stated in the offer letters. Security cover available for its NCDs was 1.10 times at 30 September 2026, backed by a hypothecated charge on specified loan receivables.
The board approved a potential public issue of secured, redeemable NCDs of up to Rs 300 crore, comprising a base issue of up to Rs 150 crore and an oversubscription retention option of up to Rs 150 crore. For two February 2024 NCD options with combined principal of Rs 254.95 crore, Sakthi Finance fixed 12 February 2027 as the record date and stated redemption is due on 26 February 2027.
Conclusion
Sakthi Finance's September 2026 results combined a decline in income and quarterly profit with lower reported GNPA and NNPA ratios. Interest income fell by Rs 3.22 crore from a year earlier, while finance costs declined by Rs 3.09 crore, leaving profit after tax 10% lower at Rs 3.38 crore. Capital adequacy rose to 21.63%, while PCR fell to 51.56%.
The next disclosed funding matter is the board-approved NCD public issue of up to Rs 300 crore, which may be made in one or more tranches. Sakthi Finance also has the 26 February 2027 redemption of the February 2024 NCD options scheduled after the 12 February 2027 record date.