










Sammaan Capital targets ₹20,000 crore H2 FY27 disbursements
Key highlights
- Sammaan reported ₹10,123 crore of H1 FY27 disbursements, slightly above its ₹10,000 crore roadmap.
- Sammaan is targeting approximately ₹20,000 crore of H2 FY27 disbursements and ₹30,100 crore for the full year.
- Sammaan’s Q2 FY27 disbursements rose 62% quarter on quarter to ₹6,278 crore.
- Sammaan targets approximately ₹70,700 crore of FY27 year-end AUM, from ₹59,188 crore at Q2 end.
powered by IRIS
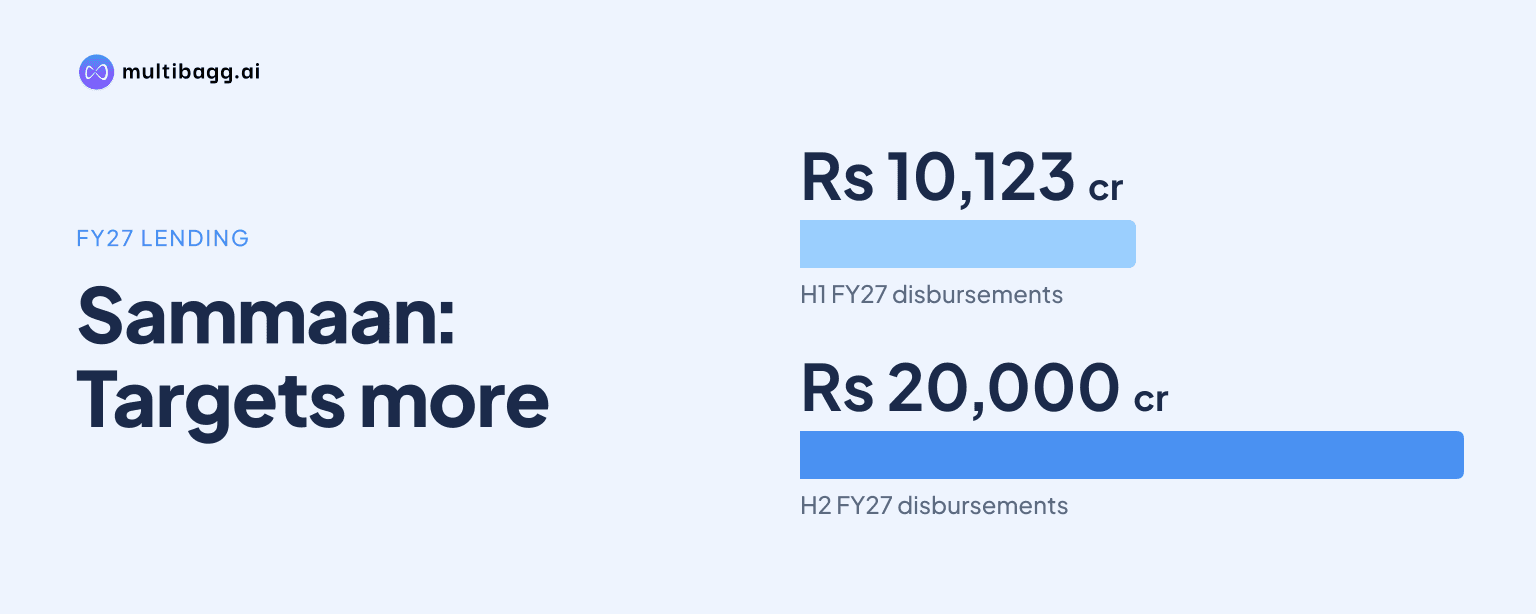
Sammaan Capital is targeting approximately ₹20,000 crore of disbursements in H2 FY27 after reporting ₹10,123 crore in H1, slightly above its ₹10,000 crore roadmap. Management’s full-year disbursement ambition is ₹30,100 crore, requiring a substantial increase from the ₹6,278 crore disbursed during Q2 FY27.
Know Sammaan Capital inside out
Results, valuation, peers and who's buying, in one view.
What is Sammaan targeting for H2 FY27?
Sammaan is targeting approximately ₹20,000 crore of disbursements in H2 FY27, according to management’s FY27 growth roadmap. The company reported ₹10,123 crore of first-half disbursements, slightly above its ₹10,000 crore H1 target, and stated a full-year disbursement ambition of ₹30,100 crore.
The H2 target is an approximate roadmap figure rather than an exact balance of the full-year ambition. Subtracting the reported H1 amount from the ₹30,100 crore annual ambition leaves ₹19,977 crore, close to management’s stated approximately ₹20,000 crore H2 objective. Management said it recognises that the second half will require substantial acceleration in business execution.
How much faster must Sammaan lend in the second half?
Sammaan needs to deliver roughly twice its H1 disbursement volume in H2 to execute its approximately ₹20,000 crore plan. H1 disbursements were ₹10,123 crore, while Q2 alone accounted for ₹6,278 crore, a 62% increase over the preceding quarter. The company completed approximately 30,700 loans in Q2, taking first-half loan disbursals to about 42,600.
At the Q2 disbursement pace, two further quarters would amount to ₹12,556 crore, below the approximate ₹20,000 crore H2 roadmap. That comparison illustrates the acceleration required, although quarterly disbursements need not be even. Management said its investment in people, technology, distribution and products is intended to support the higher second-half execution pace.
Sammaan’s year-end assets under management, or AUM, target is approximately ₹70,700 crore, compared with ₹59,188 crore at the end of Q2 FY27 and ₹56,239 crore in Q1 FY27. Its loan book was ₹46,482 crore at Q2 end against a ₹53,000 crore full-year target. Reported AUM will depend on lending volumes as well as repayments, assignments and sell-downs.
Which products and branches will support Sammaan’s H2 plan?
Sammaan plans to support H2 growth through mortgages, a larger branch network and phased launches of newer retail products. The branch network expanded from 217 to 245 branches across 20 states, and management is working towards approximately 300 branches by the end of FY27. The company added more than 1,000 employees in H1, with 95% assigned to the retail franchise and 87% deployed at branches.
Mortgages remain the principal near-term growth engine. Sammaan has more than 3,600 employees dedicated to mortgages, and approximately 25% have worked at the company for more than 15 years. Management said it had historically sold down approximately ₹1,08,000 crore of mortgage pools to 24 bank and financial-institution partners, with 90-plus-day delinquency below 0.5% on those sold-down pools.
Personal loans are moving from portfolio purchases towards own origination through 20 identified branches. Business instalment-loan product policies have been approved, while operational and technology work continues. Management also intends to expand into retail and e-commerce lending, micro loan against property, rural home loans and gold loans during H2 FY27.
Gold loans have the most specific rollout timetable among the new products. Management plans a soft launch in approximately 16 branches in Q3 FY27, followed by a rollout across 30 more branches in Q4 FY27 and wider expansion in FY28. The indicated gold-loan ticket size is approximately ₹2 lakh, with a yield range of 11% to 13%; Salesforce loan-origination software was live in more than 20 branches, with a countrywide rollout planned in Q3 FY27.
Got a follow-up? Ask IRIS
What financial conditions accompany Sammaan’s growth plan?
Sammaan’s H2 lending plan is accompanied by targets for profit, funding costs and portfolio quality. H1 profit after tax was ₹556 crore against the ₹1,400 crore full-year target, leaving ₹844 crore to achieve in H2. Q2 profit after tax increased to ₹312 crore from ₹243 crore in Q1, while profit before tax rose to ₹425 crore from ₹326 crore.
Asset quality improved between the two quarters. Gross non-performing assets declined to 0.15% in Q2 FY27 from 0.21% in Q1, while net non-performing assets fell to 0.11% from 0.15%. Management reported that 94% of Q2 disbursements were secured loans, blended cumulative collection efficiency was 99.6%, and total provisions equalled 10.2% of the loan book.
Management reported a Q2 cost of funds of 9.8% and said it was working toward a 9.3% target while remaining mindful of the interest-rate environment. Q2 gross margin, calculated by management using interest income, fair-value gains and assignment and sell-down income less interest expense, was ₹517 crore, or 2.9% of assets. Management is guiding towards a margin of around 3.5% as funding costs decline and the loan book grows.
Capital is also part of the operating plan. Net worth stood at ₹19,445 crore before the ₹906 crore received from the first warrant conversion on October 30, 2026, while capital adequacy was 20%. Avenir, through IHC, raised its promoter holding from 28.34% to 33.32%; management said remaining warrants represent ₹2,291 crore and are to convert by September 2027 in one or more tranches.
Conclusion
Sammaan has exceeded its ₹10,000 crore H1 FY27 disbursement roadmap by reporting ₹10,123 crore, but the company’s approximately ₹20,000 crore H2 objective requires a materially higher lending pace. The plan relies on mortgage origination, branch expansion from 245 towards approximately 300 locations, and phased additions including personal, business instalment and gold loans.
The next results will show whether Q3 FY27 disbursements begin closing the gap to the H2 plan and whether the planned gold-loan soft launch in approximately 16 branches proceeds on schedule. Management’s stated targets to watch are a 9.3% cost of funds, a margin of around 3.5%, approximately ₹70,700 crore of year-end AUM, and conversion of the remaining ₹2,291 crore of warrants by September 2027.