










Sammaan Capital phases personal, MSME and gold loan rollout
Key highlights
- Sammaan plans to soft-launch gold loans in approximately 16 branches in FY27 Q3 and add 30 more in FY27 Q4.
- Sammaan's personal-loan portfolio-purchase product has an average ticket size of about Rs 2 lakh and a 16%-17% yield.
- Sammaan is preparing MSME business instalment loans with Rs 18 lakh to Rs 20 lakh ticket sizes and a 14%-18% yield range.
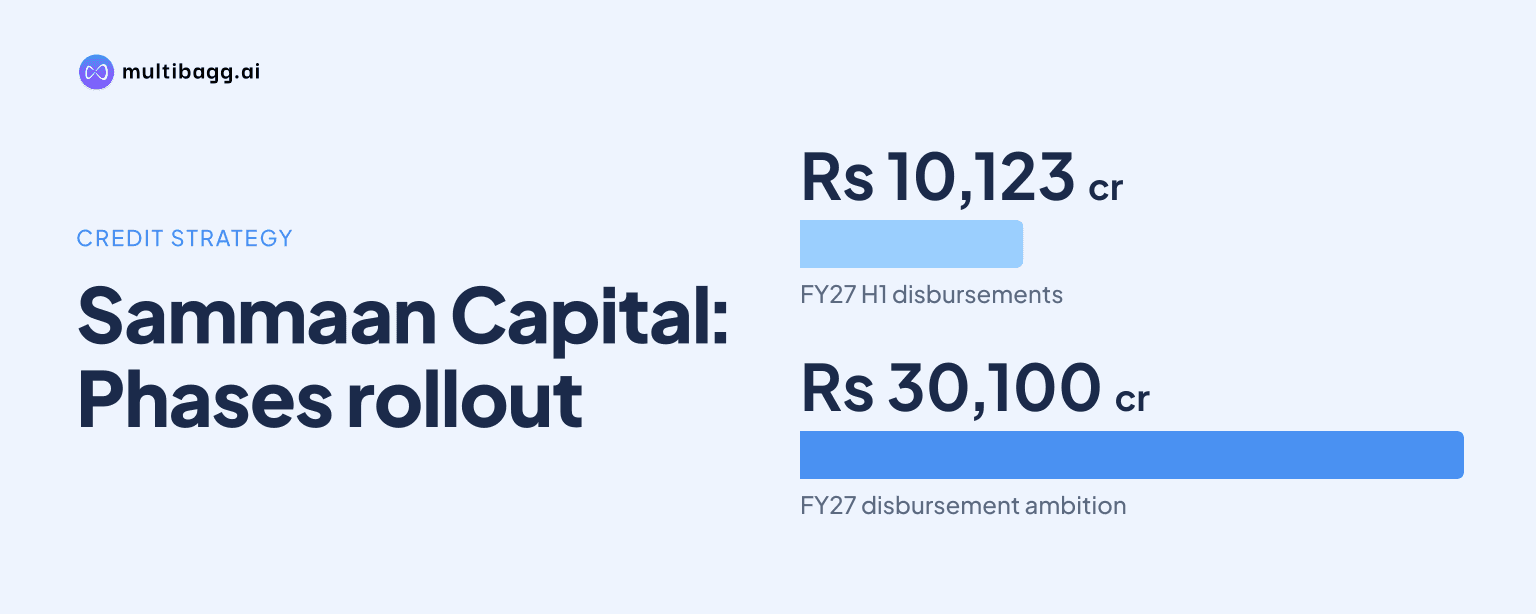
- Sammaan reported FY27 H1 disbursements of Rs 10,123 crore against a full-year ambition of Rs 30,100 crore.
powered by IRIS
Sammaan Capital is pursuing a phased expansion beyond mortgages, with a gold-loan soft launch planned in approximately 16 branches in FY27 Q3 and personal-loan own origination planned through 20 branches. The company is first using portfolio purchases, approved product policies and new operating systems before wider retail lending expansion.
Know Sammaan Capital inside out
Results, valuation, peers and who's buying, in one view.
What new retail products is Sammaan launching?
Sammaan is adding personal loans, business instalment loans for micro, small and medium enterprises (MSMEs), and gold loans while mortgages remain its main growth business. Management said in May 2026 that mortgages would lead the first two years of growth as the company built new lending engines, and it described the FY27 product programme as the next stage of that plan.
The products have different entry methods and proposed economics. Personal loans are already present through portfolio purchases and tie-ups, while MSME business instalment loans have approved policies but remain under operational and technology development. Gold loans are planned as a secured product against jewellery, requiring valuation, collateral custody and branch-vault controls.
Personal loans are designed with an average ticket size of about Rs 2 lakh and a tenure of around two years, with the 16%-17% yield applying to the portfolio-purchase book. By comparison, proposed MSME loans have much larger Rs 18 lakh to Rs 20 lakh tickets and a 14%-18% yield band, while gold loans combine a Rs 2 lakh ticket with jewellery-backed collateral.
How will Sammaan build personal and MSME loan originations?
Sammaan plans to seed its personal and MSME portfolios through seasoned pools before scaling its own loan originations. For personal loans, it has identified 20 branches and is developing assisted and digital customer journeys, alongside technology and credit-decisioning platforms, before moving beyond its existing portfolio purchases and tie-ups.
MSME business instalment lending has no disclosed branch target or portfolio target, but Sammaan has approved the product policies and is progressing with operating and technology systems. The Rs 18 lakh to Rs 20 lakh proposed ticket size distinguishes this product from the roughly Rs 2 lakh personal loan, even though both are intended to use shared leadership, technology and distribution infrastructure.
Sammaan has four operating models: originate-and-assign, originate-and-hold, pool purchases and private-credit-fund partnerships. Under originate-and-assign, it sells loans to banks and financial institutions for servicing income and excess spread; originate-and-hold retains higher-yielding assets on its balance sheet. Pool purchases allow it to acquire seasoned assets while building its own sourcing capability.
The company has mortgage experience with the assignment model, having historically sold down about Rs 1,08,000 crore of mortgage pools to 24 bank and financial-institution partners. Management said 90-plus-day delinquency on these sold-down pools has remained below 0.5%, a record it cited as support for extending a measured, rather than immediate large-scale, origination approach to newer products.
When will Sammaan launch gold loans?
Sammaan plans to soft-launch gold loans in about 16 branches in FY27 Q3, then add 30 branches in FY27 Q4 before wider expansion in FY28. The first 46 planned branches are intended to establish the product and operating process before a larger network rollout.
The product will be secured against gold jewellery, with an indicative ticket size of approximately Rs 2 lakh and a stated yield range of 11%-13%. Management also referred to potential higher-yielding segments and said it was building an independent platform covering gold valuations, collateral management, disbursements, repayments, closures and branch-level vault controls.
Gold loans would extend Sammaan's existing secured-lending emphasis. Secured loans represented approximately 94% of Q2 FY27 disbursements, while blended cumulative collection efficiency was 99.6%. The jewellery-backed product differs from the unsecured personal-loan initiative but is also intended to use branches as its primary customer-access point.
Sammaan had 245 branches when it disclosed the rollout plan and is working towards approximately 300 branches by FY27 year-end, particularly in Tier 2 and Tier 3 cities and underserved semi-urban markets. Management said the network might exceed that figure by roughly a dozen branches if economic and market conditions permit, but its stated target remains approximately 300.
Got a follow-up? Ask IRIS
How central will mortgages remain to Sammaan's strategy?
Sammaan says mortgages will remain the backbone of its growth strategy despite the new retail categories. Residential housing finance, including affordable housing and mortgages, accounted for approximately Rs 31,445 crore of its Rs 59,188 crore assets under management (AUM) in Q2 FY27, making it the largest disclosed portfolio component.
The other stated segments were smaller than residential housing finance. Secured business loans and home-loan equity represented about Rs 14,741 crore, while commercial real estate, project loans, plot loans and lease-rental discounting totalled approximately Rs 11,118 crore. Other loans, including unsecured business, working capital and personal loans, were about Rs 1,543 crore, and loans against securities were approximately Rs 270 crore.
Mortgage expansion is being supported by staffing, branch additions and technology. More than 3,600 employees are dedicated to mortgages, with almost 25% having more than 15 years of service. In FY27 H1, Sammaan added more than 1,000 employees, of whom 95% joined the retail franchise and 87% were deployed at branches.
Its technology programme spans mortgages and new products. Salesforce customer relationship management is live, Salesforce loan origination system is being rolled out, and the loan management system is being upgraded. Since June 2026, Salesforce generated more than 2.09 lakh leads, with 2,418 users across sales, credit and the contact centre.
Can Sammaan deliver its FY27 lending targets?
Sammaan reported FY27 H1 disbursements of Rs 10,123 crore, slightly above its Rs 10,000 crore roadmap, but it needs roughly Rs 20,000 crore in the second half to meet its Rs 30,100 crore full-year ambition. Management acknowledged that the second half requires substantial acceleration and said investments in people, products, distribution and technology were intended to support it.
The Q2 FY27 loan book was Rs 46,482 crore against a full-year target of Rs 53,000 crore, while AUM of Rs 59,188 crore compared with a stated FY27 target of approximately Rs 70,700 crore. Branch growth towards approximately 300 locations and the controlled rollout of personal, MSME and gold loans are therefore linked to the company's second-half execution requirement.
Credit and profitability measures provide context for that growth plan. Net non-performing assets declined from 0.83% in Q1 FY26 to 0.11% in Q2 FY27, while return on assets increased from 1.3% in Q1 FY27 to 1.5% in Q2 FY27. Return on managed assets rose from 1.1% to 1.3% across the same Q1-to-Q2 FY27 period.
Sammaan recorded FY27 H1 profit after tax of Rs 556 crore against a Rs 1,400 crore full-year target, and its cost of funds was 9.8% versus a stated 9.3% target. Management said it would remain mindful of the interest-rate environment and maintain underwriting standards, customer selection and portfolio monitoring as it expands lending.
Conclusion
Sammaan's diversification is a controlled expansion rather than a simultaneous nationwide launch. Mortgages remain its largest business at Rs 31,445 crore of Q2 FY27 AUM, while personal loans move from purchased pools towards 20-branch own origination, MSME lending awaits operating readiness, and gold loans begin in 16 branches. The product routes separate unsecured consumer credit, larger-ticket business lending and secured jewellery-backed credit.
The next test is delivery of approximately Rs 20,000 crore of second-half FY27 disbursements after Rs 10,123 crore in H1. Management's disclosed milestones are the addition of 30 gold-loan branches in FY27 Q4, progress towards approximately 300 total branches by year-end, and movement toward its 9.3% cost-of-funds target.