










Sammaan Capital targets Q4FY27 own-originated loan launches
Key highlights
- Sammaan Capital plans tentative Q4FY27 soft and commercial launches for own-originated PL and BIL.
- PL is live through pools with a stated 16.5% yield, about Rs 2 lakh ticket size and about two-year term.
- BIL is pre-launch for MSMEs, with about Rs 18 lakh tickets, about three-year terms and a 14–18% yield band.
- Sammaan Capital has identified 20 PL branches and plans to identify 20 BIL soft-launch branches.
powered by IRIS
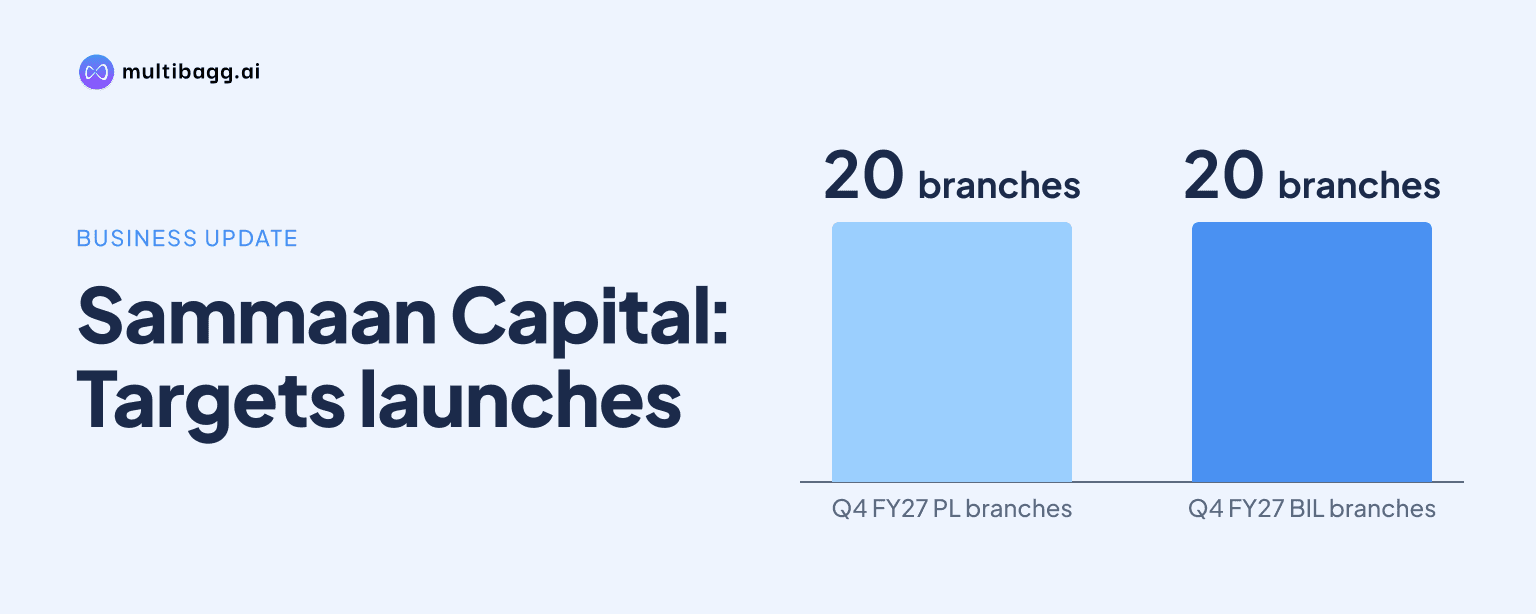
SAMMAAN CAPITAL (Sammaan Capital) plans tentative Q4FY27 soft and commercial launches of own-originated personal loans and business instalment loans after seeding the books through seasoned pools. Personal loans are already live via pools at a stated 16.5% yield, while the pre-launch business instalment loan carries a disclosed 14–18% yield band for micro, small and medium enterprises.
Know Sammaan Capital inside out
Results, valuation, peers and who's buying, in one view.
When will Sammaan Capital launch own-originated personal and business instalment loans?
Sammaan Capital plans soft and commercial launches for both Personal Loans (PL) and Business Instalment Loans (BIL) in Q4FY27, subject to market conditions at that time. The PL lifecycle shows technology build as the current stage, followed by both soft launch and commercial launch in Q4FY27. BIL is in set-up, with testing planned in Q3FY27 before its Q4FY27 soft and commercial stages.
The timetable follows policy approval but still depends on technology and distribution preparation. Sammaan Capital states that both PL and BIL product policies are approved, while Salesforce customer relationship management (CRM) has been live since June 2026. The presentation explicitly labels the launch dates tentative, so Q4FY27 represents management's disclosed plan rather than a completed launch.
How will Sammaan Capital seed and retain the new loan books?
Sammaan Capital will use pool purchases to seed PL and BIL books before moving to own origination and retention on its balance sheet. Its common launch playbook is seasoned pools, followed by loan origination system (LOS), business rule engine (BRE) and digital-journey go-lives, then a branch soft launch and scaling through own origination. PL is already live through pools, whereas BIL remains pre-launch.
Both products are classified in the pool-purchases-to-originate-and-hold model, with a yield band above 13%. This differs from the prime and micro, small and medium enterprise mortgage model, which Sammaan Capital lists as originate and assign at a 9–11% yield band. Prime and MSME mortgages are sold down to banks through direct assignment, while retained PL and BIL loans are intended to build net interest income.
Sammaan Capital does not disclose the size of its PL pool book, a target amount for BIL pool purchases, or the date of a first BIL pool acquisition. Its broader strategic mix nevertheless identifies seasoned PL and BIL pools as instruments for building the book before own origination. That leaves the scale of initial unsecured exposure undisclosed despite the Q4FY27 launch framework.
What borrowers and terms are planned for each product?
Sammaan Capital's PL is aimed at metro and Tier 1 borrowers, with an average ticket size of about Rs 2 lakh, a term of about two years and a median Credit Information Bureau (India) Ltd, or CIBIL, score of about 750. The stated customer mix is 40% salaried and 60% self-employed, and the disclosed yield is 16.5%.
BIL is an unsecured product for MSMEs, with an average ticket size of about Rs 18 lakh, a term of about three years and a median CIBIL score of about 750. Its 14–18% yield band is a range rather than the single 16.5% rate stated for PL. The presentation gives no salaried-versus-self-employed mix for BIL, consistent with its specified MSME borrower segment.
The planned BIL ticket is nine times the PL ticket, at about Rs 18 lakh against about Rs 2 lakh, and its stated term is roughly one year longer. Both products are unsecured and have the same disclosed median CIBIL score of about 750. Sammaan Capital provides no approval-rate, delinquency or credit-cost target for either product.
Got a follow-up? Ask IRIS
What technology and branch work remains before launch?
Sammaan Capital is using shared leadership, Salesforce and digital infrastructure for PL and BIL. For PL, the assisted Salesforce LOS and BRE are scheduled for Q3FY27, lending service provider integrations for January 2027, and mobile and web self-service journeys for Q4FY27. Salesforce CRM, the common lead-management platform, went live in June 2026.
For BIL, the end-to-end process build is in progress and self-service mobile and web journeys are planned for Q4FY27. Sammaan Capital does not state separate BIL timing for the LOS or BRE. Shaunak Batra is identified as Product Head for Personal and Business Loans, with more than 15 years of experience at Aditya Birla Capital, Hero Fincorp, BMW Financial Services and Citibank.
Sammaan Capital has identified 20 branches from its 245-branch network for the PL rollout, with lending service provider sourcing planned for January 2027. It plans to identify 20 existing-network branches for the BIL soft launch. The wider network is targeted to increase from 245 branches in Q2FY27 to about 300 by FY27, with 91% of that planned network already in place.
How do PL and BIL change Sammaan Capital's portfolio mix?
Sammaan Capital is introducing the two unsecured products into a portfolio where 94% of Q2FY27 disbursements were secured. Its other-loans category, including unsecured business, working-capital and personal loans, had assets under management of Rs 1,543 crore as of September 30, 2026. That category recorded Q2FY27 disbursals of Rs 367 crore and an average ticket size of Rs 1.4 lakh.
The existing other-loans category has a 10–17% yield range, actuarial tenure of about 1.5 years and 100.0% cumulative collection efficiency. In comparison, the planned PL has a two-year term and a 16.5% yield, while BIL has a three-year term and a 14–18% range. The source does not separate historical PL performance from unsecured business and working-capital loans in the Rs 1,543 crore category.
Sammaan Capital's strategic portfolio mix places affordable mortgages and loans against securities in the 11–13% originate-and-hold band, whereas PL and BIL are positioned above 13%. The launches would therefore add higher-yielding own-book products alongside affordable mortgages. Management does not disclose an assets-under-management target, disbursal target or credit-cost assumption for either PL or BIL.
Conclusion
Sammaan Capital's disclosed approach is to establish unsecured PL and BIL exposure through seasoned pools, complete shared technology and digital journeys, conduct branch soft launches and then retain own-originated loans. PL is further along because it is live via pools, has 20 identified branches and carries a stated 16.5% yield, while BIL remains in pre-launch set-up with a 14–18% yield band.
The next milestones are BIL testing in Q3FY27, the planned Q3FY27 assisted PL LOS and BRE deployment, and Q4FY27 soft and commercial launch stages for both products. Investors can also watch for PL's Q4FY27 mobile and web self-service journey, identification of 20 BIL branches and any update on the tentative dates, which management says remain subject to market conditions.