










Sanathan Textiles Limited Q2 FY27 Revenue Reaches ₹1,804 Crore
Key highlights
- Sanathan Textiles reported Q2 FY27 consolidated revenue of ₹1,804 crore, up 120.5% year on year.
- Consolidated EBITDA rose 145.0% year on year to ₹154.7 crore, with margin improving 90 basis points to 8.6%.
- Consolidated PAT increased 204.5% year on year to ₹61.2 crore, while PAT margin reached 3.4%.
- Standalone revenue was ₹992.1 crore, up 29.3% year on year, while standalone EBITDA margin declined 80 basis points to 8.5%.
powered by IRIS
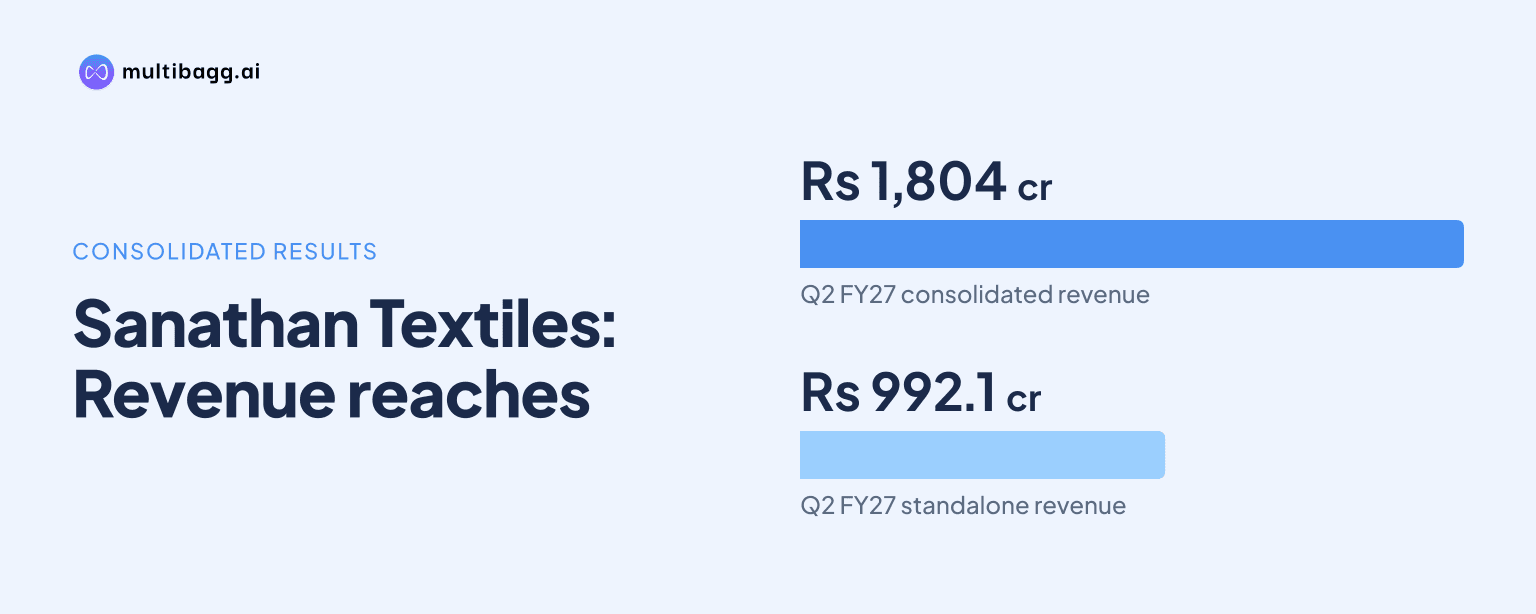
Sanathan Textiles Limited reported consolidated revenue of ₹1,804 crore in Q2 FY27, a 120.5% year-on-year increase from ₹818 crore, supported by the ramp-up of its Punjab facility and higher operating scale. Consolidated EBITDA rose 145.0% to ₹154.7 crore, while profit after tax reached ₹61.2 crore.
Know Sanathan Textiles inside out
Results, valuation, peers and who's buying, in one view.
What did Sanathan Textiles report for Q2 FY27?
Sanathan Textiles reported a sharp increase in consolidated scale for the quarter ended September 2026. Revenue rose to ₹1,804 crore from ₹818 crore in Q2 FY26, while it was also 35.2% higher sequentially, according to the results presentation. The expansion in the consolidated business was linked to the Punjab facility's volume ramp-up and better fixed-cost absorption.
The company reported consolidated EBITDA of ₹154.7 crore, up 145.0% year on year. EBITDA margin improved by 90 basis points to 8.6%. Consolidated PAT was ₹61.2 crore, an increase of 204.5% from the year-earlier quarter, and PAT margin increased by 90 basis points to 3.4%.
How did the Punjab facility affect quarterly revenue?
The Punjab facility ramp-up contributed meaningfully to volumes and revenue growth during Q2 FY27, according to the company presentation. The facility's higher utilisation increased consolidated operating scale and supported the 35.2% quarter-on-quarter rise in revenue.
Higher scale also improved fixed-cost absorption, which supported the increase in consolidated profitability. The presentation linked the operational expansion to the stronger EBITDA and PAT growth, while indicating that the company remains focused on efficiency improvements and capacity expansion.
The reported consolidated growth was substantially higher than the standalone growth rate. Standalone revenue increased 29.3% year on year to ₹992.1 crore from ₹767.1 crore. This difference reflects the importance of the expanded operations within the consolidated performance for the quarter.
What happened to standalone margins in the quarter?
Standalone profitability rose in absolute terms, but standalone margins declined from the year-earlier period. Standalone EBITDA was ₹83.8 crore, up 17.7% year on year, while EBITDA margin declined by 80 basis points to 8.5%.
Standalone PAT was reported at ₹58.7 crore, up 15.8% year on year, and the PAT margin declined by 70 basis points to 5.9%. The supplied results material also separately cited a standalone net-profit figure of ₹68.69 crore. The company presentation's ₹58.7 crore figure is used here because it is accompanied by the stated year-on-year growth and margin data.
The margin movement shows that revenue growth at the standalone level did not translate into a similar margin expansion. By contrast, the consolidated EBITDA and PAT margins each improved by 90 basis points, aided by the operational contribution of the Punjab ramp-up.
Got a follow-up? Ask IRIS
What do the results mean for investors and industry operations?
The quarter shows how newly expanded capacity can influence textile manufacturers' reported revenue and cost absorption once volumes increase. For Sanathan Textiles, the Punjab ramp-up was a stated factor behind the consolidated revenue, EBITDA and PAT performance. The figures also show that consolidated and standalone trends can differ materially during an expansion phase.
For investors, the margin data is relevant alongside revenue growth. Consolidated EBITDA margin reached 8.6%, whereas standalone EBITDA margin was 8.5% and 80 basis points below the prior-year level. The company has stated that its operational focus remains on efficiency, additional capacity and sustaining attention to margins.
The board approved the un-audited standalone and consolidated results on November 4, 2026. The limited-review conclusion was unmodified, although the consolidated review noted reliance on another auditor for one subsidiary. The board also proposed five-year reappointments of Paresh, Ajaykumar and Anilkumar Dattani from December 1, 2026, subject to shareholder approval.
What information is scheduled after the Q2 FY27 results?
Sanathan Textiles scheduled an earnings call for November 5, 2026 at 5:00 PM IST to discuss Q2 FY27 financial performance and operational updates with investors and analysts. The source material states that no earnings-call transcript had been published for the quarter at the time of the reported presentation figures.
That call is expected to provide management's discussion of the Punjab facility, efficiency initiatives, capacity additions and margin priorities. Until that discussion is available, the reported numbers and the investor presentation remain the stated basis for assessing the quarter's financial performance.
Conclusion
Sanathan Textiles delivered consolidated revenue of ₹1,804 crore in Q2 FY27, up 120.5% year on year, alongside EBITDA of ₹154.7 crore and PAT of ₹61.2 crore. The Punjab facility ramp-up and improved fixed-cost absorption were the reported drivers of the consolidated improvement, while standalone margins declined despite growth in standalone revenue and profits.
The next scheduled event is the November 5, 2026 earnings call. Investors will watch for management's comments on facility utilisation, further capacity expansion, efficiency measures and the company's stated focus on sustaining margins as its expanded operations scale up.