










Sandhar new-business loss widens to Rs 29.05 crore in H1
Key highlights
- Sandhar’s new-business revenue grew 34.5% to Rs 311.71 crore in H1 FY27.
- New-business EBITDA moved to a Rs 2.42 crore loss from a Rs 5.06 crore profit a year earlier.
- Sandhar’s new-business table reported a Rs 29.05 crore H1 FY27 PBT loss, while its project overview showed negative Rs 25.09 crore.
- New business had capital employed of Rs 424.97 crore and non-annualised ROCE of negative 3.72%.
powered by IRIS
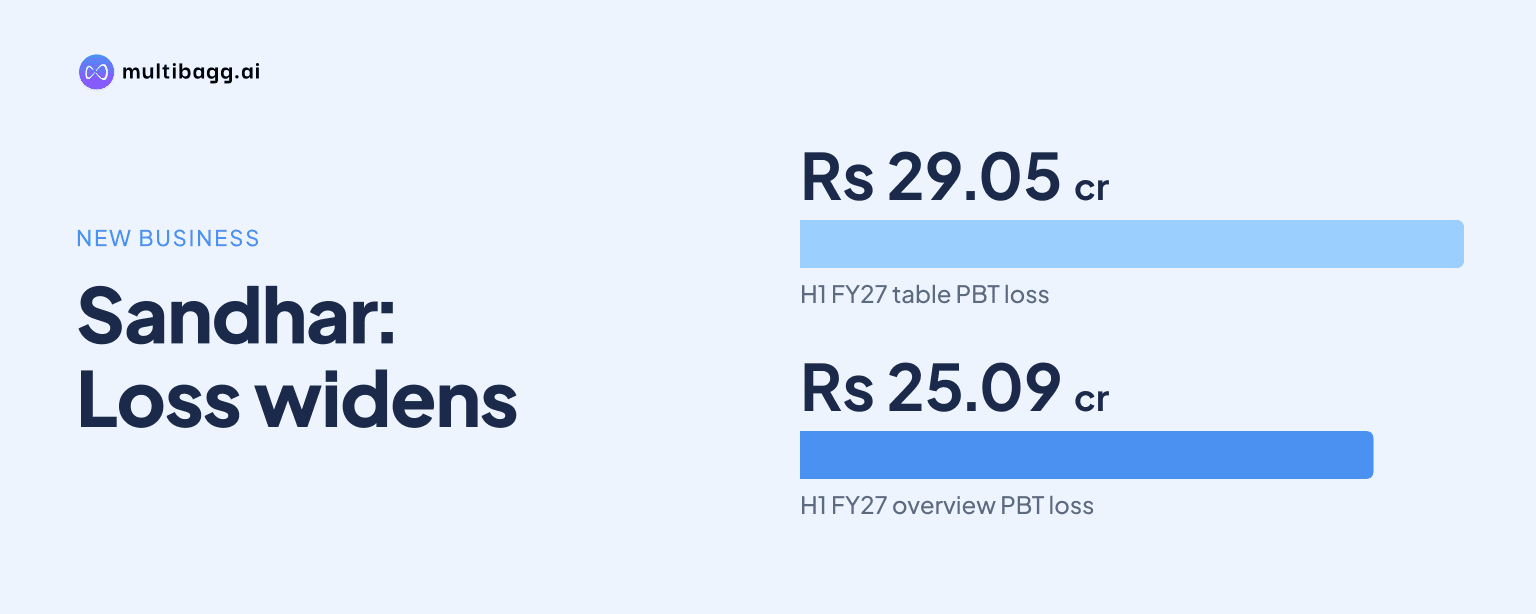
Sandhar Technologies Ltd reported a Rs 29.05 crore pre-tax loss in new business in H1 FY27, despite 34.5% year-on-year revenue growth to Rs 311.71 crore; EBITDA turned to a Rs 2.42 crore loss and non-annualised return on capital employed was negative 3.72%.
Know Sandhar Technologies inside out
Results, valuation, peers and who's buying, in one view.
What did Sandhar’s new business report in H1 FY27?
Sandhar’s new business reported Rs 311.71 crore of revenue from operations, negative earnings before interest, tax, depreciation and amortisation (EBITDA) of Rs 2.42 crore, and a Rs 29.05 crore loss before tax, or PBT, in H1 FY27. In H1 FY26, revenue was Rs 231.73 crore, EBITDA was positive at Rs 5.06 crore and the PBT loss was Rs 14.42 crore.
Revenue increased by Rs 79.98 crore year on year, while total expenses rose by Rs 87.44 crore to Rs 314.24 crore in H1 FY27. Consequently, the EBITDA margin moved from positive 2.2% in H1 FY26 to negative 0.8%, while the disclosed PBT margin declined from negative 6.2% to negative 8.0%.
In Q2 FY27, new-business revenue rose 35.1% to Rs 164.17 crore from Rs 121.51 crore a year earlier. EBITDA was negative Rs 5.47 crore against positive Rs 1.57 crore in Q2 FY26, and the reported PBT loss increased to Rs 16.88 crore from Rs 7.94 crore.
Why did Sandhar’s new-business growth not produce profit?
Sandhar’s new-business growth did not produce profit because H1 FY27 total expenses of Rs 314.24 crore exceeded total income of Rs 311.83 crore, creating a Rs 2.42 crore EBITDA loss. The segment’s Rs 0.11 crore of other income did not offset the difference between operating income and expenses.
Finance costs increased to Rs 9.30 crore from Rs 7.99 crore in H1 FY26, while depreciation rose to Rs 13.37 crore from Rs 11.49 crore. The listed EBITDA loss, finance costs and depreciation mathematically produce a Rs 25.09 crore loss, rather than the Rs 29.05 crore PBT loss shown in the new-business operating table.
Sandhar’s separate new-project overview, covering year to date September 2026, reports Rs 540 crore of investment, Rs 312 crore of revenue, negative EBITDA of Rs 2.42 crore and PBT of negative Rs 25.09 crore. The presentation does not provide a reconciliation between that Rs 25.09 crore figure and the Rs 29.05 crore loss stated in the new-business table.
The overview identifies five projects in initial stages: the acquired Hosur casting business, Sanaswadi cabins and fabrication in Pune, Chennai sheet-metal parts, an electric-vehicle powertrain business in Haryana, and seat-belt-spool operations in Romania. It does not allocate the Rs 540 crore investment or Rs 312 crore revenue among those five projects.
Got a follow-up? Ask IRIS
How did Sandhar’s new business affect consolidated performance?
Sandhar’s loss-making new business contrasted with its running business, which generated Rs 148.06 crore of PBT on H1 FY27 revenue of Rs 2,687.86 crore. The running business’s revenue increased 26.3% year on year, compared with 34.5% for new business, but its EBITDA margin was 9.7% versus negative 0.8% for the newer portfolio.
Running-business EBITDA increased 28.8% to Rs 263.15 crore in H1 FY27, and its PBT rose 55.2% from Rs 95.37 crore in H1 FY26. Sandhar separately reports H1 growth indicators excluding new projects of 26% for revenue, 29% for EBITDA and 55% for PBT.
The consolidated operating table displays PBT of Rs 122.97 crore for running and new business together, before non-recurring income and joint-venture profit. That subtotal aligns with the Rs 25.09 crore loss in the project overview when set against running-business PBT, rather than with the Rs 29.05 crore loss in the new-business table; Sandhar gives no reconciliation.
Reported consolidated profit after tax was Rs 93.31 crore in H1 FY27, down 8.0% from Rs 101.38 crore in H1 FY26. The earlier period included Rs 47.77 crore of non-recurring income, while the H1 FY27 presentation shows no non-recurring income and Rs 2.48 crore of profit share from joint ventures.
What return did Sandhar’s new business generate on capital employed?
Sandhar’s new business generated negative 3.72% return on capital employed, or ROCE, not annualised, on capital employed of Rs 424.97 crore. It recorded negative earnings before interest and tax, or EBIT, of Rs 15.79 crore in the capital-return table.
The running business had capital employed of Rs 1,471.17 crore, EBIT of Rs 174.60 crore and non-annualised ROCE of 11.87%. Consolidated capital employed was Rs 1,896.14 crore, with EBIT of Rs 158.81 crore and non-annualised ROCE of 8.38%.
The difference between new-business EBITDA of negative Rs 2.42 crore and EBIT of negative Rs 15.79 crore equals the Rs 13.37 crore depreciation listed for H1 FY27. The presentation does not disclose capital employed, EBIT or ROCE separately for the Hosur, Pune, Chennai, Haryana and Romania projects.
When does Sandhar expect its new projects to turn around?
Sandhar expects the Sanaswadi cabins and fabrication project in Pune to turn around in Q3 FY27 and the acquired Hosur casting business in Q4 FY27. It lists FY28 turnaround timing for the Chennai sheet-metal, Haryana electric-vehicle powertrain and Romania seat-belt-spool projects.
For the Hosur aluminium die-casting project, Sandhar says it has received 2,000 kilovolt of power and expects the remaining 2,000 kilovolt by January 2027. Trial runs have started, with relocation targeted for March 2027 and mass production targeted for April 2027.
At the Chennai sheet-metal project, Phase I has started and Phase II is expected to start by March 2027. Sandhar provides no revenue, EBITDA, PBT or ROCE forecast for any project after its stated turnaround date.
Conclusion
Sandhar’s H1 FY27 disclosure shows a new-business portfolio with Rs 311.71 crore of revenue but negative EBITDA, a reported Rs 29.05 crore PBT loss and negative 3.72% non-annualised ROCE. In contrast, the running business delivered Rs 263.15 crore of EBITDA and Rs 148.06 crore of PBT, illustrating the differing profitability of the two portfolios.
The next disclosed milestones are the Sanaswadi turnaround target in Q3 FY27, the Hosur turnaround target in Q4 FY27, and the Hosur relocation and mass-production targets of March and April 2027. Sandhar’s future disclosures will also need to clarify why the new-business table reports a Rs 29.05 crore PBT loss while the project overview and the listed cost bridge indicate Rs 25.09 crore.