










Sandhar restates H1 revenue growth at 28% after transfer
Key highlights
- Sandhar’s restated standalone H1 FY 27 comparison shows 28% revenue growth and 34% EBITDA growth.
- Rs 390 crore of H1 FY 26 standalone revenue shifted to wholly owned subsidiaries after restructuring.
- Reported standalone H1 FY 27 revenue was Rs 1,458.10 crore, down 4.9% year on year.
- Consolidated H1 FY 27 revenue rose 27% to Rs 2,999.57 crore.
powered by IRIS
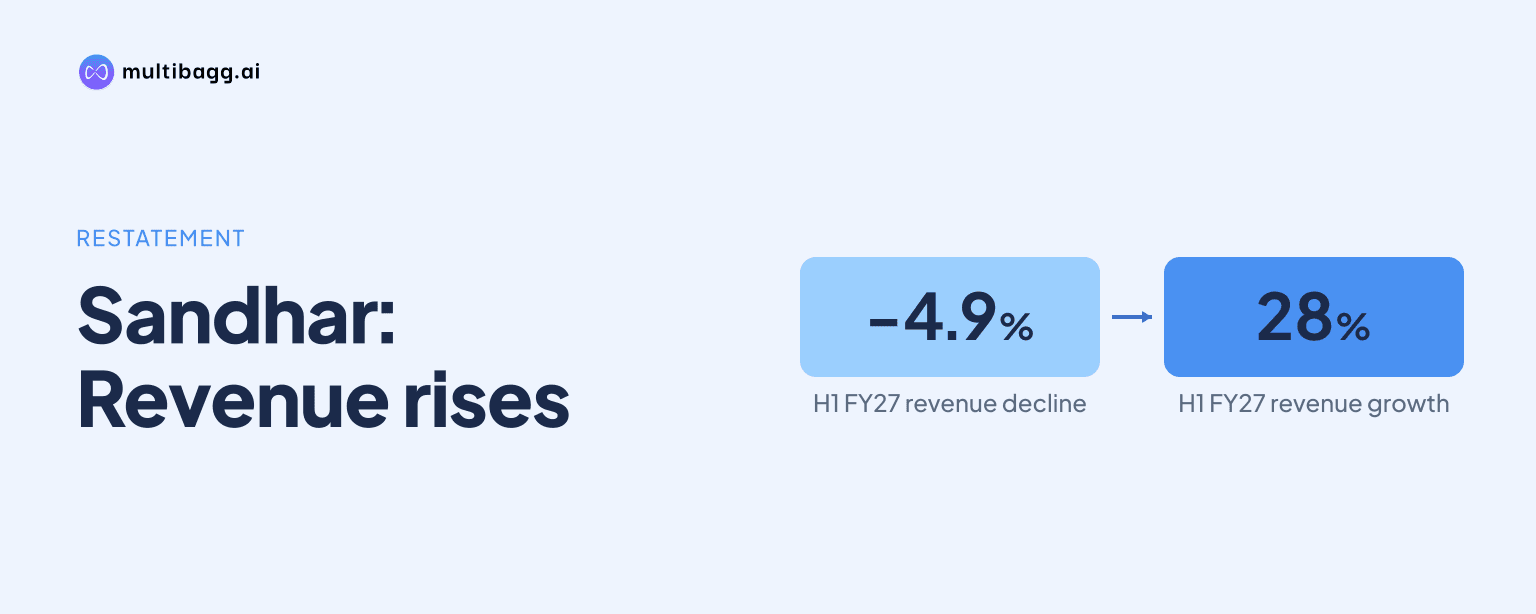
Sandhar Technologies Limited says its standalone H1 FY 27 revenue comparison is not like-for-like because Rs 390 crore of H1 FY 26 sales shifted to wholly owned subsidiaries; after excluding those transferred operations from the earlier base, Sandhar reports 28% revenue growth and 34% EBITDA growth.
Know Sandhar Technologies inside out
Results, valuation, peers and who's buying, in one view.
Why did Sandhar’s reported standalone revenue fall in H1 FY 27?
Sandhar’s reported standalone revenue fell because it restructured its sheet-metal fabrication and die-casting businesses into wholly owned subsidiaries through slump sales during the financial year ended 31 March 2026. The businesses transferred had generated Rs 390 crore of H1 FY 26 revenue and Rs 179 crore of Q2 FY 26 revenue while they remained within the standalone entity, according to Sandhar.
Reported standalone revenue from operations was Rs 1,458.10 crore in H1 FY 27, down 4.9% from Rs 1,533.15 crore in H1 FY 26. Q2 FY 27 revenue was Rs 792.14 crore, 1.6% below Rs 805.03 crore a year earlier, but 19.0% above Q1 FY 27 revenue of Rs 665.96 crore. Sandhar says the transferred businesses make these reported year-on-year standalone movements non-comparable.
What does Sandhar’s restated standalone comparison show?
Sandhar’s adjusted and restated standalone indicators show H1 FY 27 revenue growth of 28%, earnings before interest, tax, depreciation and amortisation, or EBITDA, growth of 34%, and profit before tax growth of 50%. Sandhar calculated these measures after eliminating the transferred sheet-metal and die-casting businesses from the corresponding H1 FY 26 standalone figures.
The gap between reported and restated growth stems from the Rs 390 crore of H1 FY 26 revenue that had been booked at the parent before the restructuring. On the reported basis, EBITDA before non-recurring income decreased to Rs 138.65 crore from Rs 141.85 crore, although the EBITDA margin rose to 9.38% from 9.19%. The restated 34% growth rate applies to a prior-year base stripped of the transferred activities.
Reported net profit also reflects non-recurring items and a wage-cost impact. H1 FY 26 standalone profit before tax included Rs 44.57 crore of non-recurring income, made up of Rs 34.01 crore from the Peenya plant land sale and Rs 10.56 crore of slump-sale profit. H1 FY 27 had no such income, while net profit included Rs 6.15 crore of cost related to higher minimum wages.
Got a follow-up? Ask IRIS
How did Sandhar’s consolidated results change in H1 FY 27?
Sandhar’s consolidated revenue increased 27% to Rs 2,999.57 crore in H1 FY 27 from Rs 2,360.46 crore in H1 FY 26 because the consolidated accounts include the parent, Indian subsidiaries and overseas business. Consolidated EBITDA before joint-venture profit and non-recurring income rose 24% to Rs 260.73 crore from Rs 209.44 crore, while the margin moved to 8.64% from 8.84%.
Indian business revenue increased 29% to Rs 2,741.35 crore in H1 FY 27 from Rs 2,120.16 crore, while overseas subsidiaries reported Rs 258.22 crore of revenue, up 7.5% in rupee terms. In euro terms, overseas revenue decreased 2.6% to EUR 23.49 million, but EBITDA increased 64.8% to EUR 2.50 million and earnings before tax remained negative at EUR 0.88 million.
Consolidated reported net profit declined 8.0% to Rs 93.31 crore from Rs 101.38 crore despite the revenue increase. Consolidated profit before tax before joint-venture profit and non-recurring income rose 51.9% to Rs 122.97 crore from Rs 80.95 crore, but H1 FY 26 included Rs 47.77 crore of non-recurring income and H1 FY 27 net profit included Rs 13.01 crore of higher minimum-wage cost.
Which operations and projects matter after Sandhar’s restructuring?
Sandhar’s portfolio identifies Sheet Metal & Allied and Castings, Machining & Tooling as significant business areas, with H1 FY 27 revenue of Rs 861 crore and Rs 765 crore respectively. Sheet Metal & Allied represented 29% of portfolio revenue, while Castings, Machining & Tooling represented 25%; the presentation lists sheet-metal operations under Sandhar Engineering Pvt Ltd and casting operations under wholly owned subsidiaries.
On a consolidated product basis, aluminium die casting represented 33.4% of H1 FY 27 revenue, up from 32.4% in H1 FY 26, while sheet metal increased to 18.9% from 18.1%. Cabins and fabrication declined to 9.8% from 11.2%, and the two-wheeler category’s share rose to 70.1% from 67.3% as passenger vehicle share fell to 10.8% from 13.6%.
Sandhar identified new projects carrying Rs 540 crore of investment and Rs 312 crore of revenue, with EBITDA loss of Rs 2.42 crore and profit-before-tax loss of Rs 25.09 crore. Its new-business segment recorded an H1 FY 27 EBITDA loss of Rs 2.42 crore, versus EBITDA of Rs 5.06 crore a year earlier, while running-business revenue rose 26.3% to Rs 2,687.86 crore.
Conclusion
The restructuring changes the legal entity reporting sheet-metal and die-casting activity, rather than removing that activity from Sandhar’s consolidated accounts. Reported standalone H1 FY 27 revenue declined 4.9% to Rs 1,458.10 crore, but Sandhar’s restated continuing-business comparison shows 28% revenue growth, 34% EBITDA growth and 50% profit-before-tax growth. Consolidated revenue increased 27% to Rs 2,999.57 crore.
The next disclosed milestones are the targeted March 2027 relocation and April 2027 mass production at the Hosur aluminium die-casting facility, where trial runs have begun. Sandhar also expects the Sanaswadi cabins and fabrication project to turn around in Q3 FY 27, the acquired casting business in Q4 FY 27, and the Chennai sheet-metal, EV powertrain and Romania projects in FY 28.