










Sangam (India) Limited Q2 FY27 PAT Rises 131% to Rs 53.40 Crore
Key highlights
- Sangam reported Q2 FY27 revenue of Rs 1,045.32 crore, up 32.96% year on year.
- Q2 FY27 PAT rose 130.87% year on year to Rs 53.40 crore.
- Operating profit increased 57.55% year on year to Rs 121.22 crore.
- H1 FY27 revenue was Rs 1,906 crore and PAT was Rs 94 crore.
powered by IRIS
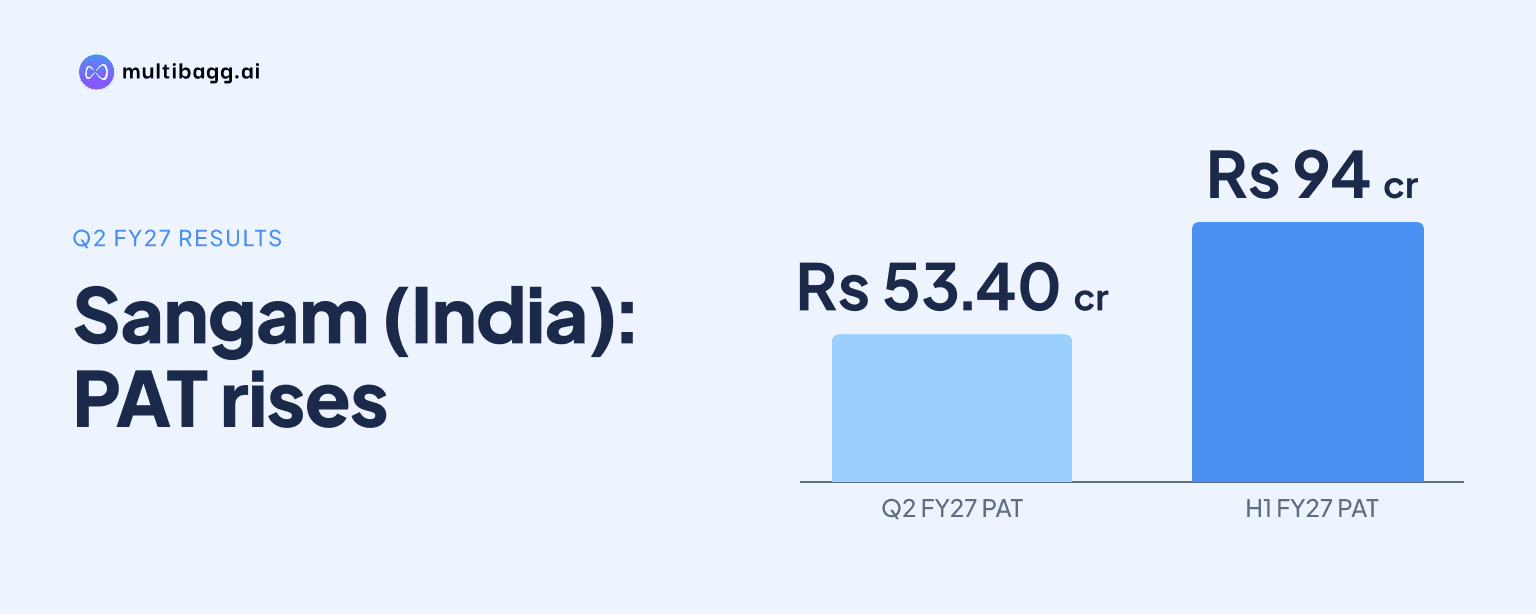
Sangam (India) Limited reported consolidated Q2 FY27 profit after tax of Rs 53.40 crore, up 130.87% year on year. Revenue rose 32.96% to Rs 1,045.32 crore for the quarter ended September 30, 2026, marking the first quarterly revenue above Rs 1,000 crore cited in its investor presentation.
Know Sangam Health Care Products inside out
Results, valuation, peers and who's buying, in one view.
What did Sangam report for Q2 FY27?
Sangam reported its highest quarterly revenue and profit figures in the available Q2 FY27 disclosures. Consolidated revenue was Rs 1,045.32 crore, compared with Rs 786.18 crore in Q2 FY26. Profit after tax rose to Rs 53.40 crore from Rs 23.13 crore in the year-earlier quarter.
The company said in its presentation that quarterly revenue had crossed Rs 1,000 crore for the first time. Management described revenue of about Rs 1,045 crore, EBITDA of Rs 127 crore and PAT of about Rs 53 crore as record quarterly results. Separately, the detailed quarterly-results data reported operating profit of Rs 121.22 crore, up 57.55% year on year. The disclosures use different labels for these profitability measures and do not provide a reconciliation between them.
How did Sangam's first-half FY27 performance compare with the prior year?
Sangam reported H1 FY27 revenue of Rs 1,906 crore and PAT of Rs 94 crore for the six months ended September 30, 2026. The company said first-half PAT had already exceeded the profit it earned during the whole previous financial year, although the presentation did not state the prior full-year PAT figure.
The first-half result follows Q1 FY27 revenue of Rs 867 crore and PAT of Rs 41 crore. In that quarter, revenue was 8.1% higher year on year, while EBITDA was Rs 112 crore compared with Rs 70 crore in Q1 FY26. The Q1 presentation put EBITDA margin at 12.9%, against 8.8% in the corresponding prior-year period.
Management had previously referred to an objective of doubling FY27 PAT. During the subsequent discussion, it clarified that this was an aspiration rather than formal financial guidance. That distinction is relevant because investors should not treat the statement as a committed earnings target.
What was disclosed through the investor presentation?
Sangam informed stock exchanges that it had submitted an investor presentation covering unaudited financial results for Q2 and H1 FY27. The presentation, which is also available on the company's website, gives shareholders and other stakeholders access to the reported financial-period information.
The exchange communication concerning the submission itself did not contain revenue, profit, margin or operating details. Those figures emerged from the presentation and the reported consolidated results released on November 4, 2026. The company had also scheduled an earnings conference call for November 5, 2026 at 1:00 PM IST, with Managing Director Anurag Soni and senior management expected to discuss the quarterly and half-year performance.
This sequence matters because an exchange filing that announces a presentation is not, by itself, a complete financial-results release. Investors assessing Sangam's performance need to distinguish between the filing notice and the underlying presentation or consolidated results that contain the financial data.
Got a follow-up? Ask IRIS
How do the Q2 results affect investors and the textile business outlook?
The Q2 numbers show that Sangam's profit grew faster than revenue during the reported period. Revenue increased 32.96%, operating profit increased 57.55%, and PAT increased 130.87% from the year-earlier quarter. The reported EBITDA margin improvement of 180 basis points also points to stronger operating profitability relative to sales.
For investors, the Rs 94 crore H1 PAT is the key cumulative measure because it exceeded the previous full-year profit according to management. However, the company has not provided formal FY27 earnings guidance in the material provided. The stated aspiration to double annual PAT therefore remains separate from an official forecast.
The figures also place the Q2 performance in the context of a stronger first half after Q1. Still, the available disclosures do not provide segment-level drivers, customer demand details, capacity information, cash-flow data or an explanation for the difference between the presentation's EBITDA figure and the separately reported operating-profit figure. These limitations leave some operating questions unanswered.
Why is the Q2 result important for Sangam's financial track record?
The Q2 result is important because Sangam recorded its first reported quarter with revenue above Rs 1,000 crore while also posting its highest quarterly PAT in the information provided. The combination of higher sales, operating profit and net profit indicates that the improvement was not limited to the top line.
The pace of earnings growth was notably higher than revenue growth in the quarter. PAT rose by about Rs 30.27 crore from Q2 FY26, while revenue increased by about Rs 259.14 crore. The company also reported H1 revenue of Rs 1,906 crore, showing that the second-quarter milestone followed a Rs 867 crore revenue base in the first quarter.
The next comparable disclosures will be important for determining whether the reported margin improvement and higher profit level are sustained. Investors will also need to monitor any later clarification on annual targets, operating drivers and the reported profitability metrics.
Conclusion
Sangam's Q2 FY27 disclosures show consolidated revenue of Rs 1,045.32 crore and PAT of Rs 53.40 crore, with net profit increasing 130.87% year on year. The Rs 94 crore H1 PAT, which management said was above the previous full-year profit, makes the first-half performance significant for assessing the company's earnings trajectory.
The next points to watch are management's discussion of operating drivers, any formal FY27 guidance, and future disclosures that clarify profitability measures. The company had scheduled its Q2 and H1 FY27 earnings call for November 5, 2026, following the November 4 results announcement.