










Transpek Industry Ltd profit falls 42.7% ahead of Q2 results
Key highlights
- Transpek reported June 2026 net sales of ₹151.06 crore, down 2.1% from ₹154.23 crore a year earlier.
- June-quarter net profit fell 42.7% year on year to ₹8.93 crore from ₹15.58 crore.
- EBITDA declined 32.4% to ₹24.14 crore and EBITDA margin was reported at 15.6%.
- Transpek's board will consider Q2 FY27 and half-year results on 13 November 2026.
powered by IRIS
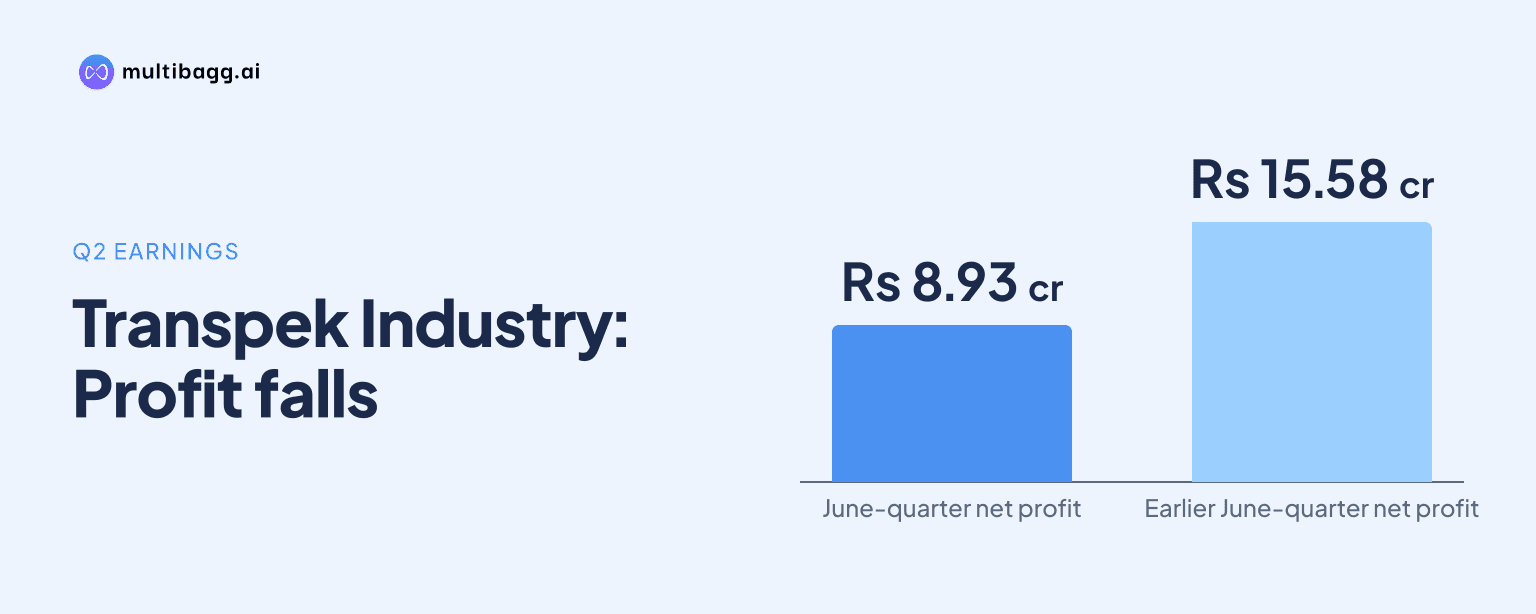
Transpek Industry Ltd reported net profit of ₹8.93 crore for the quarter ended 30 June 2026, down 42.7% from ₹15.58 crore a year earlier, ahead of its board meeting on 13 November 2026 to consider Q2 FY27 and first-half results. The June-quarter decline puts margins, revenue recovery and management's FY27 growth plan under focus.
Know Transpek Industry inside out
Results, valuation, peers and who's buying, in one view.
What did Transpek report for the June 2026 quarter?
Transpek reported consolidated net sales of ₹151.06 crore in the June 2026 quarter, compared with ₹154.23 crore in the corresponding quarter a year earlier, a decline of 2.1%. Net profit fell to ₹8.93 crore from ₹15.58 crore. Earnings per share declined to ₹15.98 from ₹27.90 in the year-earlier quarter.
The company also reported total income of ₹155.06 crore, including ₹4 crore of other income, compared with ₹165.89 crore a year earlier. The difference between net sales and total income is important when assessing quarterly performance: net sales capture revenue from operations, while total income also includes other income. Total expenses rose marginally to ₹130.92 crore from ₹130.18 crore despite the decline in sales.
Sequentially, Transpek's performance improved from the March 2026 quarter. Net sales rose from ₹148.22 crore, while net profit increased from ₹6.58 crore. Operating profit improved to ₹20.14 crore from ₹17.72 crore, but it remained below ₹24.05 crore recorded in the June 2025 quarter.
Why did Transpek's profitability weaken year on year?
Transpek's profitability weakened because input-cost pressure compressed operating margins even as expenses remained broadly stable. The reported data attributes the year-on-year profit decline to elevated raw-material costs, particularly sulphur and chlorine. EBITDA fell 32.4% to ₹24.14 crore, a sharper drop than the 2.1% decline in net sales.
EBITDA margin was reported at 15.6% in Q1 FY27, compared with 21.5% in Q1 FY26. This reduction shows that the company retained less operating profit from each rupee of revenue than it did a year earlier. EBIT fell to ₹13.30 crore from ₹23.39 crore, while profit before tax fell to ₹11.79 crore from ₹20.93 crore.
The June quarter also included a stock adjustment of negative ₹14.56 crore, compared with a negative ₹0.22 crore in the prior-year period. The financial statements show this movement alongside operating costs, but the supplied information does not provide a separate explanation for the adjustment. Investors will therefore need the company's results commentary to assess its effect on costs and profitability.
Got a follow-up? Ask IRIS
What should investors check in Transpek's Q2 FY27 results?
Investors should check whether Transpek has restored sales growth, limited input-cost pressure, progressed its acid chloride initiative and retained its FY27 growth guidance. The board is scheduled to meet at 2:00 p.m. on 13 November 2026 to consider unaudited standalone and consolidated results for the quarter and half year ended 30 September 2026.
First, revenue will show whether the June-quarter sales decline was temporary. Management has framed FY27 revenue growth at 15-20%, while stating at least 15% growth. Meeting that objective requires a materially stronger performance over the rest of the financial year than the 2.1% year-on-year decline in June-quarter net sales.
Second, investors will assess EBITDA and net-profit margins for any evidence that sulphur and chlorine cost pressures are easing. Third, they will look for an update on the high-volume acid chloride business, for which management indicated a goal of about ₹15 crore, versus ₹4 crore in the previous year. The disclosed information does not provide Q2 figures in advance of the board meeting.
When will Transpek release its September-quarter numbers?
Transpek is expected to release its September-quarter and half-year numbers after its board meeting on 13 November 2026. The company informed BSE on 4 November that its board would meet through audio-visual means to consider and approve unaudited standalone and consolidated financial results for Q2 FY27 and the half year ended 30 September 2026.
The results timetable falls within the regulatory framework requiring listed companies to publish quarterly results within 45 days of the quarter end. For the January-March quarter, the permitted period is 60 days. The notice was issued under Regulation 29 of the SEBI Listing Obligations and Disclosure Requirements Regulations, 2015.
The June 2026 results were last reported on 7 August 2026. Auditors provided unmodified limited-review reports, while results of three small subsidiaries were unreviewed and described as not material to the group. Until the 13 November meeting concludes, no financial figures for the September quarter have been disclosed.
Conclusion
Transpek's June-quarter numbers show a company facing weaker year-on-year sales and a much steeper reduction in profit as operating margins narrowed. Net sales of ₹151.06 crore were slightly below the prior-year period, but EBITDA and net profit declined 32.4% and 42.7%, respectively, making raw-material costs and margin recovery central to the investment assessment.
The next key disclosure is the Q2 FY27 and first-half result expected after the 13 November 2026 board meeting. Investors should watch whether Transpek maintains its at-least-15% FY27 revenue-growth framing, reports progress toward the ₹15 crore acid chloride goal, and provides evidence of improved profitability after the June-quarter margin pressure.