










Sarthak Metals FY26 recovery trails FY22 as cycles stretch
Key highlights
- Sarthak Metals reported FY26 revenue of Rs 192.25 crore, compared with Rs 178.42 crore in FY25 and Rs 457.30 crore in FY22.
- Sarthak Metals’ FY26 profit after tax was Rs 4.61 crore, up from Rs 4.12 crore in FY25 but below Rs 29.76 crore in FY23.
- Sarthak Metals’ provisional working-capital cycle was 173 days in FY26, versus 205 days in FY25 and 48 days in FY22.
- Sarthak Metals reported FY26 inventory days of 63 and receivable days of 94, compared with 23 days each in FY22.
powered by IRIS
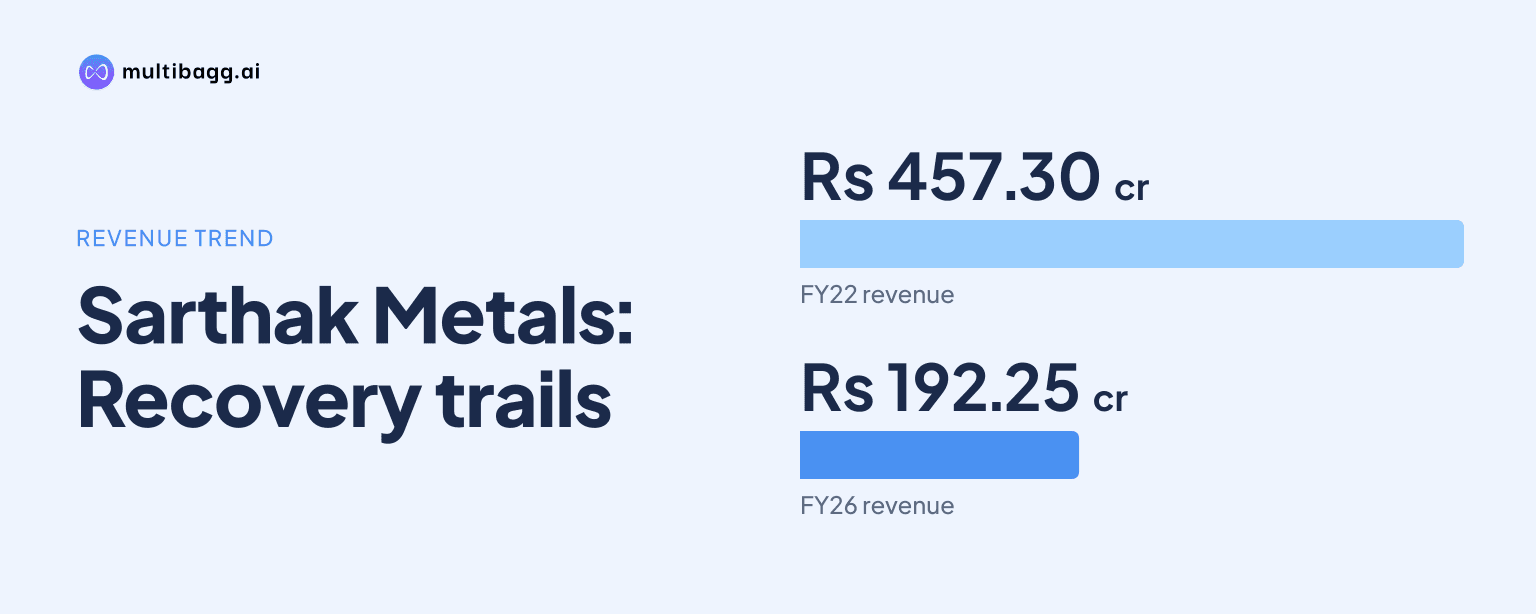
Sarthak Metals Limited’s FY26 recovery remained below FY22, with revenue of Rs 192.25 crore versus Rs 457.30 crore and profit after tax of Rs 4.61 crore versus Rs 27.48 crore, while provisional working-capital days were 173 compared with 48. FY26 revenue and profit improved from FY25, but operating-cycle measures remained substantially longer than at the start of the five-year series.
Know Sarthak Metals inside out
Results, valuation, peers and who's buying, in one view.
How has Sarthak Metals’ revenue changed over five years?
Sarthak Metals’ revenue from operations rose to Rs 192.25 crore in FY26 from Rs 178.42 crore in FY25, ending a three-year decline, but remained below the Rs 457.30 crore reported in FY22. Revenue fell to Rs 408.43 crore in FY23 and Rs 305.17 crore in FY24 before reaching the five-year low in FY25.
The FY26 increase was Rs 13.83 crore, while revenue remained Rs 265.05 crore below FY22. Over the same period, equity increased from Rs 77.94 crore in FY22 to Rs 142.27 crore in FY26, and the assets turnover ratio declined from 4.4 times to 1.5 times. The presentation does not state the reasons for the revenue movement or the change in asset turnover.
The 1.5-times assets turnover ratio was unchanged between FY25 and FY26 despite the revenue increase. It was 4.4 times in FY22, when revenue was Rs 457.30 crore, compared with Rs 192.25 crore in FY26. The reported figures therefore show that the FY26 sales increase did not coincide with a change in this ratio.
Did Sarthak Metals’ profitability recover in FY26?
Sarthak Metals’ profit after tax rose to Rs 4.61 crore in FY26 from Rs 4.12 crore in FY25, while earnings before interest, tax, depreciation and amortisation, or EBITDA, excluding other income and exceptional items increased to Rs 7.9 crore from Rs 7 crore. Both measures remained below FY24, FY23 and FY22 levels.
EBITDA margin increased to 4.1% in FY26 from 3.9% in FY25, after falling from 10.6% in FY23 and 7.1% in FY24. The FY26 margin improvement of 0.2 percentage points accompanied the Rs 13.83 crore revenue increase, but the margin was still 5.0 percentage points below FY22’s 9.1%.
Return on capital employed, or ROCE, was provisionally estimated at 4.03% in FY26, down from 5.74% in FY25 and 45.70% in FY22. Equity rose by Rs 22.06 crore from FY25 to Rs 142.27 crore in FY26. Debt to equity was 0.05 times in FY26, after being reported as 0.00 times from FY23 through FY25.
Got a follow-up? Ask IRIS
Why did Sarthak Metals’ working-capital cycle become longer?
The presentation does not state why Sarthak Metals’ working-capital cycle lengthened; it reports provisional working-capital days of 173 in FY26, compared with 48 days in FY22. The measure improved from 205 days in FY25, but it had increased in each prior year, from 48 days in FY22 to 68 days in FY23 and 79 days in FY24.
Inventory days rose to 63 in FY26 from 49 in FY25 and 23 in FY22. This was the highest inventory figure in the five-year series, exceeding 13 days in FY23 and 21 days in FY24. FY26 inventory days were 40 days higher than FY22 even though FY26 revenue was Rs 265.05 crore lower than the FY22 level.
Trade receivables, presented in days, increased to 94 in FY26 from 84 days in FY25 and 23 days in FY22. The period rose from 13 days in FY23 to 56 days in FY24, then increased for two further years. Both inventory and receivable periods were longer in FY26, while the overall working-capital measure improved only against FY25.
What do Sarthak Metals’ shareholder-return measures show?
Sarthak Metals’ ROCE fell from 45.70% in FY22 to a provisional 4.03% in FY26, while dividend per share declined from Rs 2 in FY22 and FY23 to Rs 0 in FY26. Dividend per share was Rs 1 in FY24 and Rs 0.5 in FY25. The presentation does not disclose a dividend target or a ROCE target.
The shareholding pattern shows promoters with 68.81%, public shareholders with 31.05% and foreign institutional investors, or FIIs, with 0.14%. These displayed categories total 100.00%. The presentation also compares indexed share-price performance with the BSE Sensex from the November 25, 2021 BSE Main Board listing, but does not give precise chart-end values.
Conclusion
Sarthak Metals reported a FY26 improvement from FY25 in revenue, profit after tax, EBITDA and EBITDA margin, but its revenue, profit, margin, ROCE and asset turnover remained below FY22 and FY23 levels. At the same time, provisional working-capital days of 173, inventory days of 63 and receivable days of 94 indicate substantially more capital was tied up in operating-cycle measures than in FY22.
The next point to watch is confirmation of the FY26 provisional estimates for working capital and ROCE, as well as whether inventory and receivable days reverse from 63 and 94 days. Management disclosed no numerical revenue, margin, return or working-capital target in the presentation, leaving subsequent reported operating metrics as the available measure of whether the FY26 recovery is sustained.