










Fusion CX cuts top-five exposure as BFSI and healthcare grow
Key highlights
- Fusion CX’s top-five-client revenue share fell to 36.5% in Q2FY27 from 42.5% in Q2FY26.
- Fusion CX’s BFSI share rose to 18.2% and Healthcare and Life Sciences reached 14.5% in Q2FY27.
- Fusion CX’s Telecom and Other Utilities share declined to 39.2% in Q2FY27 from 48.6% a year earlier.
- Fusion CX’s nearshore delivery share increased to 39.7% in Q2FY27 from 29.1% in Q2FY26.
powered by IRIS
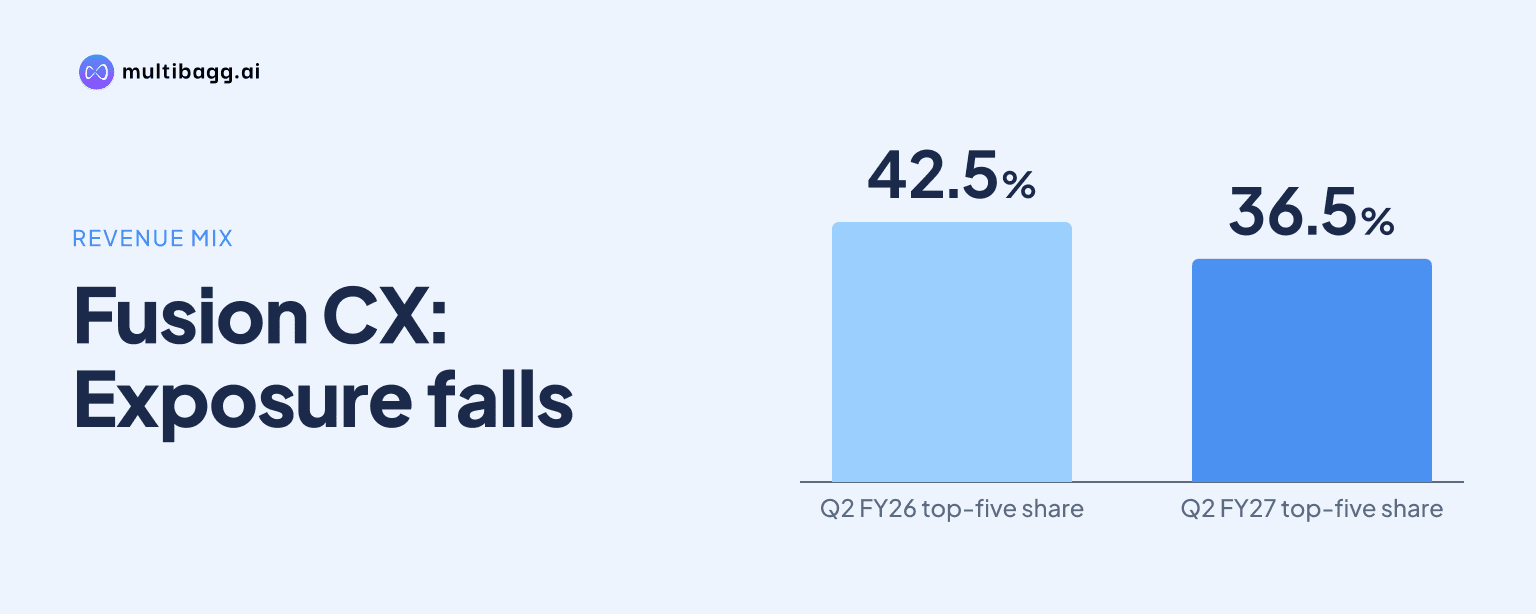
Fusion CX Limited reduced its top-five-client revenue concentration to 36.5% in Q2FY27 from 42.5% a year earlier, while Banking, Financial Services & Insurance (BFSI) and Healthcare and Life Sciences increased to 18.2% and 14.5% of revenue. The shift coincided with Telecom and Other Utilities falling to 39.2%, and nearshore delivery representing 39.7%.
Know Fusion CX inside out
Results, valuation, peers and who's buying, in one view.
How did Fusion CX’s client concentration change?
Fusion CX lowered revenue exposure to its five largest clients by 6 percentage points year on year in Q2FY27. The top-five group accounted for 36.5% of revenue, compared with 42.5% in Q2FY26 and 38.6% in Q1FY27. This was also a 2.1-percentage-point sequential reduction from the preceding quarter.
The change extended to the top 10 clients, whose share declined to 48.9% in Q2FY27 from 52.1% in Q2FY26 and 49.7% in Q1FY27. The year-on-year fall was 3.2 percentage points, smaller than the decline in the top-five measure. The figures show that client revenue became less concentrated at both reported levels during the quarter.
Fusion CX reported Q2FY27 revenue from operations of Rs 525.3 crore, up 22.1% from Rs 430.3 crore in Q2FY26 and 7.1% from Rs 490.5 crore in Q1FY27. The lower top-five and top-10 shares were therefore reported alongside growth in the quarterly revenue base, rather than a reported decline in revenue from operations.
Which verticals drove Fusion CX’s business mix shift?
Fusion CX’s mix shifted toward BFSI and Healthcare and Life Sciences in Q2FY27, while Telecom and Other Utilities remained the largest vertical but lost share. BFSI reached 18.2% of revenue from 13.7% in Q2FY26, a gain of 4.5 percentage points. Healthcare and Life Sciences rose 3.1 percentage points to 14.5% from 11.4% over the same period.
Telecom and Other Utilities declined to 39.2% of Q2FY27 revenue from 48.6% in Q2FY26, reducing its share by 9.4 percentage points. It also fell from 43.5% in Q1FY27. Despite that reduction, the vertical remained larger than each of the other four reported verticals, including BFSI at 18.2% and High-Tech Growth & Travel at 16.1%.
High-Tech Growth & Travel increased to 16.1% in Q2FY27 from 14.7% a year earlier and 15.7% in Q1FY27. Retail and Home Services was 12.0%, compared with 11.6% in Q2FY26 but below 13.3% in Q1FY27. Together, BFSI and Healthcare and Life Sciences made up 32.7% of revenue in Q2FY27, versus 25.1% in Q2FY26.
Got a follow-up? Ask IRIS
How did Fusion CX’s delivery-centre and geographic mix change?
Fusion CX’s nearshore centres accounted for 39.7% of Q2FY27 revenue, becoming the largest reported delivery model. Nearshore share was 29.1% in Q2FY26, an increase of 10.6 percentage points, and was broadly unchanged from 39.9% in Q1FY27. The reported movement made nearshore larger than onshore at 33.3% and offshore at 27.0% in the latest quarter.
Onshore revenue share fell to 33.3% in Q2FY27 from 44.7% a year earlier, a reduction of 11.4 percentage points, but rose from 32.0% in Q1FY27. Offshore increased modestly year on year to 27.0% from 26.2%, while declining from 28.2% sequentially. These three delivery shares total 100%, showing a reallocation within Fusion CX’s reported delivery-centre mix.
The United States and Canada remained Fusion CX’s principal geography at 81.0% of Q2FY27 revenue, though this was below 82.1% in Q2FY26 and 84.1% in Q1FY27. India represented 9.9%, down from 13.0% a year earlier and unchanged sequentially. Australia and Others increased to 4.8% from 0.3% in Q2FY26, while Europe, Middle East and Africa, or EMEA, was 4.3% versus 4.7%.
Fusion CX employed 15,101 people at the Q2FY27 closing date, up from 12,401 a year earlier and 13,735 at the end of Q1FY27. Annualised revenue per employee was unchanged at Rs 14 lakh across Q2FY27, Q2FY26 and Q1FY27. Annualised voluntary attrition was 29.4%, compared with 29.9% year on year and 31.2% sequentially.
What do Fusion CX’s Q2 and H1 financial results show?
Fusion CX reported Q2FY27 revenue from operations of Rs 525.3 crore and profit after tax of Rs 58.6 crore. Revenue increased 22.1% year on year and 7.1% quarter on quarter, while profit after tax increased 31.3% year on year and 5.4% sequentially. The Q2 profit-after-tax margin was 11.2%, compared with 10.4% in Q2FY26 and 11.3% in Q1FY27.
Earnings before interest, tax, depreciation and amortisation, or EBITDA, were Rs 97.6 crore in Q2FY27, up 15.2% from Rs 84.7 crore a year earlier. EBITDA margin was 18.6%, below 19.7% in Q2FY26 and 19.4% in Q1FY27. Other income rose to Rs 15 crore from Rs 6 crore year on year, contributing to total income of Rs 540.3 crore in the quarter.
For H1FY27, revenue from operations reached Rs 1,015.8 crore, up 20.4% from Rs 843.4 crore in H1FY26. H1 EBITDA rose 27.7% to Rs 192.7 crore, and its margin increased to 19.0% from 17.9%. H1 profit after tax increased 56.3% to Rs 114.2 crore, with margin rising to 11.2% from 8.7%.
Fusion CX reported days sales outstanding, or DSO, of 73 days in Q2FY27, compared with 83 days in Q2FY26 and 77 days in Q1FY27. Its debt-to-equity ratio was 0.5 times, versus 0.6 times a year earlier and 0.4 times in Q1FY27. As of 30 September 2026, trade receivables were Rs 417.7 crore and cash and cash equivalents were Rs 58.6 crore.
Conclusion
Fusion CX’s Q2FY27 metrics show a reported broadening of both its client and sector mix. Top-five-client exposure fell to 36.5%, while BFSI and Healthcare and Life Sciences together reached 32.7% of revenue and Telecom and Other Utilities declined to 39.2%. Nearshore delivery rose to 39.7%, exceeding the 33.3% onshore and 27.0% offshore shares.
The presentation does not disclose a mix target or a delivery-centre expansion plan, leaving the persistence of the Q2FY27 changes unresolved. The next reported results will show whether top-10 concentration remains below 50%, nearshore remains near 39.7%, and revenue growth continues from the H1FY27 base of Rs 1,015.8 crore.