










SBI Life maintains FY27 IRP goal after 12% H1 growth
Key highlights
- SBI Life’s H1 FY27 individual rated premium was Rs 9,720 crore, up 12% year on year.
- SBI Life retained its FY27 individual rated premium growth guidance of 14% to 15%.
- SBI Life reported H1 FY27 VNB of Rs 3,270 crore, up 19%, with a 27.9% margin.
- Guaranteed non-participating savings business increased 27% to Rs 2,470 crore in H1 FY27.
powered by IRIS
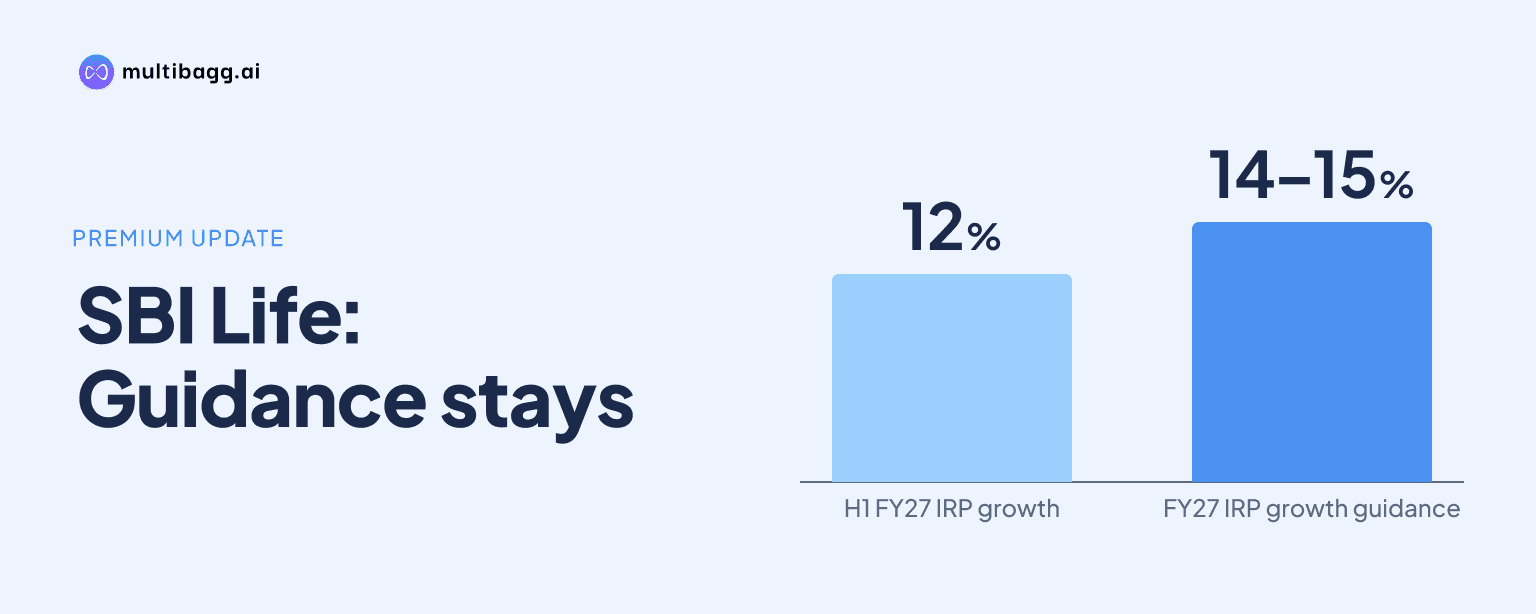
SBI Life maintained its 14% to 15% individual rated premium growth target for FY27 after individual rated premium rose 12% year on year to Rs 9,720 crore in the first half ended September 30, 2026. Management expects its historically stronger third quarter to lift growth during the second half.
Know SBI Life Insurance Company inside out
Results, valuation, peers and who's buying, in one view.
Can SBI Life meet its FY27 IRP target?
SBI Life says it can meet its 14% to 15% FY27 individual rated premium, or IRP, growth target despite first-half growth of 12%. Management said it remains committed to the full-year target and does not base its view on quarter-to-quarter or month-to-month movements.
The first-half result leaves a gap to close. IRP was Rs 9,720 crore in H1 FY27, while SBI Life’s three-year compound annual growth rate, or CAGR, for IRP was 11%. Management said first-quarter growth exceeded 15%, but the second quarter was slightly subdued, pulling the first-half rate to 12%.
Management also said H1 growth was at the same level as industry growth, while its objective for the full year remains to grow faster than the industry. It did not disclose an October sales figure, a second-half IRP target or a quarterly target that would quantify the required acceleration.
Why does SBI Life expect a stronger second half?
SBI Life expects a stronger second half because management said its third-quarter growth rate has normally been higher and it expects that seasonal pattern to continue in FY27. The company identified the bancassurance channel as central to that expectation after a softer second quarter.
State Bank of India and regional rural bank bancassurance contributed 53% of total annualised premium equivalent, or APE, during H1 FY27. Individual APE from this channel was Rs 5,990 crore, up 10% year on year, and SBI Life said the network had more than 64,000 customer insurance facilitators.
SBI branch productivity was Rs 50 lakh of individual APE for the period ended September 2026. Management said all products are available through all channels and distributors, but acknowledged that the uptake in the agency channel had been slightly better than in bancassurance.
Agency individual APE rose 12% to Rs 3,200 crore as of September 2026, while SBI Life added more than 72,000 agents on a gross basis and opened 14 branches. Other channels, including direct, corporate agents, other banks, brokers, online and web aggregators, grew 67% and accounted for 19% of total APE.
Which products are adding to SBI Life’s growth?
SBI Life is increasing the contribution of non-unit-linked products while unit-linked insurance plans, or ULIPs, remain its largest product group. ULIP APE was Rs 6,020 crore and represented 62% of the H1 FY27 product mix, compared with 65% in H1 FY26.
Guaranteed non-participating savings business grew 27% year on year to Rs 2,470 crore for the period ended September 2026. Participating-product APE was Rs 510 crore, up 9%, while sum assured in the participating segment rose 40% during the period.
Individual protection APE rose 16% to Rs 430 crore, while pure protection grew 26% on an individual APE basis. Including riders, individual protection APE grew 30%, and rider attachment reached nearly 49% of eligible individual policies.
Group protection APE increased 134% to Rs 1,600 crore, while total annuity and pension new business underwritten was Rs 4,620 crore. Management said it plans to launch a regular-pay deferred annuity product soon and expects its margin to be similar to or potentially above the company margin, without providing a volume estimate.
Got a follow-up? Ask IRIS
How are margins tracking against SBI Life’s growth plan?
SBI Life reported value of new business, or VNB, of Rs 3,270 crore in H1 FY27, up 19%, exceeding the 12% IRP growth rate. Its VNB margin was 27.9% in the first half and 29.3% in the second quarter.
Management attributed the second-quarter margin movement particularly to an improved product mix. It retained its VNB margin guidance range of 26% to 28%, saying its objective is to optimise VNB rather than revise the range after one quarter’s outcome.
SBI Life said it revised customer returns during the second quarter and prices products uniformly across channels. Management said product repricing in response to market yield movements will continue through the third and fourth quarters, but it did not disclose the VNB contribution from guaranteed non-participating savings.
Profit after tax rose 17% to Rs 1,270 crore in H1 FY27. SBI Life said the goods and services tax, or GST, impact was Rs 530 crore; excluding that impact, it calculated profit after tax at Rs 1,690 crore, up 39% year on year.
What operating measures support SBI Life’s outlook?
SBI Life entered the second half with gross written premium of Rs 48,400 crore, up 13% year on year, and renewal premium of Rs 28,150 crore, up 15%. Renewal premium represented 58% of gross written premium in H1 FY27, providing a larger contribution than new business premium alone.
Assets under management were Rs 5.3 lakh crore as of September 30, 2026, up 9% year on year, while embedded value was Rs 87,350 crore, up 15%. Operating return on embedded value was 18.8%, and solvency was 1.97 against the regulatory requirement of 1.50.
Persistency improved across reported individual regular-premium cohorts. The 13th-month persistency ratio was 87.6%, up 44 basis points year on year; the 25th-month ratio was 78.4%, up 110 basis points; and the 49th-month ratio was 69.3%, up 40 basis points.
Reported operating-expense ratio was 6.9% in H1 FY27, compared with 6.2% a year earlier, while total cost ratio was 11.7% against 10.9%. Excluding GST, the operating-expense ratio was 5.8%, which SBI Life said was in line with the prior year.
Conclusion
SBI Life’s unchanged FY27 target requires growth to move above the 12% recorded in the first half, but the company is relying on its usual third-quarter seasonal uplift, a bancassurance channel contributing 53% of APE, and faster expansion in agency and other distribution channels. Product mix has also shifted, with ULIP share declining by 3 percentage points while guaranteed non-participating savings and protection lines expanded.
The next disclosure to watch is third-quarter IRP growth and whether bancassurance sales recover after the subdued second quarter. Management also plans to improve sales of non-participating savings and annuity products through bancassurance in the coming quarter and half year, while it expects to launch a regular-pay deferred annuity product soon.