










Scoda Tubes Limited exports lift H1 revenue as domestic falls
Key highlights
- Scoda Tubes’ H1 FY27 exports rose 59.4% to Rs 112.9 crore.
- Exports accounted for 41% of Scoda Tubes’ H1 FY27 revenue, up from 29% in H1 FY26.
- Scoda Tubes’ H1 FY27 domestic revenue fell 6.6% to Rs 160.4 crore.
- Scoda Tubes reported H1 FY27 revenue from operations of Rs 273.3 crore, up 12.6% year on year.
powered by IRIS
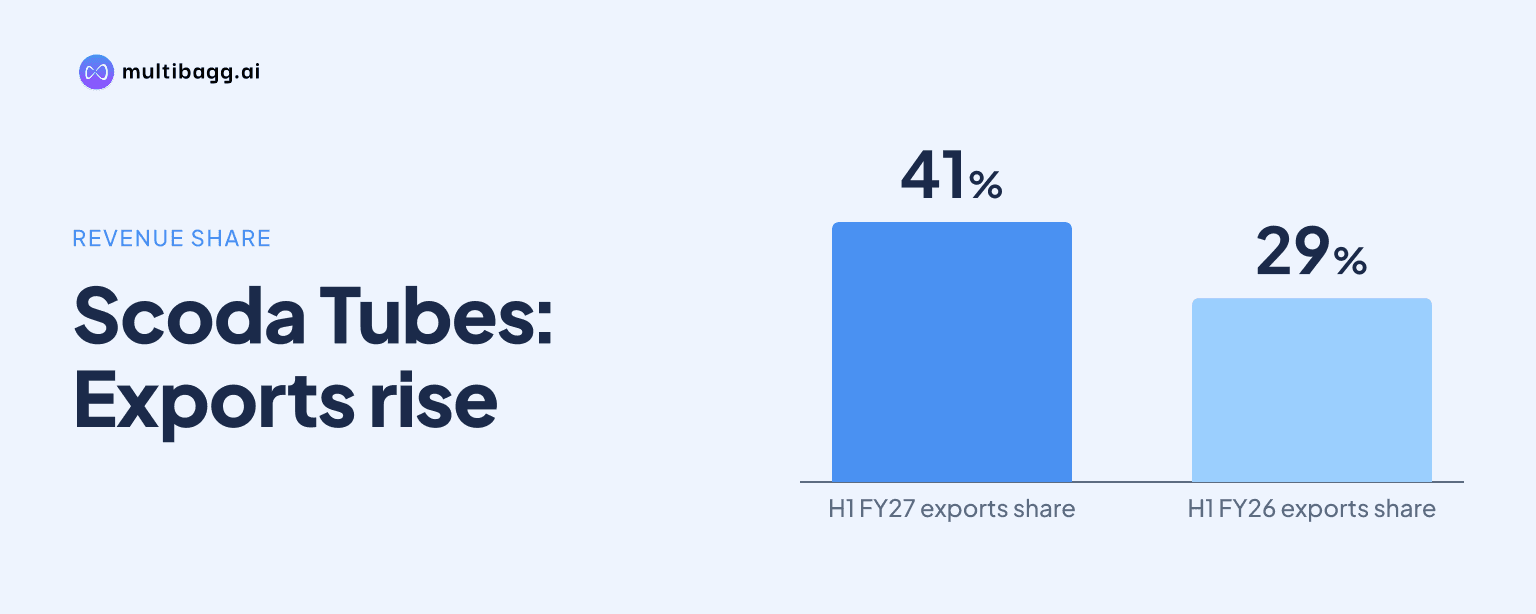
In H1 FY27, Scoda Tubes increased exports 59.4% to Rs 112.9 crore, lifting export share to 41% of Rs 273.3 crore revenue as domestic sales fell 6.6%. The Rs 42.1 crore export increase exceeded the Rs 11.4 crore domestic decline, while revenue from operations rose 12.6% year on year.
Know Scoda Tubes inside out
Results, valuation, peers and who's buying, in one view.
How did Scoda Tubes’ H1 geographic revenue change?
Scoda Tubes’ H1 FY27 revenue mix moved materially toward exports, which represented 41% of revenue versus 29% in H1 FY26. Domestic sales accounted for the remaining 59%, down from 71% a year earlier. Export revenue rose to Rs 112.9 crore from Rs 70.8 crore, while domestic revenue declined to Rs 160.4 crore from Rs 171.8 crore.
Revenue from operations increased to Rs 273.3 crore in H1 FY27 from Rs 242.7 crore in H1 FY26. The financial-highlights page describes this as 12.6% growth, while the geographic-revenue page shows 12.7%, with both pages reporting the same revenue values. The period’s disclosed geographic figures are set out below.
Scoda Tubes separately presents the H1 FY27 mix as 58.7% domestic and 41.3% exports before rounding. Its regional breakdown identifies India at 59% of revenue, Europe at 30%, the Americas at 9% and other markets at 2%. The company reports a presence in 32 countries, although it does not provide country-level export revenue values.
Did Scoda Tubes’ second quarter show the same shift?
Scoda Tubes’ Q2 FY27 results showed the same direction of geographic change, with exports rising 41.6% to Rs 55.1 crore and domestic revenue falling 11.6% to Rs 93.8 crore. Exports accounted for 37% of Q2 revenue, compared with 27% in Q2 FY26, while the domestic proportion declined to 63% from 73%.
Q2 revenue from operations rose 2.5% to Rs 148.9 crore from Rs 145.3 crore in Q2 FY26, a slower rate than the 12.6% H1 increase. Export revenue increased by Rs 16.2 crore in the quarter, from Rs 38.9 crore, whereas domestic revenue decreased by Rs 12.4 crore, from Rs 106.2 crore.
H1 FY27 export revenue of Rs 112.9 crore included Rs 55.1 crore in Q2, and domestic revenue of Rs 160.4 crore included Rs 93.8 crore in Q2. The presentation does not disclose quarterly sales by country, product category or export customer, so it does not identify the overseas markets that generated the increase.
What did higher export revenue mean for Scoda Tubes’ earnings?
Scoda Tubes reported higher H1 FY27 revenue alongside lower earnings before interest, taxes, depreciation and amortisation, or EBITDA, and profit after tax, or PAT. EBITDA fell 13.0% to Rs 31.8 crore from Rs 36.5 crore in H1 FY26, while PAT declined 52.3% to Rs 10 crore from Rs 21.1 crore.
Gross profit increased 15.9% to Rs 89.6 crore and gross profit margin rose to 32.8% from 31.8%. However, EBITDA margin declined to 11.6% from 15.1%, a reduction of 343 basis points, and PAT margin fell to 3.7% from 8.7%, a reduction of 500 basis points. One basis point equals one-hundredth of a percentage point.
In Q2 FY27, EBITDA decreased 29.3% to Rs 15.8 crore from Rs 22.3 crore, while PAT decreased 65.7% to Rs 4.8 crore from Rs 14 crore. The Chairperson and Executive Director said Q2 faced intensifying competition from private players and elevated power, fuel and freight costs. Management said it was focused on operating efficiencies, cost optimisation and competitiveness.
Cash flow from operations changed to an inflow of Rs 53.4 crore in H1 FY27 from an outflow of Rs 51 crore in H1 FY26. Debtor days were 91 at H1 FY27, compared with 97 in FY26, and the cash conversion cycle was 164 days, compared with 211 days in FY26. These measures changed even as H1 EBITDA and PAT declined.
Got a follow-up? Ask IRIS
What supports Scoda Tubes’ export reach and expansion plan?
Scoda Tubes manufactures stainless-steel seamless pipes, seamless tubes, seamless U tubes, instrumentation tubes, and welded tubes and U tubes for sectors including oil and gas, chemicals, fertilisers, power, pharmaceuticals, automotive and transportation. The presentation lists seamless production capacity of 20,068 metric tonnes per annum and welded capacity of 1,020 metric tonnes per annum.
Scoda Tubes lists certifications and approvals including PED 2014/68/EU, DNV, Indian Boiler Regulation, ISO 9001:2015, ISO 14001:2015 and ISO 45001:2018. It says these capabilities and accreditations have enabled it to serve 349 clients globally to date. An audit for Rina Marine in Italy had been completed and certification was pending, while the company had applied for Bureau Veritas Marine standards in France.
The company began exporting in 2010, according to its milestone disclosure. Management said it remains confident of achieving FY27 revenue growth of 20% to 25%, supported by its order pipeline, expanding manufacturing capabilities and execution. It also said trial production at the expanded welded facility remains on track for Q4 2027, alongside commissioning of dedicated solar capacity.
A separate capacity plan states that Scoda Tubes is increasing welded capacity by 12,000 metric tonnes per annum in 2027E. The company said its solar power capacity for seamless operations is already operational. Its Gujarat solar plant has 3.9 megawatts of alternating-current capacity and 4.99 megawatts of direct-current capacity, with annual generation of 7.74 million kilowatt-hours and estimated electricity-cost savings of about Rs 4.87 crore.
Conclusion
Scoda Tubes’ H1 FY27 revenue growth reflected a substantial geographic mix shift: exports rose Rs 42.1 crore to Rs 112.9 crore while domestic sales fell Rs 11.4 crore to Rs 160.4 crore. Exports consequently reached 41% of revenue, but the period also recorded lower EBITDA, PAT and related margins despite a 100-basis-point rise in gross profit margin.
The disclosed items to watch are management’s FY27 revenue-growth objective of 20% to 25%, trial production at the expanded welded facility in Q4 2027 and the planned 12,000-metric-tonnes-per-annum welded-capacity addition in 2027E. Future disclosures may also show whether dedicated solar commissioning and pending Rina Marine certification affect geographic sales or operating costs.