










SoftTech Q2 standalone PAT doubles as consolidated PAT falls 36%
Key highlights
- SoftTech’s Q2 FY27 standalone PAT more than doubled to Rs 3.63 crore from Rs 1.64 crore.
- SoftTech’s Q2 FY27 consolidated PAT declined to Rs 21 lakh from Rs 33 lakh.
- Standalone Q2 FY27 revenue rose 27.19% to Rs 32.70 crore, while consolidated revenue increased 17.61% to Rs 31.53 crore.
- Q2 FY27 recurring revenue grew 50.45% to Rs 14.95 crore and reached 45.7% of sales.
powered by IRIS
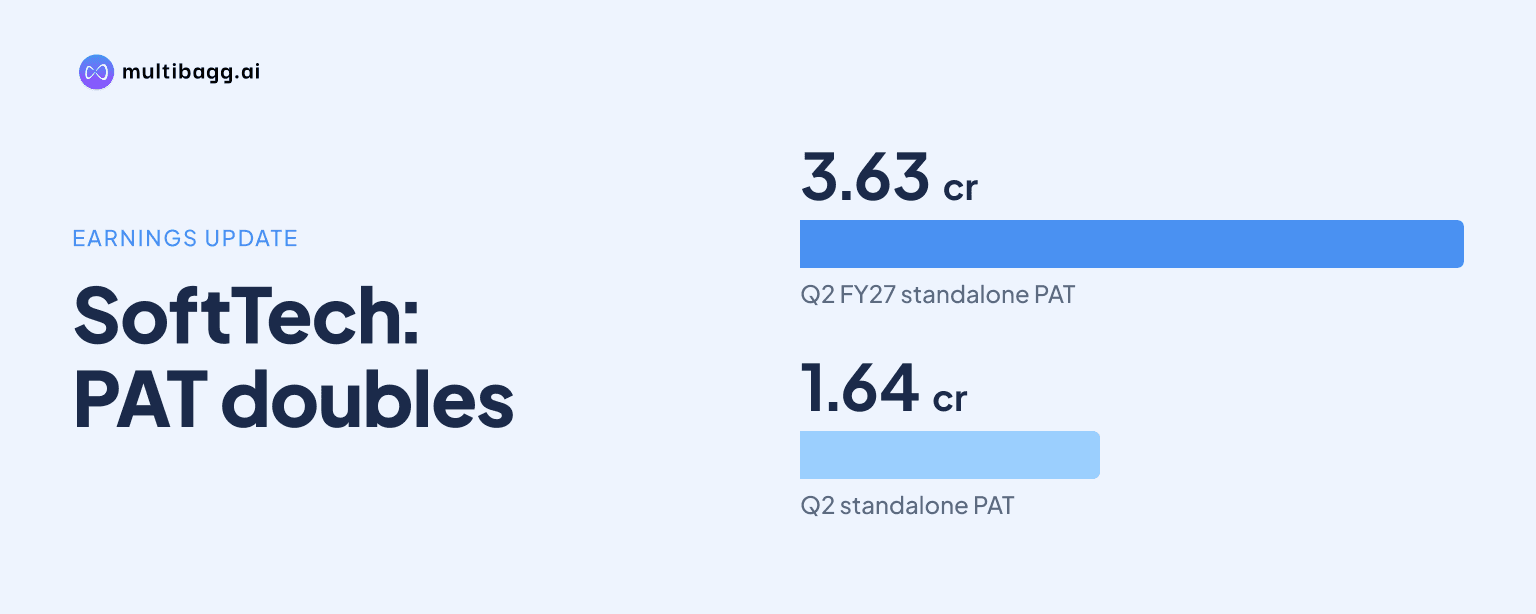
In Q2 FY27, SoftTech Engineers Limited reported standalone profit after tax (PAT) of Rs 3.63 crore, up from Rs 1.64 crore a year earlier, while consolidated PAT fell 36% to Rs 21 lakh from Rs 33 lakh. Management attributed the consolidated outcome to deferred Middle East and Africa (MEA) order execution and higher Germany go-to-market spending.
Know Softtech Engineers inside out
Results, valuation, peers and who's buying, in one view.
Why did SoftTech’s standalone and consolidated Q2 profits diverge?
SoftTech’s standalone PAT increased by Rs 1.99 crore in Q2 FY27, while consolidated PAT declined by Rs 12 lakh. Both reporting bases delivered higher revenue from operations: standalone revenue rose 27.19% to Rs 32.70 crore from Rs 25.71 crore, whereas consolidated revenue rose 17.61% to Rs 31.53 crore from Rs 26.81 crore.
The earnings gap was apparent at earnings before interest, tax, depreciation and amortisation (EBITDA). Standalone EBITDA increased to Rs 11.47 crore from Rs 7.61 crore and its EBITDA margin rose to 35.1% from 29.6%. Consolidated EBITDA rose to Rs 7.99 crore from Rs 6.98 crore, but its margin declined to 25.3% from 26.0%.
The resulting profit gap widened after depreciation, finance costs and tax. Standalone profit before tax was Rs 4.88 crore in Q2 FY27 versus Rs 2.44 crore a year earlier, while consolidated profit before tax fell to Rs 92 lakh from Rs 1.21 crore. The presentation identifies the MEA execution deferment and Germany spending as the disclosed factors affecting the consolidated result.
What drove SoftTech’s higher standalone Q2 profit?
SoftTech’s standalone profit increased as revenue growth exceeded the movement in several operating-cost lines. Revenue from operations increased by Rs 6.99 crore to Rs 32.70 crore in Q2 FY27, with management citing new verticals, including eTDR, and growth in existing businesses.
Recurring revenue was the faster-growing part of the Q2 sales mix. It increased 50.45% to Rs 14.95 crore from Rs 9.94 crore, compared with a 12.54% rise in one-time revenue to Rs 17.75 crore. Recurring revenue therefore represented 45.7% of sales, compared with 38.7% in Q2 FY25-26.
Employee cost was largely unchanged at Rs 6.34 crore, compared with Rs 6.33 crore in Q2 FY26, while cost of goods sold rose to Rs 8.04 crore from Rs 5.03 crore. Other expenses rose to Rs 6.85 crore from Rs 6.75 crore, but EBITDA still increased by Rs 3.86 crore. Finance cost declined to Rs 97 lakh from Rs 1.09 crore, which management attributed to better fund utilisation.
Why did SoftTech’s consolidated PAT fall despite revenue growth?
SoftTech’s consolidated PAT declined because incremental EBITDA did not offset higher operating expenses and charges below EBITDA. Consolidated other expenses increased to Rs 8.15 crore in Q2 FY27 from Rs 7.21 crore a year earlier, with management attributing the rise to higher go-to-market investments in Germany.
Management said a temporary deferment of an MEA order affected sales because of customer-side execution planning amid geopolitical uncertainties. Consolidated revenue nevertheless increased by Rs 4.72 crore to Rs 31.53 crore in Q2 FY27. Management said SoftTech remains engaged with the customer and expects progress when execution timelines become clearer.
Consolidated depreciation and amortisation increased to Rs 6.85 crore from Rs 5.65 crore, while other income declined to Rs 76 lakh from Rs 98 lakh. Finance cost fell to Rs 97 lakh from Rs 1.09 crore, but this did not prevent profit before tax from falling to Rs 92 lakh. Tax expense was Rs 70 lakh, leaving consolidated PAT of Rs 21 lakh and a PAT margin of 0.7%.
Got a follow-up? Ask IRIS
How did SoftTech’s first-half performance compare across reporting bases?
SoftTech’s H1 FY27 standalone earnings grew while its consolidated PAT declined slightly. Standalone revenue from operations rose to Rs 64.92 crore from Rs 51.50 crore and PAT increased to Rs 5.55 crore from Rs 3.27 crore. Consolidated revenue rose to Rs 64.82 crore from Rs 53.82 crore, while PAT declined to Rs 1.37 crore from Rs 1.44 crore.
The margin trends followed the same split in H1 FY27. Standalone EBITDA margin increased to 32.5% from 29.7% and PAT margin rose to 8.5% from 6.4%. Consolidated EBITDA margin edged down to 26.3% from 26.7%, while consolidated PAT margin declined to 2.1% from 2.7%.
Recurring revenue increased faster than total standalone revenue in the half. It rose 46.23% to Rs 28.21 crore from Rs 19.29 crore and represented 43.5% of sales, compared with 37.5% in H1 FY25-26. One-time revenue increased 13.99% to Rs 36.71 crore, contributing to total revenue growth of 26.07%.
What should readers watch in SoftTech’s next update?
SoftTech’s next update may clarify whether the deferred MEA order progresses into execution and whether Germany go-to-market costs continue to increase. Management gave neither an execution date nor an order value, but said it expects progress once customer timelines become clearer. Consolidated other expenses were Rs 21.43 crore in H1 FY27, compared with Rs 15.33 crore in H1 FY26.
SoftTech’s stated growth plan centres on CivitCity, CivitPort and CivitIndustry. The company identifies digital twins and command centres in more than 18 states for CivitCity, 13 major ports plus AAI and NHAI for CivitPort, and DMIC, CBIC and state industrial corporations for CivitIndustry. These are commercial priorities rather than reported revenue commitments.
Conclusion
SoftTech’s Q2 FY27 results show a material divergence between reporting bases: standalone PAT rose to Rs 3.63 crore as revenue and EBITDA margin increased, while consolidated PAT fell to Rs 21 lakh. The consolidated outcome reflected a deferred MEA order and higher Germany go-to-market expenses even though consolidated revenue increased to Rs 31.53 crore.
The next indicators are the customer’s MEA execution timeline and the level of Germany spending, which management identified as a source of higher costs. SoftTech’s plan also includes CivitCity opportunities in more than 18 states and CivitPort opportunities involving 13 major ports, but the presentation does not provide revenue targets or conversion dates for those priorities.