










Shelter Pharma plans Rs 12-15 crore second plant by 2028
Key highlights
- Shelter Pharma plans to invest about Rs 12-15 crore in a second Himmatnagar plant.
- The proposed plant is designed for more than Rs 100 crore of annual revenue capacity, with production targeted from mid- to end-2028.
- First-half FY27 revenue rose 35.6% year on year to Rs 45.13 crore, while PAT increased 15.4% to Rs 5.19 crore.
- Revenue in the 12 months to September 2026 was Rs 84.97 crore, or 85% of current single-shift capacity.
powered by IRIS
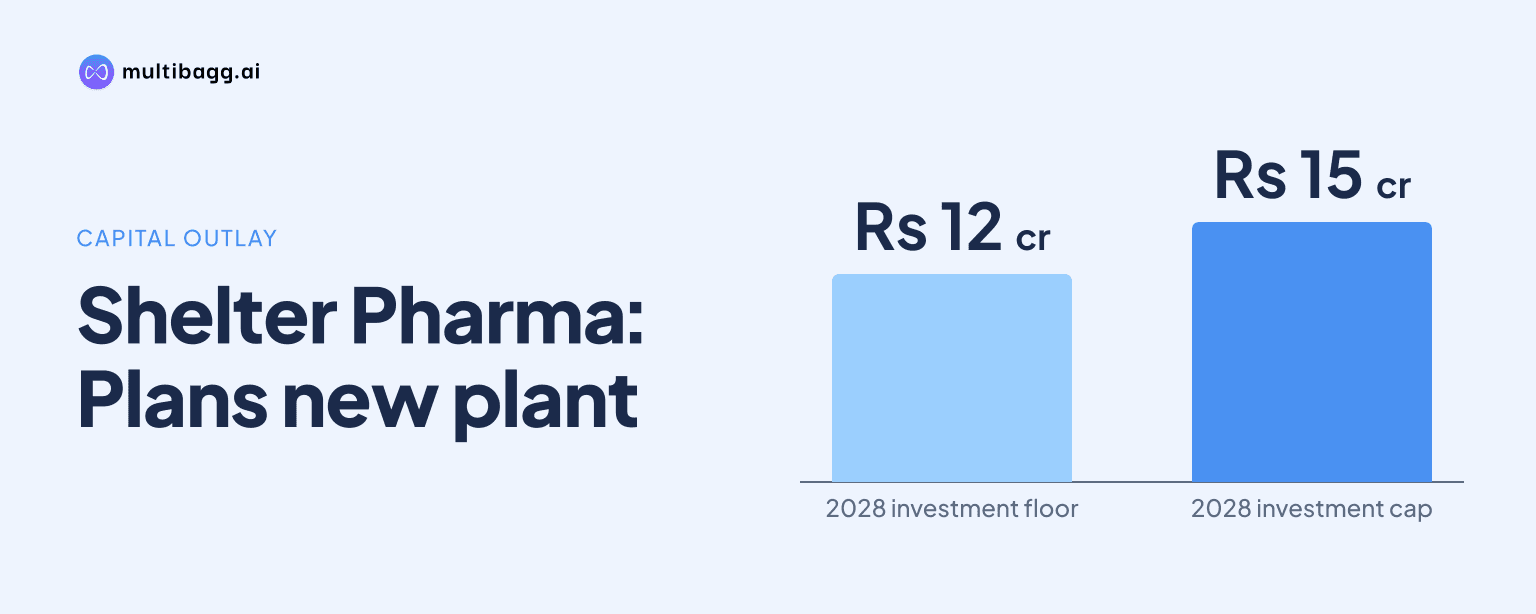
Shelter Pharma Limited plans a Rs 12-15 crore second plant, with production targeted from mid- to end-2028, to take estimated revenue capacity above Rs 200 crore after revenue in the 12 months to September 2026 reached Rs 84.97 crore, or 85% of current single-shift capacity.
Know Shelter Pharma inside out
Results, valuation, peers and who's buying, in one view.
Why is Shelter Pharma adding a second plant?
Shelter Pharma is adding a second plant because its existing Himmatnagar facility is nearing its annual single-shift revenue capacity of about Rs 100 crore at current prices. Revenue for the 12 months to September 2026 was Rs 84.97 crore, equal to 85% of that capacity, while first-half FY27 revenue of Rs 45.13 crore represented 90% of half-year single-shift capacity.
Management expects the current plant to reach full single-shift capacity by the end of FY27 if anticipated growth continues. Shelter Pharma plans to operate two shifts as an interim measure, which management says can raise output with little capital expenditure until the second plant begins production between mid- and end-2028.
The expansion is linked to Shelter Pharma's FY30 revenue target of Rs 200 crore, compared with FY26 revenue of Rs 73.13 crore. Management said the target represents a compound annual growth rate of 28.6% and expects the expanded sales team, export registrations, two-shift production and the proposed plant to support that plan.
What capacity will Shelter Pharma's second plant provide?
Shelter Pharma says the second plant is designed to support more than Rs 100 crore of annual revenue, taking total revenue capacity to more than Rs 200 crore. The company said these capacity measures are management estimates expressed in revenue terms and have not been reviewed by statutory auditors.
Shelter Pharma makes about 300 herbal and Ayurvedic formulations and nutritional products for human and animal health at Himmatnagar, Gujarat. Its product formats include tablets, capsules, powders, syrups, oils and ointments, while animal-health products include feed supplements, mineral mixtures, boluses and gels for dairy cattle and poultry.
Human health generated Rs 22.26 crore in first-half FY27 and animal health contributed Rs 22.87 crore, producing a near-even revenue split. This changed from FY26, when animal health represented 55% of revenue, as management said the human-health range grew faster during the six-month period.
Got a follow-up? Ask IRIS
How will Shelter Pharma fund and schedule the project?
Shelter Pharma estimates the proposed plant will cost about Rs 12-15 crore and plans to fund it mainly through internal accruals. The company is in the process of procuring land at Himmatnagar, making land acquisition and site approvals outstanding steps before installation can proceed.
Management expects the manufacturing licence and other approvals by December 2026. Subject to that timeline, Shelter Pharma plans to install the facility through calendar 2027 and start production from mid- to end-2028, while warning that regulatory approvals, construction and commissioning could affect the schedule.
Total borrowings were Rs 2.05 crore at 30 September 2026, compared with Rs 80 lakh at 31 March 2026, after Shelter Pharma took a Rs 1.30 crore term loan. Cash stood at Rs 1.79 crore, and management reported debt to earnings before interest, tax, depreciation and amortisation, or EBITDA, of 0.15 times and debt to equity of 0.03 times.
Shelter Pharma reported net cash used in operating activities of Rs 69.08 lakh for the six months ended 30 September 2026, after inventories increased by Rs 7.09 crore. Inventory was Rs 31.52 crore, or 127 days, versus Rs 24.44 crore, or 122 days, at 31 March 2026 as the company carried raw and packing materials into the second half.
What did Shelter Pharma report in first-half FY27?
Shelter Pharma reported revenue of Rs 45.13 crore for first-half FY27, up 35.6% year on year and 13.3% half on half, its largest six-month revenue to date. Domestic sales were Rs 39.03 crore and exports were Rs 6.11 crore, or 13.5% of revenue, exceeding the Rs 5.87 crore of exports recorded in all of FY26.
Profit after tax, or PAT, rose 15.4% year on year and 14.8% half on half to Rs 5.19 crore. EBITDA increased 17.9% year on year to Rs 7.38 crore, although its margin declined 244 basis points year on year to 16.4% as gross margin fell 237 basis points to 22.6% amid higher logistics costs associated with fuel and freight.
Employee costs rose 59.7% year on year to Rs 1.36 crore after April appointments that included a veterinary zonal sales manager, a regional sales manager for Uttarakhand and western Uttar Pradesh, three sales officers in Gujarat and Rajasthan, and an export executive. Depreciation doubled to Rs 38 lakh after the Himmatnagar building was capitalised in FY26.
Management has guided for FY27 revenue growth of 35-40%, an EBITDA margin of 16-18% and a PAT margin of 11-13%. First-half FY27 EBITDA margin was 16.4% and PAT margin was 11.5%, while management said the second half is seasonally larger.
Conclusion
Shelter Pharma's planned Rs 12-15 crore plant is intended to address the capacity constraint at its existing Himmatnagar site, where 12-month revenue of Rs 84.97 crore had reached 85% of its stated Rs 100 crore single-shift capacity. The proposed plant's more than Rs 100 crore revenue capacity, alongside two-shift production, is management's route to capacity above Rs 200 crore for the FY30 revenue target.
The next disclosed milestones are land procurement and expected manufacturing and other approvals by December 2026, followed by installation through calendar 2027. Progress against FY27 guidance of 35-40% revenue growth, the conversion of Rs 31.52 crore of inventory into sales, and production within the mid- to end-2028 window will determine whether the stated plan remains on schedule.