










Shilpa leverage falls to 1.3x as adjusted ROCE reaches 18.2%
Key highlights
- Shilpa reported net debt to EBITDA of 1.3x in 1HFY27, compared with 1.4x in FY26.
- Shilpa’s adjusted ROCE reached 18.2% in 1HFY27, up from 17.4% in FY26.
- Shilpa’s gross block rose to Rs 2,393 crore in 1HFY27 from Rs 2,281 crore in FY26.
- Shilpa reported Rs 252 crore of net capex in 1HFY27 and Rs 290 crore of EBITDA.
powered by IRIS
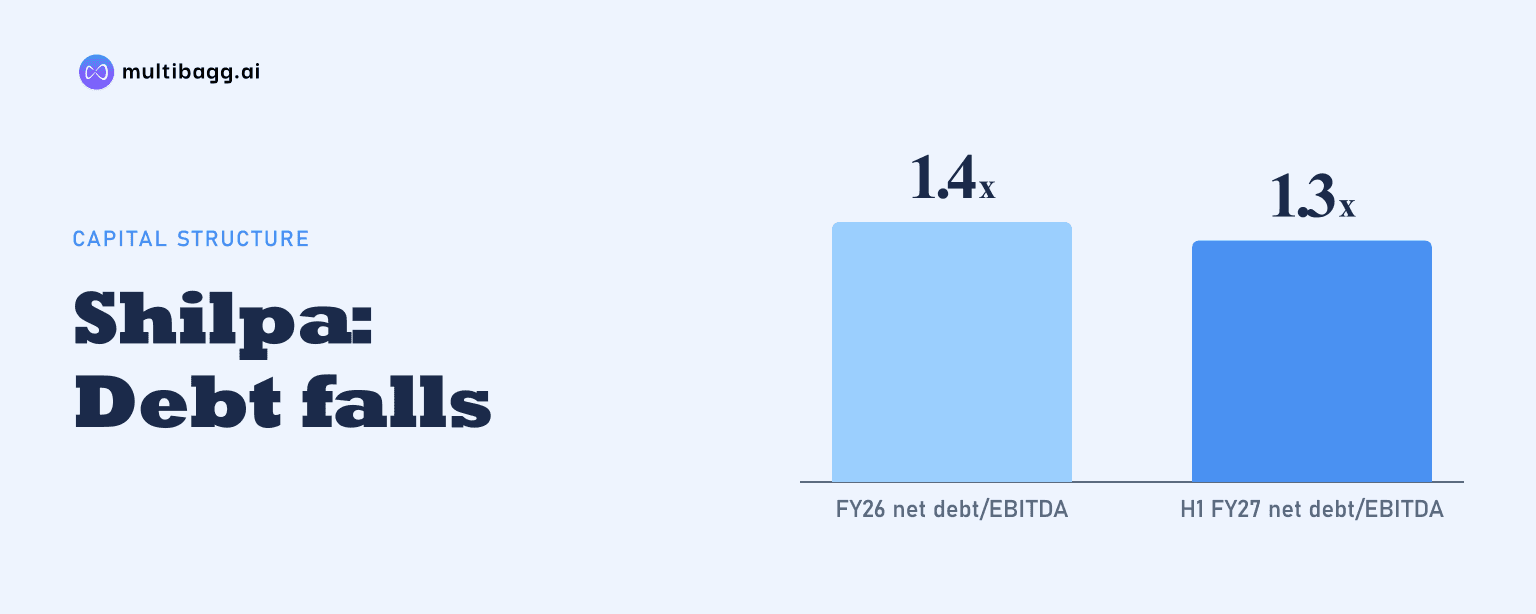
Shilpa reported net debt to EBITDA of 1.3x and adjusted return on capital employed of 18.2% in 1HFY27 on a trailing-12-month basis, compared with 1.4x and 17.4% respectively in FY26. Gross block rose to Rs 2,393 crore and net capital expenditure reached Rs 252 crore, although the presentation does not disclose operating cash flow.
Know Shilpa Medicare inside out
Results, valuation, peers and who's buying, in one view.
How did Shilpa’s leverage change in 1HFY27?
Shilpa’s net debt-to-EBITDA ratio declined to 1.3x in 1HFY27 from 1.4x in FY26. EBITDA means earnings before interest, tax, depreciation and amortisation, and the presentation states that the 1HFY27 figure is calculated on a trailing-12-month basis. The ratio had fallen from 6.7x in FY23 to 5.8x in FY24, 1.6x in FY25 and then 1.4x in FY26.
The reported leverage movement coincided with higher first-half earnings. Consolidated EBITDA increased 40% year on year to Rs 290 crore in 1HFY27 from Rs 208 crore in 1HFY26, while the EBITDA margin moved to 29% from 30%. The presentation does not provide gross debt, cash balances or net debt in rupees, so it does not show how much of the reduction to 1.3x resulted from earnings growth, debt reduction, higher cash, or a combination of these factors.
Shilpa also says its credit rating was upgraded by one category from A+ to AA-, attributing the change to a strengthening balance sheet and improving return ratios. The supplied material does not identify the rating agency or provide an upgrade date. Its stated rationale is consistent with the reported decline in net debt to EBITDA from 1.6x in FY25 to 1.3x in 1HFY27.
How much did Shilpa invest in fixed assets?
Shilpa’s gross block increased to Rs 2,393 crore in 1HFY27 from Rs 2,281 crore in FY26, a rise of Rs 112 crore. The fixed-asset base had grown from Rs 1,587 crore in FY23 to Rs 1,670 crore in FY24, Rs 1,997 crore in FY25 and Rs 2,281 crore in FY26. The presentation does not split the 1HFY27 gross block between plants, equipment, locations or operating segments.
Net capital expenditure, or net capex, was Rs 252 crore in 1HFY27. This compares with Rs 361 crore in FY26, Rs 216 crore in FY25, Rs 172 crore in FY24 and Rs 225 crore in FY23. Since Rs 252 crore covers a half-year while the previous figures cover full financial years, it should not be treated as a like-for-like annual comparison, but it confirms that asset investment continued during 1HFY27.
The disclosed API programme gives context for some continuing capacity additions. Shilpa says its new oncology block expansion remains on track for completion by the end of FY27, while peptide expansion is underway to add solid-phase synthesis capacity for glucagon-like peptide-1, high-potency active pharmaceutical ingredient and contract development and manufacturing requirements. The presentation provides no project-level capex budgets, so none of the Rs 252 crore can be allocated to a specific expansion.
Got a follow-up? Ask IRIS
Did Shilpa’s returns and earnings improve alongside asset growth?
Shilpa’s adjusted return on capital employed, or adjusted ROCE, rose to 18.2% in 1HFY27 from 17.4% in FY26 and 15.0% in FY25. The company defines adjusted ROCE as excluding investments made in potential high-growth biologics and NBE businesses. NBE refers to new biological entities, meaning the reported ratio is not a return measure on all investments in Shilpa’s overall asset base.
First-half profit grew faster than revenue and EBITDA. Total income increased 44% year on year to Rs 1,007 crore in 1HFY27 from Rs 700 crore in 1HFY26, EBITDA grew 40% to Rs 290 crore from Rs 208 crore, and profit after tax rose 98% to Rs 180 crore from Rs 91 crore. The EBITDA margin declined by 1 percentage point to 29%, whereas the profit-after-tax margin increased to 18% from 13%.
The quarterly figures show that margin pressure remained visible despite record revenue. In 2QFY27, total income was Rs 538 crore, up 45% year on year from Rs 372 crore and 15% sequentially from Rs 469 crore in 1QFY27. EBITDA reached Rs 151 crore, compared with Rs 110 crore a year earlier and Rs 139 crore in the preceding quarter, but its margin was 28%, below 30% in both comparator quarters.
Profit after tax in 2QFY27 was Rs 79 crore, 80% above Rs 44 crore in 2QFY26 but below Rs 101 crore in 1QFY27. The 1HFY27 revenue mix was led by API at Rs 470 crore, or 47% of total income, followed by formulation at Rs 407 crore, or 40%. Biologicals supplied Rs 117 crore, or 12%, while other revenue accounted for Rs 13 crore, or 1%.
Does Shilpa disclose operating cash flow of Rs 292 crore?
No, Shilpa does not disclose operating cash flow, cash flow from operations or a Rs 292 crore operating-cash-flow figure in the supplied presentation. The financial summary reports adjusted ROCE, gross block, net debt to EBITDA and net capex, while the performance pages report total income, EBITDA, operating profit before tax and profit after tax. None of these measures quantifies cash generated from operations after working-capital movements.
The distinction is relevant because 1HFY27 profit after tax of Rs 180 crore is an accounting profit measure, while Rs 252 crore of net capex records investment spending. Gross block of Rs 2,393 crore records the reported asset base. Without operating cash flow, receivables, inventory, payables or free-cash-flow figures, the supplied pages cannot establish whether the Rs 180 crore of first-half profit translated into a particular amount of operating cash generation.
Shilpa’s API division reported Rs 558 crore of 1HFY27 revenue including captive sales, compared with Rs 481 crore in 1HFY26. Reported API revenue excluding captive sales was Rs 496 crore, while specialty contract development and manufacturing revenue was Rs 62 crore, up from Rs 42 crore in 1HFY26. These revenue measures show business activity, but they do not replace a cash-flow statement.
Management’s disclosed milestones could affect the timing of future capacity use and revenue, rather than providing cash-flow guidance. Shilpa expects commercial supplies to a European specialty contract development and manufacturing customer to begin in 2HFY27. It also reports four programmes under registration with global regulators, for which approvals are expected over the next 18 to 24 months.
Conclusion
Shilpa’s reported financial summary shows lower leverage, a higher adjusted return measure and continuing investment in fixed assets. Net debt to EBITDA reached 1.3x in 1HFY27, adjusted ROCE reached 18.2%, gross block rose by Rs 112 crore from FY26 to Rs 2,393 crore, and first-half net capex was Rs 252 crore. Total income rose 44% to Rs 1,007 crore, while profit after tax rose 98% to Rs 180 crore.
The next disclosed items to watch are completion of the oncology block by the end of FY27, commencement of European customer supplies in 2HFY27 and the expected regulatory outcomes for four registration-stage programmes within 18 to 24 months. A future disclosure of operating cash flow, working-capital movements, gross debt and cash balances would be needed to assess cash conversion behind the reported earnings and leverage metrics.