










Shreenath Paper Products subsidiary holds Rs 2.67 crore pending
Key highlights
- Shreenath Paper Products' subsidiary held Rs 2.67 crore of share application money pending allotment at 30 September 2026.
- Rs 2.17 crore contributed by Shreenath Paper Products was eliminated as an intra-group balance in consolidation.
- Rs 50 lakh from the outside shareholder remained in the consolidated statement of assets and liabilities.
- Minority interest was Rs 15.23 lakh, including Rs 12.73 lakh of post-acquisition reserves.
powered by IRIS
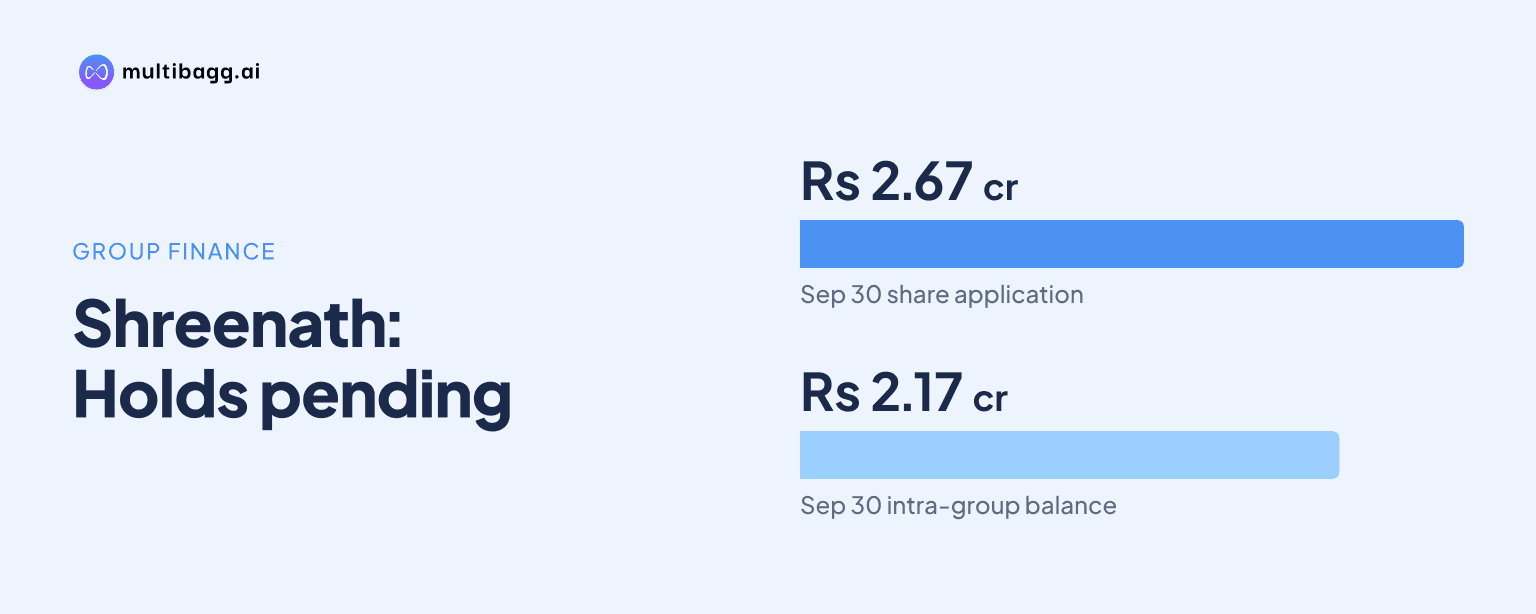
Shreenath Paper Products Limited disclosed that its subsidiary held Rs 2.67 crore of share application money pending allotment at 30 September 2026, including Rs 2.17 crore from the parent and Rs 50 lakh from its outside shareholder. After eliminating the parent’s intra-group contribution, Rs 50 lakh remained in the consolidated statement of assets and liabilities.
Know Shreenath Paper Products inside out
Results, valuation, peers and who's buying, in one view.
What makes up Shreenath Paper Products' pending share application money?
Shreenath Paper Products' subsidiary had Rs 2.67 crore of share application money pending allotment at 30 September 2026. The balance comprised Rs 2.17 crore received from Shreenath Paper Products and Rs 50 lakh received from Mr Bijoy Ramesh Shah, who held 25% of the subsidiary’s issued equity share capital at that date.
The filing describes the Rs 2.67 crore as share application money pending allotment, rather than issued share capital. It does not disclose the number of shares to be allotted, the issue price, an allotment timetable or whether the two contributions carry identical terms. Management said the treatment remains subject to its assessment of applicable allotment, refund and classification requirements.
The distinction matters because the subsidiary’s pending balance is larger than the amount visible in the group balance sheet. Shreenath Paper Products eliminated the Rs 2.17 crore it paid to the controlled subsidiary during consolidation, while the Rs 50 lakh received from Mr Shah remained in the consolidated statement of assets and liabilities at 30 September 2026.
Why does Rs 50 lakh remain in Shreenath Paper Products' consolidated results?
Rs 50 lakh remained in Shreenath Paper Products' consolidated statement of assets and liabilities because it was received from Mr Shah, an investor outside the group. The standalone balance sheet at 30 September 2026 reported no share application money, while the consolidated balance sheet reported Rs 50 lakh under share application money.
The filing expressly says that the Rs 50 lakh has not been included in minority interest merely because it came from the minority shareholder. This separates the pending contribution from the subsidiary’s 25% non-controlling ownership interest until allotment, refund or another classification is determined under management’s assessment.
Minority interest was Rs 15.23 lakh at 30 September 2026, comprising Rs 2.50 lakh attributable to the subsidiary’s issued share capital and Rs 12.73 lakh attributable to post-acquisition reserves. The Rs 50 lakh pending contribution was therefore separate from, and greater than, the reported minority-interest balance.
The consolidated statement of assets and liabilities recorded share capital of Rs 19.65 crore, reserves and surplus of Rs 26.69 crore, share application money of Rs 50 lakh and minority interest of Rs 15.23 lakh at 30 September 2026. At 31 March 2026, the consolidated comparative showed no share application money and no minority interest because it corresponded to the holding company alone.
How does first-time consolidation affect Shreenath Paper Products' comparisons?
Shreenath Paper Products presented consolidated financial results for the first time for the half-year ended 30 September 2026, making its earlier consolidated-labelled comparative figures not directly comparable. The filing says the 31 March 2026 and earlier comparative amounts represent the holding company alone because Shreenath Paper Industries Private Limited was not included in the group at those dates.
At 30 September 2026, Shreenath Paper Products held 75% of the subsidiary’s issued equity share capital and Mr Shah held the remaining 25%. The consolidated results include the subsidiary’s assets, liabilities, income, expenses and cash flows from the date control was obtained, after elimination of intra-group transactions and balances.
The filing also states that the date on which control was first obtained must be confirmed before final issue. That unresolved date is relevant because it determines the point from which the subsidiary’s results are included in the half-year consolidated figures under AS 21, the Accounting Standard for Consolidated Financial Statements.
For the half-year ended 30 September 2026, consolidated revenue from operations was Rs 78.36 crore, compared with standalone revenue of Rs 68.54 crore. Consolidated profit after tax was Rs 1.18 crore versus standalone profit after tax of Rs 66.81 lakh; Rs 12.73 lakh of the consolidated profit was attributed to minority interest, leaving Rs 1.05 crore attributable to equity shareholders of Shreenath Paper Products.
Got a follow-up? Ask IRIS
Which intra-group balances did Shreenath Paper Products eliminate?
Shreenath Paper Products eliminated Rs 2.17 crore of intra-group share application money when preparing the consolidated results for the half-year ended 30 September 2026. It also eliminated the holding company’s investment in the subsidiary against the relevant share of the subsidiary’s equity, preventing both sides of that intra-group position from appearing at group level.
The group eliminated Rs 36.36 lakh of intra-group sales and corresponding purchases, excluding goods and services tax. It also eliminated Rs 9.46 lakh of intra-group trade receivables and payables, including goods and services tax, at 30 September 2026.
No inventory acquired through the Rs 36.36 lakh of intra-group sales remained unsold at the reporting date. As a result, Shreenath Paper Products reported no unrealised profit in closing inventory from those transactions, which removes the need for a separate inventory-profit adjustment in the consolidated result.
The consolidated cash-flow statement separately recorded Rs 50 lakh of share application money received and Rs 5 lakh from issue of shares in financing activities for the half-year ended 30 September 2026. It also recorded Rs 2.50 lakh as purchase of shares from a minority shareholder in investing activities, without explaining that transaction’s relationship to the reported 75%-25% ownership at the reporting date.
What does Shreenath Paper Products say the subsidiary will do?
Shreenath Paper Products says the subsidiary was established to manufacture sublimation paper, a category of goods previously procured and traded by the holding company. The company describes the manufacturing activity as backward integration intended to support internal sourcing and operational integration.
The filing does not provide separate revenue, profit, assets or cash-flow figures for the manufacturing operation in the half-year ended 30 September 2026. It says trading and manufacturing have been considered for segment reporting under AS 17, Segment Reporting, with separate reportable information to be presented if required.
The consolidated cash-flow statement includes the subsidiary’s cash and cash equivalents in full from the date control was obtained, rather than reducing cash for the 25% minority ownership. The filing states that the consolidated cash-flow statement must be fully reconciled and approved before filing, identifying reconciliation as an outstanding matter as of 12 November 2026.
Conclusion
Shreenath Paper Products' Rs 2.67 crore pending share-application balance shows that the subsidiary’s funding was not fully converted into issued share capital at 30 September 2026. Consolidation removed the Rs 2.17 crore parent contribution, but retained the Rs 50 lakh received from the outside shareholder separately from the Rs 15.23 lakh minority interest.
The next disclosures to watch are management’s decision on allotment, refund or classification of the Rs 50 lakh, confirmation of the date control was obtained, and reconciliation and approval of the consolidated cash-flow statement. The subsidiary’s planned sublimation-paper manufacturing activity is also the disclosed operating development that could affect future group reporting.