










Shriram Properties makes FY27 H2 depend on 2,200 handovers
Key highlights
- Shriram Properties plans 5.25 million square feet of FY27 launches in H2.
- The identified handover pipeline covers 2,295 units and Rs 1,155 crore of indicated development potential.
- H1 FY27 revenue was Rs 543 crore and EBITDA was Rs 104 crore.
- Net debt was Rs 761 crore on September 30, 2026, while cash was Rs 357 crore.
powered by IRIS
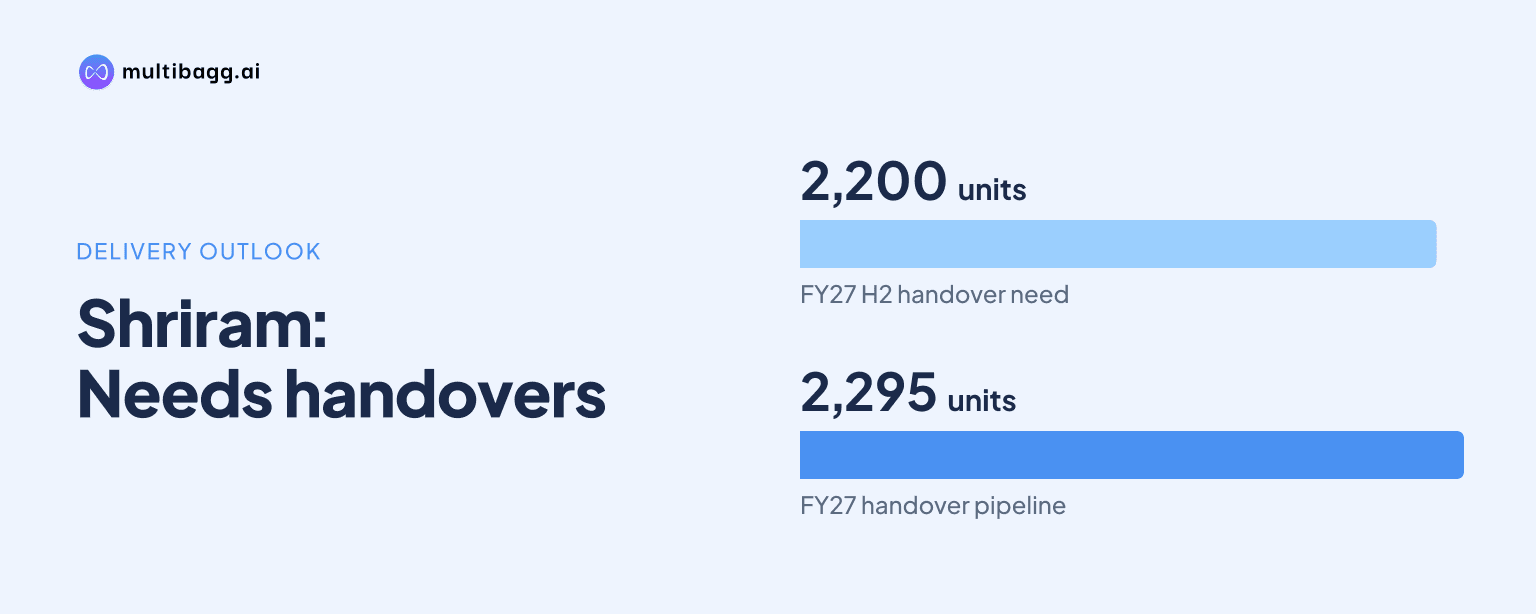
Shriram Properties expects FY27’s second half to determine its delivery of planned growth, with 5.25 million square feet of launches and 2,295 pending handovers linked to Rs 1,155 crore of indicated development potential. Management said on November 13, 2026 that completion, occupancy certificates and customer handovers remain conditions for this revenue recognition.
Know Shriram Properties inside out
Results, valuation, peers and who's buying, in one view.
Why is Shriram Properties’ FY27 second half decisive?
Shriram Properties’ FY27 second half is decisive because launches, project completions and revenue recognition are concentrated after the first half. The company handed over 1,450 units in H1 FY27, including more than 760 units in Q2, and said its remaining project pipeline provided visibility for more than 2,200 additional handovers before year-end.
Management said FY27 performance depends on timely approvals, new launches, occupancy certificates and customer handovers. Several projects were approaching certificate and handover stages, which are the mechanisms through which completed homes contribute to recognised revenue and cash generation. Management therefore expects revenue recognition to be substantially stronger in H2 if planned completions materialise.
The first-half operating base was improving, but it does not remove the delivery requirement. Sales rose about 20% sequentially to Rs 583 crore in Q2 FY27, while H1 sales were Rs 1,067 crore across 1.76 million square feet. Collections reached Rs 431 crore in Q2 and Rs 795 crore in H1, up 10% year on year, supporting construction activity needed for the H2 handover schedule.
What launches does Shriram Properties plan for FY27?
Shriram Properties plans approximately 5.93 million square feet of launches in FY27, with 5.25 million square feet scheduled for H2. The planned calendar covers projects in Bengaluru, Chennai and Pune, including Bannerghatta Road, Yelahanka, Doddagubbi and Sarjapura in Bengaluru, as well as Manjari, Hinjewadi and Chennai’s Gateway C-Zone.
The schedule has already encountered one approval-related shift. The Pune Manjari project, originally planned for Q2, was deferred to Q3 because approvals were pending; management told analysts that the 2.3 million-square-foot project had received all but one clearance and could launch between November and December. Management said launches across the portfolio were expected from November through March.
Management also said it was not relying only on newly launched projects for FY27 sales. Sustenance inventory and new phases of existing developments are expected to contribute, alongside new supply. In recent launches, management reported that 50% of Chennai inventory and 75% of Kolkata inventory had been sold, while it targeted release of at least 5 million square feet during the year from projects with 7.2 million square feet of saleable area.
Which projects drive Shriram Properties’ handover potential?
Shriram Properties identified 2,295 pending handovers across projects with 3.39 million square feet of sold area and Rs 1,155 crore of indicated development potential. This project-level disclosure is marginally higher than management’s broader H2 description of more than 2,200 handovers and revenue potential exceeding Rs 1,100 crore, but both measures show that a defined group of projects underpins the second-half outlook.
The named projects are 107 South East and Esquire in Bengaluru, and Sunshine One, Sunshine Two, Grand One and Southbrook in Kolkata. Management highlighted 107 South East, with about 796 pending handovers, and Sunshine Two, with about 776 pending handovers. These two projects alone account for about 1,572 units, subject to completion and approval milestones.
Kolkata’s execution has particular bearing on the revenue mix because it contributed approximately 50% of H1 FY27 revenue. Management said it was closely monitoring occupancy certificates and construction schedules across the identified projects. The objective, it said, is to convert completion into handovers, revenue recognition and cash generation rather than simply finish construction work.
Got a follow-up? Ask IRIS
What financial position supports Shriram Properties’ H2 plan?
Shriram Properties reported H1 FY27 revenue of Rs 543 crore, up 11% year on year, EBITDA of Rs 104 crore, up 73%, and profit after tax of Rs 32.6 crore, up 12%. EBITDA means earnings before interest, tax, depreciation and amortisation. The quarterly improvement reflected revenue from completed projects and handovers, with Park 63 and Shankari in Chennai and Grand One and Sunshine in Kolkata among the main Q2 contributors.
Q2 FY27 revenue grew 19% year on year while total expenses remained flat, according to management, lifting EBITDA margin to approximately 23%. Finance cost rose by Rs 9.6 crore year on year to Rs 31.6 crore, reflecting consolidation of acquired joint-venture projects. The company said the acquired interests would allow it to recognise full project revenue and corresponding profit, rather than only its share of joint-venture profit.
Cash generation increased in H1 FY27, although management noted financing inflows also raised the cash balance. Operating inflows of Rs 505 crore and outflows of Rs 404 crore produced Rs 101 crore of operating cash flow, versus Rs 76 crore a year earlier. After Rs 105 crore of new-project investment, net free cash flow was Rs 184 crore, compared with negative Rs 34 crore in H1 of the prior year.
Gross external debt rose to Rs 1,118 crore on September 30, 2026 from Rs 651 crore at June-end, while net debt increased to Rs 761 crore from Rs 432 crore. Management attributed much of the increase to debt consolidated through joint-venture acquisitions. Cash was Rs 357 crore at September-end and undrawn borrowing limits were Rs 245 crore; management said it would seek to refinance higher-cost borrowings where feasible and align incremental debt with project-level cash flows.
Conclusion
Shriram Properties has a larger execution programme in FY27 H2 than in H1: 5.25 million square feet of planned launches, 2,295 identified pending handovers and Rs 1,155 crore of indicated development potential. The H1 results, including Rs 543 crore of revenue, Rs 104 crore of EBITDA and Rs 184 crore of net free cash flow after new-project investment, provide the reported operating base, but do not substitute for the scheduled completions.
The next measures to watch are regulatory clearance for Manjari, the November-to-March launch sequence, and occupancy certificates and handovers at 107 South East and Sunshine Two. Management also reaffirmed its FY28 target of Rs 2,500 crore of revenue and 10% profit before tax, citing Rs 4,600 crore of unbooked revenue potential from ongoing projects; delivery of the FY27 H2 programme is the nearer-term test of that plan.