










Shriram Properties Q2 EBITDA triples as expenses stay flat
Key highlights
- Q2 FY27 revenue increased 19% year on year to Rs 272 crore.
- Q2 FY27 EBITDA rose to Rs 62.4 crore from Rs 18.6 crore while total expenses remained flat.
- Q2 FY27 profit after tax increased 151% year on year to Rs 21.6 crore.
- Shriram Properties expects more than 2,200 H2 FY27 handovers with revenue potential exceeding Rs 1,100 crore.
powered by IRIS
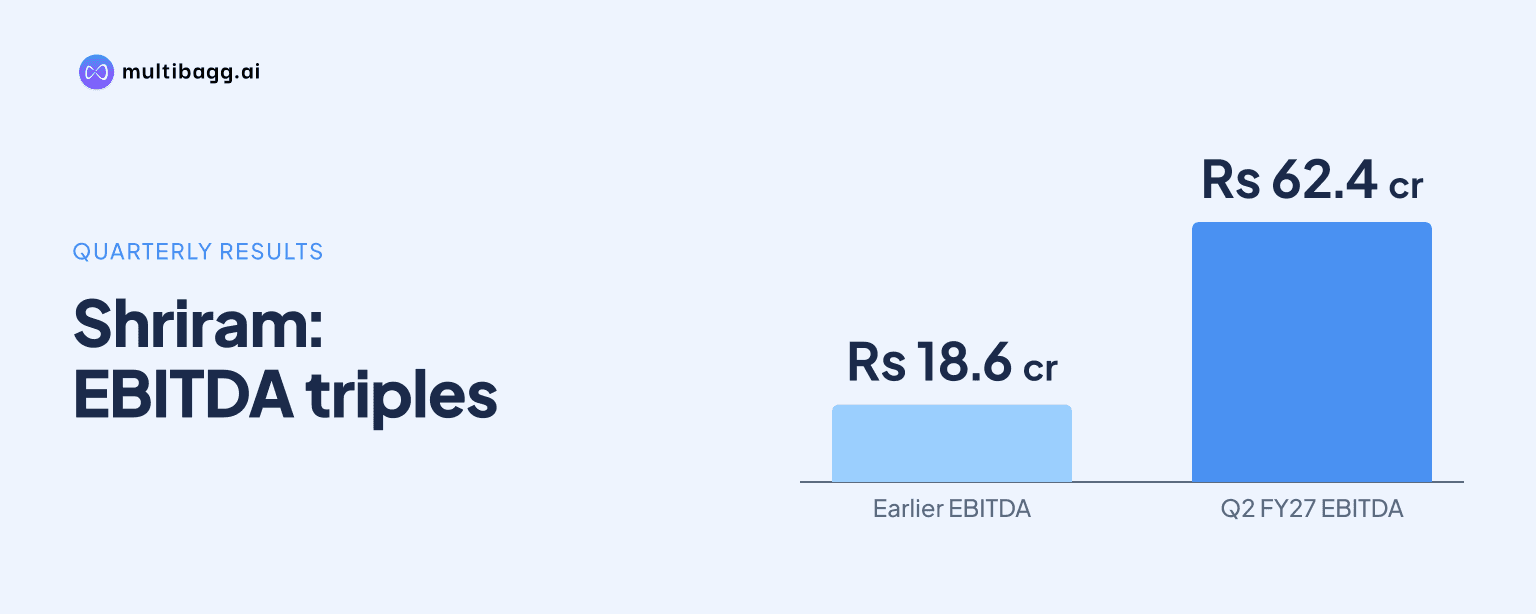
Shriram Properties Limited more than tripled EBITDA in Q2 FY27 to Rs 62.4 crore from Rs 18.6 crore a year earlier, as revenue increased 19% to Rs 272 crore while total expenses remained flat. Shriram Properties said favourable product mix, completed-project handovers and disciplined cost management drove the increase.
Know Shriram Properties inside out
Results, valuation, peers and who's buying, in one view.
Why did Shriram Properties’ Q2 EBITDA more than triple?
Shriram Properties’ Q2 FY27 EBITDA more than tripled because Rs 43 crore of additional revenue was recognised while total expenses were unchanged from Q2 FY26. EBITDA rose by Rs 43.8 crore to Rs 62.4 crore in the quarter ended September 30, 2026, from Rs 18.6 crore a year earlier. EBITDA margin reached about 23%, according to management.
Management attributed the change to favourable product mix, cost discipline and income recognition from completed projects rather than revenue growth alone. Q2 revenue was supported by handovers from projects completed in FY26 and recently completed projects, including Park 63 and Shankari in Chennai and Grand One and Sunshine in Kolkata.
The operating result also improved sequentially alongside sales activity. Q2 sales were Rs 583 crore, about 20% above Q1, while collections rose 18% sequentially to Rs 431 crore. For H1 FY27, sales totalled Rs 1,067 crore and collections were Rs 795 crore, up 10% year on year.
How did Shriram Properties’ Q2 FY27 profit compare with last year?
Shriram Properties moved to a Q2 FY27 profit before tax of Rs 29.6 crore from a Rs 1.1 crore loss in Q2 FY26, as EBITDA rose faster than finance costs. Profit after tax increased 151% to Rs 21.6 crore from Rs 8.6 crore, although finance cost increased to Rs 31.6 crore from Rs 22 crore.
For H1 FY27, revenue increased 11% to Rs 543 crore and EBITDA rose 73% to Rs 104 crore. Profit before tax more than doubled to Rs 44 crore, while profit after tax increased 12% to Rs 32.6 crore. Management said cost of sales, employee-benefit expenses and other expenses remained largely stable during the first half.
The increase in finance cost reflected a change in the reporting perimeter rather than the Q2 operating result alone. Shriram Properties said the consolidation of acquired joint-venture projects increased finance cost, while future income and expenses from those projects will be included directly in its consolidated statements.
Which projects and regions supported Shriram Properties’ revenue?
Shriram Properties’ Q2 revenue was led by handovers in Chennai and Kolkata, with Kolkata contributing about 50% of H1 FY27 revenue. The company handed over more than 760 units in Q2 and 1,450 units in H1, with Park 63, Shankari, Grand One and Sunshine identified as the main Q2 revenue contributors.
The company converted five joint ventures and three key projects into wholly owned subsidiaries, including 107 South East, WYT Field and 122 West. Management estimated that the restructuring creates about Rs 1,800 crore of additional revenue-recognition potential in consolidated reporting over the relevant project-completion periods. That amount is not presented as a single-quarter revenue addition.
Recent launches also supported Q2 sales momentum. Shriram Properties said 50% of recent Chennai inventory and 75% of Kolkata inventory had sold, while a plotted and villa development in Kolkata sold more than 75% of inventory within 90 days. The company has about 105 acres of land in Kolkata following a settlement and is evaluating development-led opportunities there.
Got a follow-up? Ask IRIS
What could determine Shriram Properties’ second-half FY27 results?
Shriram Properties’ H2 FY27 results depend on completing projects, obtaining occupancy certificates and converting completed homes into handovers. Management expects more than 2,200 additional handovers in H2 after 1,450 in H1, with revenue potential exceeding Rs 1,100 crore from that handover pipeline.
The identified H2 pipeline comprises about 3.39 million square feet of sold area, 2,295 pending handovers and indicated development potential of about Rs 1,155 crore. Key projects include 107 South East and Esquire in Bengaluru, and Sunshine One, Sunshine Two, Grand One and Southbrook in Kolkata. 107 South East had about 796 pending handovers and Sunshine Two had about 776, subject to planned completion and approvals.
New launches are also weighted to the second half. Shriram Properties’ FY27 launch calendar covers about 5.93 million square feet, of which 5.25 million square feet is planned for H2, subject to approvals and launch readiness. The Manjari project in Pune was deferred from Q2 to Q3 because approvals were pending, while Gateway C-Zone in Chennai was targeted for Q4.
How have Shriram Properties’ cash flow and debt changed?
Shriram Properties generated Rs 101 crore of operating cash flow in H1 FY27, compared with Rs 76 crore in the prior-year period, while reported debt increased after joint-venture consolidation. Operating inflows were Rs 505 crore and operating outflows were Rs 404 crore during H1, producing the Rs 101 crore positive operating cash flow.
After financial cash flows and Rs 105 crore invested in new projects, net free cash flow was positive at Rs 184 crore, compared with negative Rs 34 crore in H1 FY26. Cash increased to Rs 357 crore on September 30, 2026, from Rs 172 crore at the start of FY27. Management said financing inflows also contributed to the higher cash balance.
Gross external debt increased to Rs 1,118 crore at September 30 from Rs 651 crore at the end of June, while net debt increased to Rs 761 crore from Rs 432 crore. Net debt to equity rose to about 0.51 from 0.29. Management attributed much of the increase to debt consolidated with the acquired joint-venture projects and said it had Rs 245 crore of undrawn borrowing limits.
Conclusion
Shriram Properties’ Q2 FY27 profit improvement was driven mainly by operating leverage: revenue rose 19%, total expenses stayed flat and EBITDA increased to Rs 62.4 crore. The company also shifted from a Rs 1.1 crore pre-tax loss in Q2 FY26 to Rs 29.6 crore of pre-tax profit, despite finance cost rising by Rs 9.6 crore following joint-venture consolidation.
The next measure of execution is management’s H2 plan for more than 2,200 handovers and revenue potential above Rs 1,100 crore. Investors will need to watch occupancy certificates, the delayed Manjari approvals, delivery of the planned 5.25 million square feet of H2 launches, collections and the stated plan to ease the higher debt level over the next 12 to 18 months.