










Simplex Castings Maintains Rs 300-Crore FY27 Revenue Target
Key highlights
- Simplex Castings reported H1 FY27 revenue of Rs 123.96 crore, up 23.21% year on year.
- Management maintained FY27 revenue guidance of Rs 300 crore-plus despite incomplete expansion work.
- Simplex Castings reported a pending order book of roughly Rs 150 crore and a pipeline exceeding Rs 100 crore.
- Capital work in progress rose to Rs 36.77 crore at September 30, 2026, from Rs 12.38 crore previously.
powered by IRIS
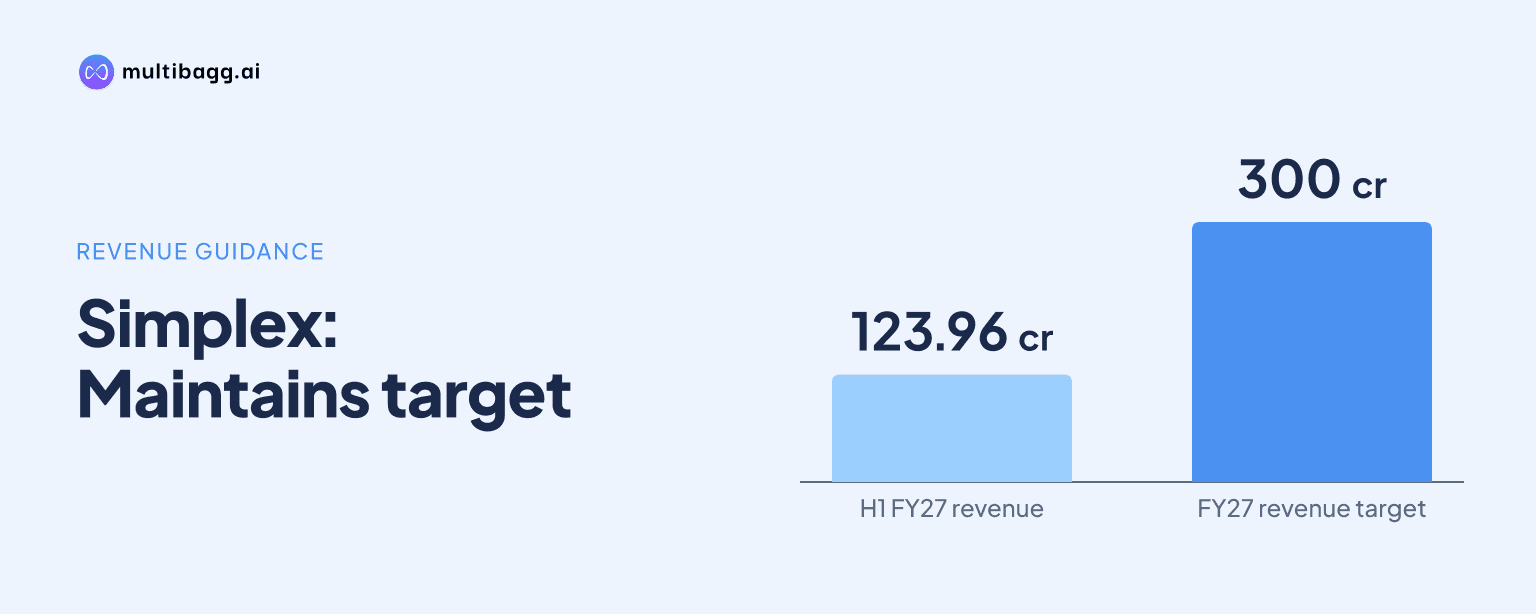
Simplex Castings Limited maintained its Rs 300-crore-plus FY27 revenue target on November 16, 2026, despite only part of its expansion being expected by March, citing Rs 123.96 crore of H1 revenue, a Rs 150-crore order book, more than Rs 100 crore of pipeline and bill-discounting arrangements for working capital.
Know Simplex Castings inside out
Results, valuation, peers and who's buying, in one view.
Can Simplex Castings meet its Rs 300-crore FY27 revenue target?
Yes, Simplex Castings said it remains on track to achieve around Rs 300 crore or more of revenue in FY27. Revenue from operations was Rs 123.96 crore in H1 FY27, up 23.21% year on year, leaving Rs 176.04 crore to be delivered in the second half to reach Rs 300 crore for the full year.
Management attributed the required second-half acceleration to the company’s normal dispatch pattern. It said customers typically deploy project budgets and increase dispatches in H2, while October and the first half of November were progressing better than H1. Management also said customers were seeking faster supplies of castings and fabricated items after their own projects took time to be finalised.
An analyst referred to a Rs 330-crore number in the company presentation, but management repeatedly described its FY27 guidance as Rs 300 crore-plus. A Rs 330-crore outcome would require Rs 206.04 crore in H2, compared with Rs 176.04 crore needed for the stated Rs 300-crore threshold.
Will incomplete capacity additions affect Simplex Castings in FY27?
No, management said the partly unfinished expansion would not affect Simplex Castings’ FY27 guidance. It estimated that the overall capital-expenditure programme would require another five to six months, with some facilities commissioned by March and about 50% of the remaining work continuing roughly three months after the financial year.
The investment is not a single project, management said. It includes additional sheds and fabrication-shop capacity, and some sheds are expected to contribute during FY27 before the full programme is complete. Capital work in progress was Rs 36.77 crore at September 30, 2026, compared with Rs 12.38 crore previously.
Management said existing capacity and the part commissioning planned by March should support the current-year target. The completed capacity base is intended to support the next financial year’s Rs 500-crore target, particularly through fabrication and railway work. It expects utilisation of existing capacity to reach between 80% and 90% in the next financial year.
What order visibility supports Simplex Castings’ FY27 plan?
Simplex Castings cited a pending order book of roughly Rs 150 crore and a further pipeline of more than Rs 100 crore as the main support for its Rs 300-crore-plus FY27 target. Management said a major part of the Rs 150-crore order book should be executed in the current financial year, without providing a customer-wise or product-wise split.
Steel, power and railways are the company’s three priority sectors, although management highlighted coke-oven doors and power equipment as current opportunities. It said Simplex Castings had secured casting orders for all four or five coke-oven batteries currently being built in India. Management described each future coke-oven battery as an opportunity worth Rs 25 crore to Rs 30 crore of coke-oven doors.
For the next year, management identified four planned coke-oven batteries at Bokaro, Bhilai and two IISCO sites, which it said could represent around Rs 120 crore of coke-oven-door opportunity. It is also targeting more than Rs 150 crore of turnover from fabrication of heavy structures for power-plant equipment. These figures are management objectives and opportunities, not booked revenue.
Got a follow-up? Ask IRIS
How is Simplex Castings funding growth and managing margins?
Simplex Castings said bill-discounting arrangements with Larsen & Toubro and Bharat Heavy Electricals Limited would help bridge its working-capital requirement until preferential-allotment proceeds are received. The arrangements apply to thermal-power projects and allow bills raised on those customers to be discounted before ordinary collection cycles end.
Management said it had approval to raise close to Rs 100 crore from Indian funds. It said the additional funds would support working capital rather than increase the originally planned capital expenditure. As the company seeks to scale from Rs 300 crore towards Rs 500 crore, management expects work-in-process inventory to rise and estimated that two-and-a-half to three months of such inventory could reach about Rs 80 crore.
H1 FY27 profit growth exceeded revenue growth. Earnings before interest, tax, depreciation and amortisation, or EBITDA, rose 29.05% to Rs 24.26 crore, against revenue growth of 23.21%, while EBITDA margin increased by about 89 basis points to 19.58%. Profit after tax rose 40.55% to Rs 14.5 crore and profit-after-tax margin increased by 145 basis points to 11.7%.
Management said long-term orders containing price-variation clauses help reduce the effect of raw-material inflation. It expects H2 margins to be broadly similar to H1 levels. However, it described the Q2 FY27 profit-after-tax margin of 12.13% as above its normal experience and said it aims to maintain profit-after-tax margin in an 8% to 10% range, versus a historical maximum of 7% to 8% in earlier strong years.
What could change Simplex Castings’ outlook?
The key variables are the pace of H2 dispatches, the commissioning of remaining capacity and working-capital availability. Management said it did not expect customer delays because buyers were seeking castings and fabricated products for their own projects, but the company must still convert its Rs 150-crore order book and Rs 100-crore-plus pipeline into FY27 revenue.
Railways remain a longer-term growth lever rather than a confirmed FY27 contributor. Management said the large wagon order expected between July and September had been delayed to the next quarter. The proposed order concerns about 1 lakh wagons over two-and-a-half to three years, and Simplex Castings expects demand for its bogies after wagon builders receive their allocations.
Management said the current capital programme is sufficient for its railway plans, including fabricated locomotive and metro bogies that it had not previously produced. It also said railways are intended to become 30% to 40% of standard output over time, while defence and shipbuilding are expected to remain a smaller activity of about 10% to 15%.
Conclusion
Simplex Castings’ Rs 300-crore-plus FY27 guidance depends on a substantially higher H2 than the Rs 123.96 crore reported in H1, rather than on complete commissioning of its expansion. Management’s stated support for the target is the Rs 150-crore order book, the Rs 100-crore-plus pipeline, seasonally higher dispatches and interim financing through bill discounting.
The next developments to watch are the planned March commissioning of part of the fabrication facilities, the receipt of preferential-allotment proceeds and the release of the delayed railway wagon order in the next quarter. Management has also set a Rs 500-crore target for the next financial year and says the current capacity programme is sufficient to support that plan.