










SIS Limited says most Labour Code repricing benefit is ahead
Key highlights
- SIS reported record Q2 FY27 revenue of Rs 4,816.0 crore, up 28.1% year on year.
- Q2 FY27 profit after tax rose 37.1% year on year to Rs 110.7 crore.
- Security Solutions India revenue increased 38.9% year on year to Rs 2,144.1 crore.
- SIS said most Labour Code repricing benefit remains ahead without disclosing a rupee value or timeline.
powered by IRIS
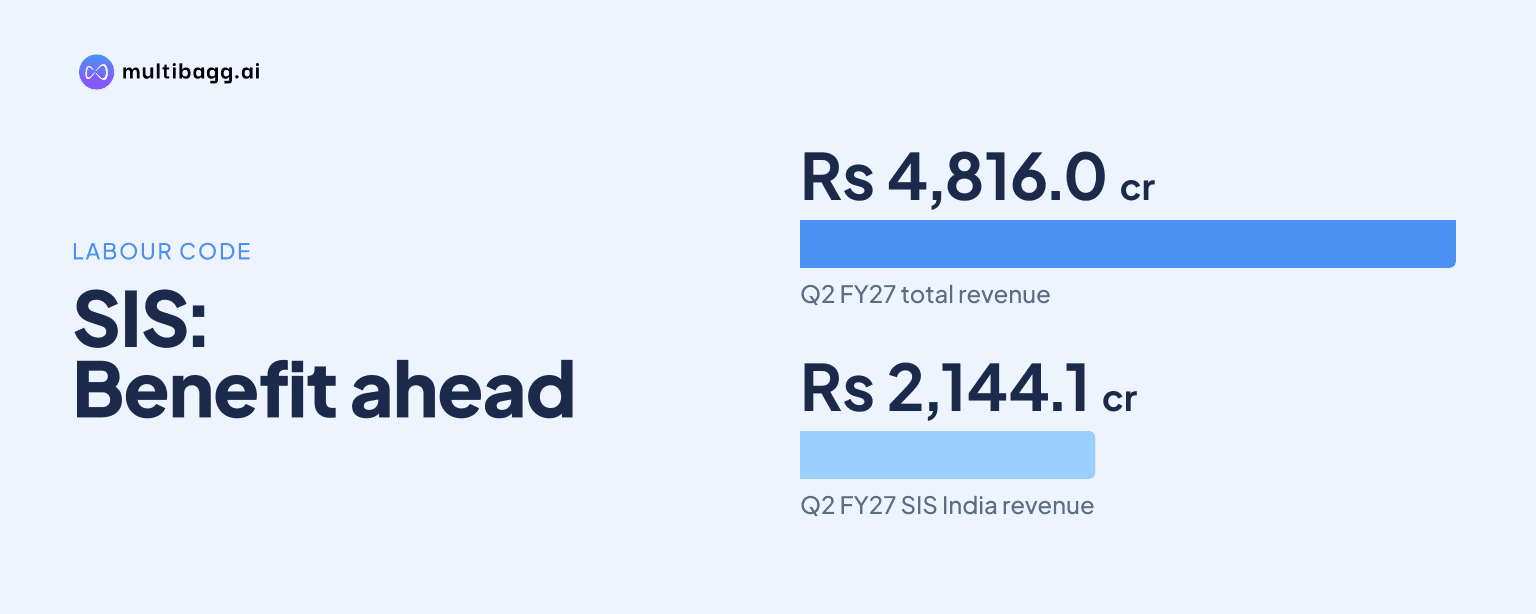
SIS Limited reported its highest-ever quarterly profit after tax of Rs 110.7 crore in Q2 FY27, up 37.1% year on year, while management said on November 4, 2026, that the major chunk of Labour Code repricing benefit was still ahead. Quarterly revenue reached Rs 4,816.0 crore and earnings before interest, tax, depreciation and amortisation rose 32.7%.
Know SIS inside out
Results, valuation, peers and who's buying, in one view.
What did SIS report in Q2 FY27?
SIS reported record quarterly revenue and profit after tax for the quarter ended September 30, 2026, alongside EBITDA of Rs 223.3 crore. Revenue from operations rose 28.1% year on year to Rs 4,816.0 crore from Rs 3,758.5 crore in Q2 FY26, and increased 4.6% sequentially from Rs 4,603.6 crore in Q1 FY27. EBITDA grew 32.7% year on year from Rs 168.3 crore.
SIS recorded faster growth in EBITDA and profit after tax than in revenue during Q2 FY27. EBITDA increased 7.8% from Rs 207.1 crore in Q1 FY27, while profit after tax increased 8.9% from Rs 101.7 crore. The EBITDA margin rose by 0.1 percentage point both year on year and sequentially to 4.6%, and the profit after tax margin rose to 2.3% from 2.1% in Q2 FY26.
How did SIS operating segments perform in Q2 FY27?
SIS Security Solutions India was the largest reported segment by quarterly revenue, generating Rs 2,144.1 crore in Q2 FY27, up 38.9% year on year. Revenue was Rs 1,543 crore in Q2 FY26 and Rs 2,004 crore in Q1 FY27. SIS attributed major wins during the quarter to Ecommerce, Metals and Mining, and information technology and IT-enabled services sectors.
SIS Security Solutions India reported its highest-ever quarterly EBITDA of Rs 112.3 crore, with margin increasing to 5.3% from 5.1% in Q1 FY27. Security Solutions International generated Rs 2,019.6 crore of revenue, up 25.7% year on year and 6.3% in constant currency, while segment EBITDA rose 34.5% year on year to Rs 71.9 crore. SIS said new wins in Energy and Hospitality drove international growth.
SIS Facility Management Solutions was the smallest of the three reported segments by revenue but had the highest segment EBITDA margin, at 5.7% in Q2 FY27. Its revenue grew 7.6% year on year to Rs 677.3 crore, while its highest-ever quarterly EBITDA rose 17.8% to Rs 38.3 crore. Major wins came from Healthcare, Material, Steel and Consumers sectors, and margin increased from 5.5% in Q1 FY27.
Got a follow-up? Ask IRIS
What did SIS say about Labour Code repricing?
SIS said the major chunk of Labour Code repricing benefit remains ahead, without identifying a quantified benefit in Q2 FY27. Group Managing Director Rituraj Kishore Sinha made the statement while discussing revenue of Rs 4,816 crore, EBITDA growth of 33% and profit after tax of about Rs 111 crore in the November 4, 2026 release.
Management had called FY27 an “inflection year” in Q1 and said Q2 established that trend through 28% year-on-year revenue growth. The release does not disclose the value of the expected repricing benefit, the period in which it could be realised, or the amount already reflected in Q2 FY27 EBITDA of Rs 223.3 crore. The size and timing of the stated remaining benefit therefore remain unresolved.
SIS also included a safe-harbour statement covering future status, events, plans and objectives. It said forward-looking statements are based on estimates and anticipated effects of future events, are subject to risks and uncertainties, and may differ materially from actual results. Management’s repricing comment is an outlook statement alongside the reported Q2 FY27 EBITDA margin of 4.6%.
What do SIS cash flow and balance-sheet measures show?
SIS reported a net debt-to-EBITDA ratio of 1.24 times as of September 2026, compared with 1.05 times as of June 2026. The 0.19-times sequential increase occurred as consolidated EBITDA reached Rs 223.3 crore in Q2 FY27. The release does not provide an absolute net debt amount or identify the drivers of the change.
Operating cash flow divided by EBITDA was negative 44.4% on a consolidated basis during the quarter, while group days sales outstanding, or DSO, stood at 69 days. These measures were reported alongside 32.7% year-on-year EBITDA growth. SIS also reported return on capital employed of 16.5% and return on equity of 16.0% in Q2 FY27.
Conclusion
SIS paired record Q2 FY27 revenue of Rs 4,816.0 crore and profit after tax of Rs 110.7 crore with growth across all three reported operating segments. Security Solutions India delivered the fastest revenue growth, at 38.9%, while Facility Management Solutions recorded the highest segment EBITDA margin, at 5.7%; consolidated EBITDA margin was 4.6%, up 0.1 percentage point from both comparison periods.
The next issue to watch is the scale and timing of the Labour Code repricing benefit that management says is still ahead under its FY27 inflection-year view. SIS has not disclosed a monetary target or realisation schedule, while net debt-to-EBITDA was 1.24 times in September 2026 and quarterly operating cash flow to EBITDA was negative 44.4%; subsequent disclosures can show how those measures develop.