










SKP H1 revenue rose 7.7% as consolidated loss reached Rs 57 lakh
Key highlights
- SKP consolidated H1FY27 revenue rose 7.7% to Rs 43.04 crore.
- SKP reported a Rs 57 lakh consolidated loss in H1FY27 against a Rs 3.35 crore profit a year earlier.
- SKP standalone H1FY27 revenue increased 9.4% to Rs 31.38 crore, while profit after tax was Rs 5.94 crore.
- SKP reported 79% roller utilisation and 23% ball utilisation in Q2FY27.
powered by IRIS
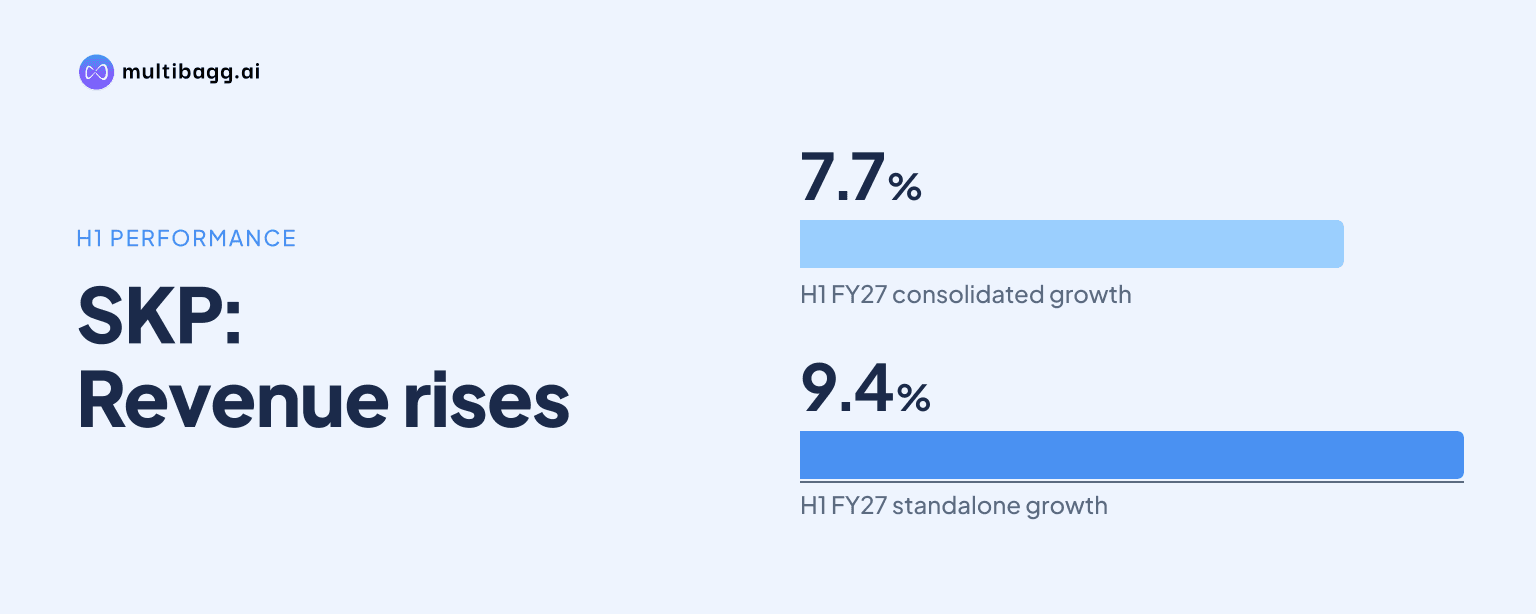
SKP Bearing Industries Limited reported H1FY27 consolidated revenue of Rs 43.04 crore, up 7.7% year on year, but recorded a Rs 57 lakh loss after tax against a Rs 3.35 crore profit in H1FY26. Earnings before interest, tax, depreciation and amortisation (EBITDA) fell 32.4% to Rs 4.83 crore and the EBITDA margin declined to 11.23% from 17.86%.
Know SKP Bearing Industries inside out
Results, valuation, peers and who's buying, in one view.
Why did SKP report a loss despite H1 revenue growth?
SKP reported a loss because its operating profit and other income declined while tax exceeded profit before tax in H1FY27. Revenue rose by Rs 3.08 crore to Rs 43.04 crore, but EBITDA fell by Rs 2.31 crore to Rs 4.83 crore. Profit before tax was Rs 1.85 crore and tax was Rs 2.42 crore, producing a Rs 57 lakh loss after tax.
The change was also evident quarter by quarter. SKP recorded a Rs 61 lakh loss in Q2FY27, compared with a Rs 4 lakh profit in Q1FY27 and a Rs 2.98 crore profit in Q2FY26. Consolidated expenditure increased to Rs 38.21 crore in H1FY27 from Rs 32.82 crore in H1FY26, exceeding the Rs 3.08 crore rise in revenue.
Other income declined to Rs 1.50 crore in H1FY27 from Rs 2.65 crore a year earlier, while interest increased to Rs 2.04 crore from Rs 1.57 crore. Depreciation was broadly unchanged at Rs 2.44 crore, compared with Rs 2.42 crore in H1FY26. These reported movements explain part of the earnings decline, although the presentation does not provide a detailed cost bridge.
How did SKP’s standalone business compare with the group result?
SKP’s standalone Indian business remained profitable in H1FY27, though both its EBITDA and profit margins were below the prior-year level. Standalone revenue grew 9.4% to Rs 31.38 crore from Rs 28.69 crore, while EBITDA increased 2.1% to Rs 10.77 crore from Rs 10.54 crore. Profit after tax declined to Rs 5.94 crore from Rs 7.10 crore.
The standalone EBITDA margin was 34.31% in H1FY27, down from 36.75% in H1FY26, while the consolidated EBITDA margin was 11.23%, down from 17.86%. Standalone profit after tax margin was 18.92%, compared with a consolidated loss margin of 1.32%. The difference shows that the profitable standalone result did not translate into a positive group result.
In Q2FY27, standalone revenue was Rs 15.64 crore, marginally below Rs 15.74 crore in Q1FY27 but above Rs 15.04 crore in Q2FY26. Q2 EBITDA was Rs 5.39 crore, nearly unchanged from Rs 5.37 crore in Q1FY27 but below Rs 6.15 crore in Q2FY26. SKP said Q2 other income increased from Q1 primarily because of foreign-exchange gains.
Did SKP quantify France’s effect on the consolidated loss?
SKP did not quantify France-specific costs or provide a separate French profit-and-loss statement for the Rs 57 lakh H1FY27 consolidated loss. The presentation describes France as being in an integration and path-to-profitability phase, with cost-optimisation initiatives nearing completion. It does not allocate the group’s Rs 38.21 crore H1FY27 expenditure by geography, operation or subsidiary.
The available disclosure links the France operation to a revenue-recovery and operational-stabilisation plan, rather than establishing a precise France cost contribution to the loss. France revenue rose from €0.23 million in FY24 to €2.02 million in FY25 and €2.42 million in FY26. Management said legacy customers were gradually returning after the ownership transition and that further customer discussions were progressing through supplier evaluation and qualification.
SKP said the France operation has about 400 machines or assets, providing capacity to scale volumes without major fresh capacity expansion. Management’s plan includes India-based sourcing of materials and services, machinery redeployment and cross-selling across global original equipment manufacturer (OEM) customers. These are stated initiatives and capacity observations, not reported profitability outcomes.
Got a follow-up? Ask IRIS
What is SKP’s plan for its France operation?
SKP management is targeting a gradual France revenue recovery towards a pre-acquisition annual revenue base of €8 million to €8.5 million, followed by a longer-term ambition of €16 million. The FY26 France revenue figure of €2.42 million was below both stated reference points. Management has not disclosed a timetable for attaining the €8 million to €8.5 million range or the €16 million ambition.
Management also disclosed a newly secured customer relationship with projected revenue potential of about Rs 100 crore by FY30. It said the relationship enables dual sourcing across the customer’s global facilities and was previously unattainable from India over a decade. The presentation does not disclose an annual revenue schedule, contracted volumes, order value or expected margin from this customer.
The French plan therefore depends on customer reactivation, new customer qualifications, operating efficiencies and volume growth using the existing asset base. France revenue increased by €0.40 million from FY25 to FY26, following a €1.79 million increase from FY24 to FY25. The presentation does not give H1FY27 France revenue, leaving the current pace of recovery undisclosed.
What was the progress in SKP’s Indian manufacturing operations?
SKP’s roller operation was operating at 79% utilisation in Q2FY27, while the newer ball operation was at 23% utilisation. Annualised installed capacity was 1,872 tonnes per annum (TPA) for rollers and 2,000 TPA for balls. SKP said roller expansion was complete and that operating and utilisation ramp-up were under way.
Ball production increased 32% to 117.1 in Q2FY27 from 88.7 in Q1FY27, according to the presentation. Commercial approvals have been secured and initial ball dispatches are under way. SKP is targeting eligibility for International Automotive Task Force (IATF) 16949 certification after March 2026, while stating that the ball operation is International Organization for Standardization certified.
SKP also said production had commenced for defence and aerospace applications and that it was under approval with a leading Indian aircraft and aerospace manufacturer for critical components. Commercial vehicles accounted for 20% of H1FY27 industrial revenue, followed by two-wheelers at 17%, automotive and bearing industries at 14% each, and aftermarket at 11%. SKP reported that return on capital employed for its core Indian manufacturing business was about 40% or more in FY26.
Conclusion
SKP’s H1FY27 results show that 7.7% consolidated revenue growth to Rs 43.04 crore did not offset the decline in operating profitability. EBITDA fell to Rs 4.83 crore, the consolidated margin declined by 6.63 percentage points to 11.23%, and the group moved from a Rs 3.35 crore profit to a Rs 57 lakh loss. The standalone Indian operation remained profitable, but its margin also declined year on year.
The next disclosed indicators are progress towards France’s €8 million to €8.5 million pre-acquisition revenue base, management’s longer-term €16 million ambition, and the projected Rs 100 crore customer opportunity by FY30. In India, roller utilisation of 79%, ball utilisation of 23%, and the post-March 2026 IATF 16949 eligibility target provide measurable points for assessing the manufacturing ramp-up.