










Stellant Securities promoter holding rises to 45.38% after allotment
Key highlights
- Stellant Securities promoters acquired 166,200 fully convertible warrants on November 4, 2026.
- The warrants were issued at Rs 602 per underlying equity share, including a Rs 592 premium.
- The promoter group’s reported aggregate holding rose to 45.38% from 42.77%.
- Stellant Securities reported diluted share or voting capital of Rs 66.80583 lakh assuming full warrant conversion.
powered by IRIS
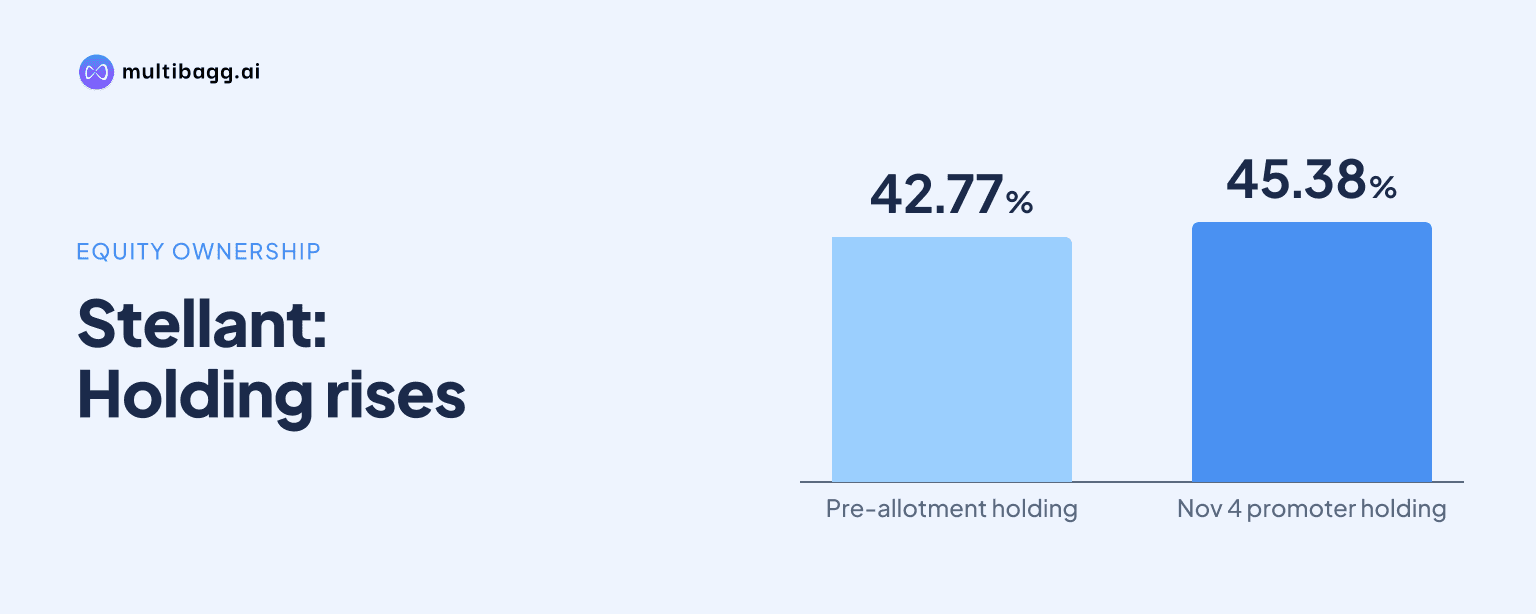
Stellant Securities (India) Limited’s promoter group received 166,200 fully convertible warrants through a preferential allotment on November 4, 2026, raising its reported aggregate holding to 45.38% from 42.77% of total share or voting capital. The warrants were issued for cash at Rs 602 per underlying equity share.
Know Stellant Securities (India) inside out
Results, valuation, peers and who's buying, in one view.
What did Stellant Securities promoters acquire?
Stellant Securities’ four disclosed acquirers received 166,200 fully convertible warrants in the preferential allotment dated November 4, 2026. The instruments entitle holders to receive equity shares carrying voting rights on conversion, rather than representing an immediate acquisition of equity shares carrying voting rights.
The allotment increased the promoter group’s reported aggregate holding, including shares and convertible instruments, by 2.61 percentage points of total share or voting capital. On the filing’s fully diluted measure, the acquired warrants represented 2.48%, while the group’s aggregate holding rose to 43.23% from 40.75%.
The preferential issue price was Rs 602 per underlying equity share, including a premium of Rs 592 over the Rs 10 face value. The filing describes the warrants as fully convertible and issued for cash, but does not state a conversion deadline or exercise timetable.
Which Stellant Securities promoters received the warrants?
Stellant Securities disclosed that Mangala Subhash Rathod received 33,224 warrants, while Saajan Subhash Rathod and Mayank Subhash Rathod each received 66,488 warrants. Subhash Phootarmal Rathod, who already held 150,000 warrants before the transaction, was listed among the acquirers and persons acting in concert but did not receive any of the newly disclosed 166,200 warrants.
Mangala Subhash Rathod and Subhash Phootarmal Rathod were the two group members disclosed as holding equity shares carrying voting rights before and after the allotment. Their respective shareholdings remained 1,192,855 and 1,379,855 shares, or 18.74% and 21.68% of total share or voting capital, because the reported transaction involved warrants rather than an immediate equity-share allotment.
How did the allotment change Stellant Securities promoter ownership?
Stellant Securities reported promoter-group holdings of 2,722,100 shares and convertible instruments before the acquisition, rising to 2,888,300 after it. The reported total therefore increased by 166,200 instruments, the same number of warrants allotted through the preferential issue.
The filing separately lists 150,000 pre-existing warrants held by Subhash Phootarmal Rathod and the 166,200 newly acquired warrants. It also shows that the equity shares held by Mangala Subhash Rathod and Subhash Phootarmal Rathod did not change on November 4, 2026.
On the fully diluted basis stated in the filing, the promoter group’s 43.23% holding is lower than its 45.38% total-capital figure. The difference follows the filing’s use of a larger diluted share or voting-capital base assuming warrant conversion, rather than a different number of promoter-group instruments.
Got a follow-up? Ask IRIS
What are the conversion terms and capital figures?
Stellant Securities described the securities as fully convertible warrants issued for cash at Rs 602 per equity share, with a Rs 10 face value and a Rs 592 premium per share. The disclosure does not specify a conversion deadline, exercise schedule or other conversion condition beyond describing the warrants as fully convertible.
The company reported equity share capital and total voting capital of Rs 63.64383 lakh before the acquisition and the same Rs 63.64383 lakh after it. This indicates that the November 4, 2026 event did not immediately alter reported equity share capital, consistent with the allotment of warrants rather than equity shares.
Stellant Securities reported total diluted share or voting capital of Rs 66.80583 lakh after the acquisition, assuming warrants are fully convertible. The filing identifies BSE Limited as the company’s listed exchange and identifies all four acquirers as belonging to the promoter or promoter group.
When was the Stellant Securities allotment disclosed?
Stellant Securities recorded November 4, 2026 as the date of acquisition or receipt of allotment intimation. The disclosure under Regulation 29(1) of the Securities and Exchange Board of India’s Substantial Acquisition of Shares and Takeovers Regulations, 2011, was dated November 6, 2026 and stated Mumbai as the place of signing.
The filing names Mangala Subhash Rathod, Saajan Subhash Rathod, Mayank Subhash Rathod and Subhash Phootarmal Rathod as the acquirers and persons acting in concert. Their status matters because the 45.38% post-acquisition figure is an aggregate group measure, not the holding of one individual promoter.
The filing does not disclose any sale of shares, encumbrance or voting rights otherwise than by shares in connection with the 166,200-warrant transaction. Its stated acquisition mode is preferential allotment, rather than an open-market purchase or an inter-se transfer.
Conclusion
Stellant Securities’ November 2026 preferential allotment added 166,200 fully convertible warrants to the promoter group’s reported position at Rs 602 per underlying share. The disclosed aggregate holding increased from 42.77% to 45.38% on the total share or voting-capital measure, while the fully diluted measure moved from 40.75% to 43.23%.
The next point to watch is whether and when the warrants convert into equity shares, because the filing’s Rs 66.80583 lakh diluted share or voting-capital figure assumes full conversion. The disclosure provides no conversion deadline or exercise timetable, so any later conversion, equity-capital change or further promoter transaction would require a subsequent company disclosure.