










Stellant Securities receives Rs 2.50131 crore from promoter warrants
Key highlights
- Stellant Securities allotted 166,200 promoter warrants at Rs 602 each.
- The promoter warrants carry total consideration of Rs 10.00524 crore.
- Stellant Securities received Rs 2.50131 crore, or 25%, on allotment.
- Mayank Rathod and Saajan Rathod each received 66,488 warrants.
powered by IRIS
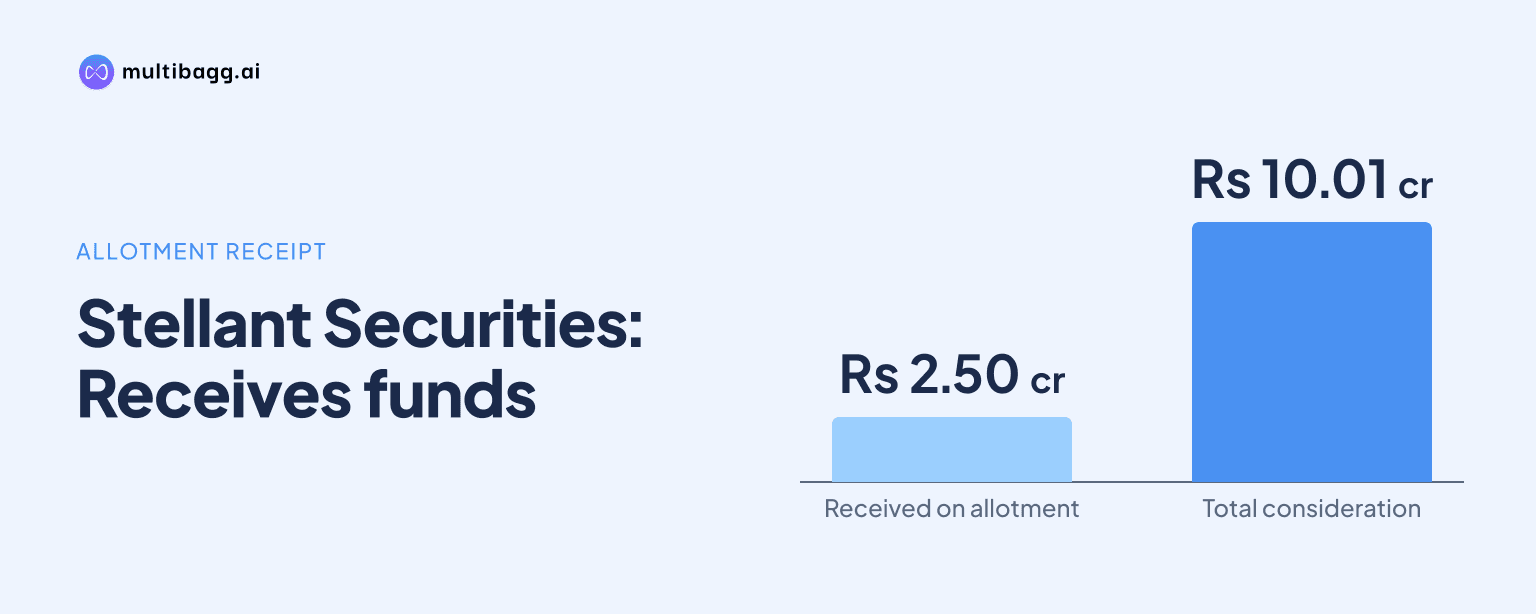
Stellant Securities (India) Limited received Rs 2.50131 crore on allotment of 166,200 warrants convertible into equity to three promoter allottees at Rs 602 each. The upfront amount represents 25% of the Rs 10.00524 crore total consideration, while each warrant carries a Rs 10 face value and Rs 592 premium.
Know Stellant Securities (India) inside out
Results, valuation, peers and who's buying, in one view.
What did Stellant Securities allot at Rs 602 a warrant?
Stellant Securities allotted 166,200 warrants convertible into equity at an issue price of Rs 602 each to members of its promoter group. The disclosed price comprises Rs 10 equity face value and Rs 592 premium, meaning the premium accounts for Rs 592 of every Rs 602 warrant issue price. The company presented the transaction in Annexure II as an allotment of warrants for cash consideration to the promoter and promoter group.
The 166,200 warrants represent potential equity issuance through their stated conversion feature, rather than an immediate allotment of equity shares in this annexure. At the Rs 602 issue price, the full value attached to the warrants is Rs 10.00524 crore. The filing does not state a conversion date, conversion deadline, post-conversion shareholding percentage or the number of outstanding shares after conversion.
The transaction is reported under Schedule III of Part A of the Securities and Exchange Board of India, or SEBI, Listing Obligations and Disclosure Requirements Regulations, 2015. The annexure also cites SEBI Circular No. SEBI/HO/CFD/CFD-PoD1/P/CIR/2023/123 dated July 13, 2023. It identifies all three recipients as promoters in both their current and proposed status categories.
Who received the 166,200 Stellant Securities warrants?
Stellant Securities allotted 66,488 warrants each to Mayank Rathod and Saajan Rathod, while Mangla Subhash Rathod received 33,224 warrants. The two larger allotments are exactly twice the 33,224-warrant allotment. Together, Mayank Rathod and Saajan Rathod account for 132,976 warrants, or 80% of the disclosed 166,200-warrant promoter allotment.
Each of the two 66,488-warrant allocations carries total consideration of Rs 4.0025776 crore, compared with Rs 2.0000848 crore for the 33,224 warrants allotted to Mangla Subhash Rathod. The stated consideration follows the same Rs 602 price across all three allocations. No different warrant prices, discounts or special terms for any of the three allottees are disclosed in Annexure II.
Got a follow-up? Ask IRIS
How much did Stellant Securities receive upfront from promoters?
Stellant Securities received Rs 2.50131 crore on allotment, which its filing identifies as 25% of the Rs 10.00524 crore total consideration for the 166,200 warrants. The remaining 75% of the total consideration, calculated from the disclosed figures, is Rs 7.50393 crore. The filing labels only the initial 25% as consideration paid on allotment.
Mayank Rathod and Saajan Rathod each paid Rs 1.0006444 crore at allotment, while Mangla Subhash Rathod paid Rs 0.5000212 crore. Those payments align with 25% of their respective Rs 4.0025776 crore and Rs 2.0000848 crore full consideration amounts. The company does not disclose in the annexure when or under what additional conditions the balance consideration would be paid.
The difference between cash received at allotment and the full stated consideration matters because the warrants are described as convertible into equity. The filing confirms the initial payment percentage and the total proposed consideration, but does not specify how many warrants, if any, may ultimately convert. It also does not disclose the resulting change in promoter ownership or equity capital if all 166,200 warrants convert.
How does the promoter warrant issue compare with the non-promoter equity allotment?
Stellant Securities' 166,200 promoter warrants have a lower disclosed count and consideration than the 678,388 equity shares allotted to non-promoter or public recipients in Annexure I. The equity-share allotment was also priced at Rs 602 per share, but its total stated consideration was Rs 40.8389576 crore, compared with Rs 10.00524 crore for the promoter warrants. The non-promoter equity-share count was 512,188 higher than the warrant count.
The mechanism differs between the annexures. Annexure I calls the 678,388 instruments equity shares issued and allotted for cash consideration, whereas Annexure II describes 166,200 warrants convertible into equity and records only 25% consideration as paid on allotment. Both annexures state a Rs 602 issue price, made up of Rs 10 face value and Rs 592 premium.
The largest recipient in the non-promoter equity-share annexure was Lloyds Enterprises Limited, with 166,112 shares for Rs 9.9999424 crore. That share count is only 88 below the 166,200 promoter warrants in Annexure II, although the instruments have different stated forms. The filing does not provide a combined post-allotment capital figure that would allow the two annexures to be translated into ownership percentages.
Conclusion
The disclosed transaction gives Stellant Securities a promoter-group warrant allotment of 166,200 instruments at Rs 602 each, with Rs 2.50131 crore received initially against full stated consideration of Rs 10.00524 crore. Mayank Rathod and Saajan Rathod received 66,488 warrants each, while Mangla Subhash Rathod received 33,224, and all three remain classified as promoters in the filing.
The next item to watch is whether Stellant Securities discloses payment of the remaining Rs 7.50393 crore and conversion of any or all of the 166,200 warrants into equity. The annexure does not state the conversion timing, final share count, or resulting promoter holding, so those matters remain unresolved in the supplied disclosure.