










Style Baazar Q2 EBITDA drops 55% as net loss hits Rs 32.1 crore
Key highlights
- Style Baazar reported a Rs 32.1 crore consolidated PAT loss in Q2 FY27, versus a Rs 51.5 crore profit in Q2 FY26.
- Q2 FY27 EBITDA fell 54.8% year on year to Rs 31.2 crore and EBITDA margin fell to 6.5% from 13.0%.
- Q2 FY27 revenue from operations declined 10.0% year on year to Rs 478.5 crore.
- Style Baazar ended 30 September 2026 with 283 stores, up 33 stores year on year.
powered by IRIS
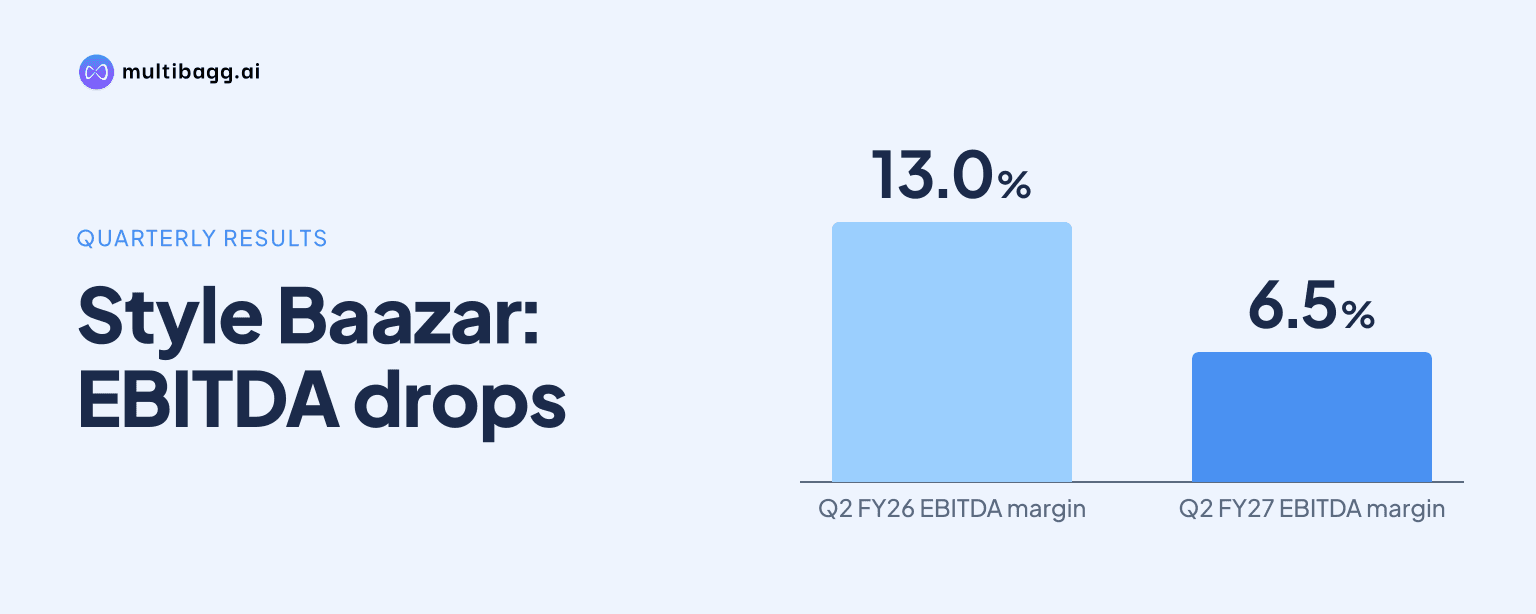
Baazar Style Retail Limited reported a consolidated loss after tax of Rs 32.1 crore in Q2 FY27, as Style Baazar’s earnings before interest, tax, depreciation and amortisation (EBITDA) fell 54.8% year on year to Rs 31.2 crore and EBITDA margin declined to 6.5% from 13.0%.
Know Baazar Style Retail inside out
Results, valuation, peers and who's buying, in one view.
Why did Style Baazar report a Q2 FY27 loss?
Style Baazar reported the Q2 FY27 loss after revenue, gross profit and EBITDA all declined from both Q2 FY26 and Q1 FY27. Revenue from operations was Rs 478.5 crore, down 10.0% year on year from Rs 531.5 crore and down 1.6% sequentially from Rs 486.4 crore. Gross profit fell 13.9% year on year to Rs 139.4 crore, compared with Rs 161.9 crore a year earlier.
Style Baazar recorded a profit after tax (PAT) of Rs 51.5 crore in Q2 FY26 and Rs 2.2 crore in Q1 FY27, before the Rs 32.1 crore loss in Q2 FY27. PAT margin moved from 9.6% in Q2 FY26 and 0.5% in Q1 FY27 to negative 6.7% in Q2 FY27. The presentation describes these as consolidated financial highlights.
Management attributed the quarterly comparison partly to the festive calendar moving from Q2 to Q3 FY27. It said it saw strong festive customer footfall, but expects a larger share of festive sales to be realised in H2 FY27, making Q2 FY27 not directly comparable with Q2 FY26.
How much did Style Baazar’s Q2 profitability change?
Style Baazar’s EBITDA fell to Rs 31.2 crore in Q2 FY27 from Rs 68.9 crore in Q2 FY26 and Rs 71.9 crore in Q1 FY27. The year-on-year reduction was 54.8%, while the sequential reduction was 56.6%. EBITDA margin declined by 644 basis points year on year and 826 basis points quarter on quarter, where 100 basis points equal one percentage point.
The margin change was larger than the revenue change in the sequential comparison. Revenue was Rs 7.9 crore lower than Q1 FY27, while EBITDA was Rs 40.7 crore lower. Gross profit declined by Rs 26.4 crore, alongside an EBITDA-margin reduction from 14.8% to 6.5%.
The half-year data show that the Q2 result reversed the profitable first quarter. For H1 FY27, EBITDA was Rs 103.1 crore, down 18.6% from Rs 126.8 crore in H1 FY26, while revenue rose 6.1% to Rs 964.9 crore. H1 PAT was a Rs 29.9 crore loss, against a Rs 53.5 crore profit in H1 FY26.
What operating measures declined during Q2 FY27?
Style Baazar’s sales per square foot per month declined 25.9% year on year to Rs 642 in Q2 FY27 from Rs 865 in Q2 FY26. It also declined 5.6% from Rs 679 in Q1 FY27. This measure fell while retail area increased 16.4% year on year to 2.67 million square feet at the end of the quarter.
The number of bills fell 4.0% year on year to 5.40 million, from 5.63 million in Q2 FY26, and was 2.2% below Q1 FY27’s 5.53 million. Average bill value was Rs 938, down 6.6% year on year from Rs 1,005 but 0.5% above Rs 933 in Q1 FY27. Quantity sold rose 0.4% year on year to 19.6 million units, although it declined 1.4% sequentially from 19.9 million units.
Own-brand sales represented 60% of Q2 FY27 sales, compared with 58% in Q2 FY26 and 62% in Q1 FY27. For H1 FY27, own brands accounted for 61% of sales, against 59% a year earlier. Management’s FY27 target is a 65% own-brand sales contribution, placing the half-year mix 4 percentage points below that target.
Got a follow-up? Ask IRIS
How did store expansion affect Style Baazar’s Q2 performance?
Style Baazar ended Q2 FY27 with 283 stores, 33 more than the 250 stores at the end of Q2 FY26 and seven more than the 276 at the end of Q1 FY27. It opened 10 stores during Q2 FY27 in West Bengal, Bihar, Uttar Pradesh and Andhra Pradesh. The 283-store network operated across 10 states at 30 September 2026.
Management said new stores take time to reach optimal sales levels and initially incur rental, employee and depreciation costs, putting pressure on margins. Average store size rose to 9,442 square feet from 9,185 square feet a year earlier and 9,347 square feet in Q1 FY27. The presentation also said newly opened stores were in initial stabilisation and revenue ramp-up phases, weighing on bills and sales per square foot.
H1 FY27 same-store sales growth was negative 11.5%, compared with positive 10.2% in H1 FY26. Style Baazar said H1 FY27 did not include the festive season, while H1 FY26 included its start. Inventory days on revenue rose to 143 at 30 September 2026 from 108 a year earlier, with management saying inventory had been built for the October festive season.
What is Style Baazar guiding for after Q2 FY27?
Style Baazar management is guiding for 25% year-on-year revenue growth for FY27, while seeking to capture festive demand in the upcoming quarter. The company said it will continue expanding its store network across core and focus markets and increase own-brand contribution. This is management guidance, not a reported FY27 result.
Core markets accounted for 79% of H1 FY27 sales, down from 84% in H1 FY26, while focus markets accounted for 21%, up from 16%. Style Baazar defines core markets as West Bengal, Odisha, Assam and Bihar, and focus markets as Jharkhand, Andhra Pradesh, Tripura, Uttar Pradesh, Arunachal Pradesh and Madhya Pradesh. Apparel remained 87% of sales and general merchandise 13% in both half-years.
The apparel mix changed modestly in H1 FY27: men’s apparel accounted for 39% of sales, down from 41% in H1 FY26; women’s rose to 32% from 31%; and kids’ rose to 29% from 28%. Private labels increased to 61% of sales from 59%, while other brands declined to 39% from 41%. These mix changes occurred alongside H1 revenue growth of 6.1% and an EBITDA margin decline to 10.7% from 13.9%.
Conclusion
Style Baazar’s Q2 FY27 deterioration extended across revenue, gross profit, operating margin and PAT. Revenue declined 10.0% year on year to Rs 478.5 crore, EBITDA declined 54.8% to Rs 31.2 crore, and PAT changed from a Rs 51.5 crore profit to a Rs 32.1 crore loss. The 283-store network expanded retail area while sales per square foot declined to Rs 642.
The next disclosed checkpoint is the upcoming festive quarter, which management expects to contain a larger share of festive sales than Q2 FY27. Investors can watch whether FY27 guidance of 25% year-on-year revenue growth, the 65% own-brand target and the stabilisation of recently opened stores are reflected in revenue, sales per square foot, EBITDA margin and inventory days after 30 September 2026.