










Superhouse Ltd Q1 FY27 Profit Returns at ₹3.56 Crore
Key highlights
- Superhouse reported Q1 FY27 net profit of ₹3.56 crore versus a ₹0.35 crore loss in Q1 FY26.
- Q1 FY27 revenue rose 2.1% year-on-year to ₹166 crore.
- Q1 FY27 EPS improved to ₹4.09 from a loss per share of ₹0.26.
- Superhouse scheduled its Q2 FY27 and half-year results board meeting for 14 November 2026.
powered by IRIS
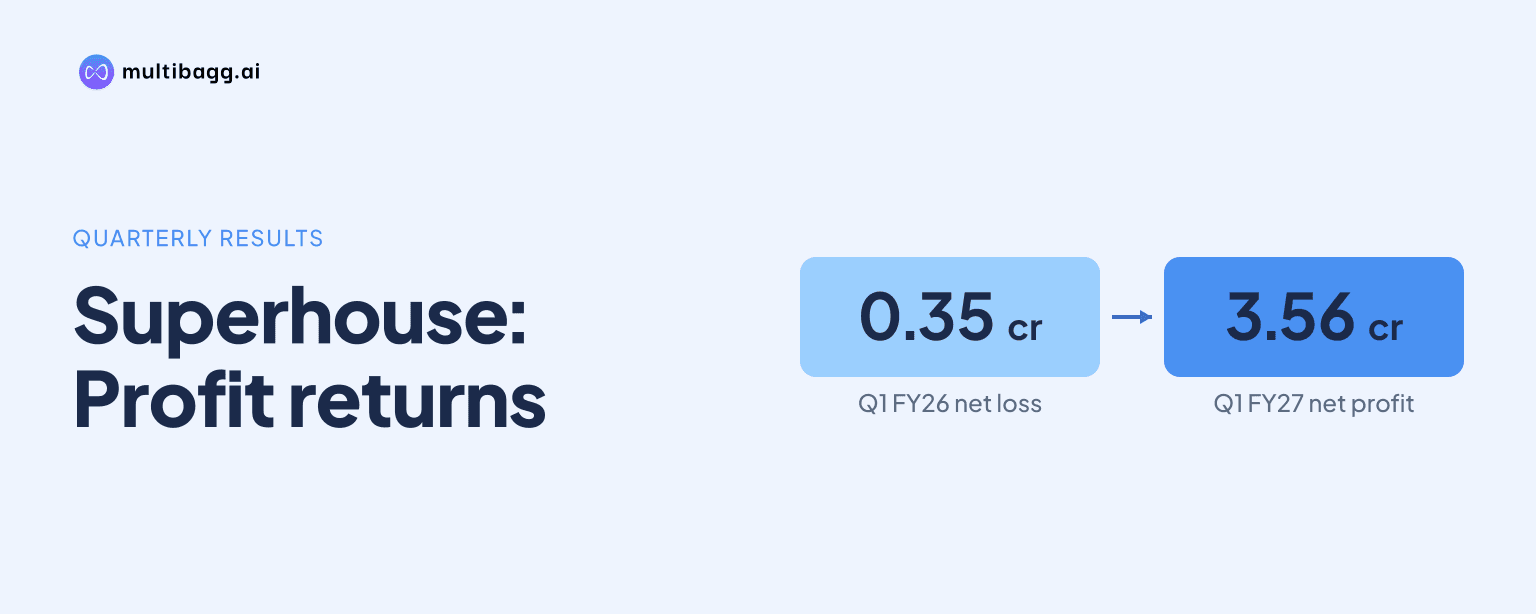
Superhouse Ltd returned to a net profit of ₹3.56 crore in Q1 FY27, compared with a ₹0.35 crore loss in Q1 FY26. Revenue rose 2.1% year-on-year to ₹166 crore, while earnings per share improved to ₹4.09 from a loss per share of ₹0.26, marking a return to profitability.
Know Superhouse inside out
Results, valuation, peers and who's buying, in one view.
How did Superhouse perform in Q1 FY27?
Superhouse reported a profit after a loss-making first quarter a year earlier. Net income was ₹3.56 crore in the quarter ended June 2026, an improvement of ₹3.91 crore from the ₹0.35 crore loss reported in Q1 FY26. The result indicates that the company crossed into positive earnings despite limited growth in reported revenue.
Revenue for the quarter was ₹166 crore, up 2.1% from the corresponding quarter of the previous financial year. The figures are stated in crore for consistency, with the reported revenue of ₹1.66 billion converted to ₹166 crore. The available information does not provide a detailed break-up of sales by product, geography, or operating segment.
The company had filed its Q1 FY27 results on 13 August 2026. Its reported basic earnings per share rose to ₹4.09, against a loss per share of ₹0.26 in Q1 FY26. Earnings per share and net profit both reflect the change from a loss to a profit in the period.
What were the key Q1 FY27 financial figures?
Superhouse recorded ₹166 crore in revenue, ₹3.56 crore in net profit and earnings per share of ₹4.09 in Q1 FY27. Revenue growth was modest at 2.1% year-on-year, but profitability improved materially because the comparable quarter had recorded a net loss.
The source also describes Superhouse as a micro-cap company in the diversified consumer products industry. It cites an average trailing price-to-earnings ratio of 18 times for India’s luxury industry, though no company-specific trailing P/E ratio is provided and the two industry labels should not be treated as directly comparable.
When will Superhouse consider its Q2 FY27 results?
Superhouse scheduled a board meeting for 14 November 2026 to consider and approve standalone and consolidated financial results for the quarter and half year ended 30 September 2026. The company’s board-meeting intimation was filed with the exchanges on 31 October 2026, while another filing dated 2 November referred to the same proposed meeting.
The materials also refer to newspaper notices regarding the proposed board meeting. Those notices state the purpose of the meeting but do not contain Q2 or half-year financial figures. As a result, the available information supports the scheduled consideration of the results, not any specific Q2 FY27 financial outcome.
Superhouse had earlier announced its Q1 FY27 results 44 days after the June quarter ended. The indicated Q2 FY27 meeting date is 45 days after the September quarter-end, providing a similar timeline for the company’s quarterly reporting process.
Got a follow-up? Ask IRIS
Why does the return to profit matter for investors?
The return to profit matters because Superhouse moved from a net loss in the comparable quarter to positive earnings while revenue increased by 2.1%. A ₹3.91 crore year-on-year improvement in net income is larger than the movement in revenue, although the source does not disclose the underlying drivers, such as cost changes, product mix or other income.
For shareholders, the earnings result provides a clearer base for assessing quarterly performance than the prior-year loss. However, the reported data alone does not establish whether the Q1 profit trend continued into the September quarter. Investors will need the standalone and consolidated Q2 and half-year disclosures for updated revenue, margins, profit and earnings-per-share information.
The company’s share price was stated at ₹148.10 in the supplied information. No share-price reaction to the Q1 announcement is provided for Superhouse, so no link can be drawn between the reported financial performance and the stock’s subsequent movement.
What is the relevant reporting background for Superhouse?
Superhouse’s 46th annual general meeting was held on 30 September 2026. The meeting approved the FY26 financial statements, a dividend of ₹0.80 per share and the reappointment of two directors, according to the provided information. The company has also filed its FY26 annual report under the theme “Strength in Manufacturing, Excellence in Execution.”
The Q2 and half-year results, when disclosed, are expected to carry the board’s approval and the statutory auditor’s limited review in accordance with SEBI Regulation 33. That review process is relevant because it is part of the quarterly financial-reporting framework for listed companies.
Conclusion
Superhouse’s Q1 FY27 financial performance showed a return to profitability, with net income of ₹3.56 crore and EPS of ₹4.09, compared with losses in the year-earlier quarter. Revenue of ₹166 crore was only 2.1% higher year-on-year, making the improvement in profit the central feature of the quarter.
The next disclosed event is the board’s consideration of Q2 FY27 and half-year results for the period ended 30 September 2026 on 14 November 2026. Investors will watch for the reported revenue, profit, EPS and any management disclosures that explain whether the first-quarter return to profit was sustained.