










Supreme Engineering clears NPA-linked loan dues through OTS
Key highlights
- Supreme Engineering completed its full OTS payment on 11 November 2026 and received a lender no-dues certificate.
- Supreme Engineering’s secured loan account had been classified as an NPA on 19 August 2021.
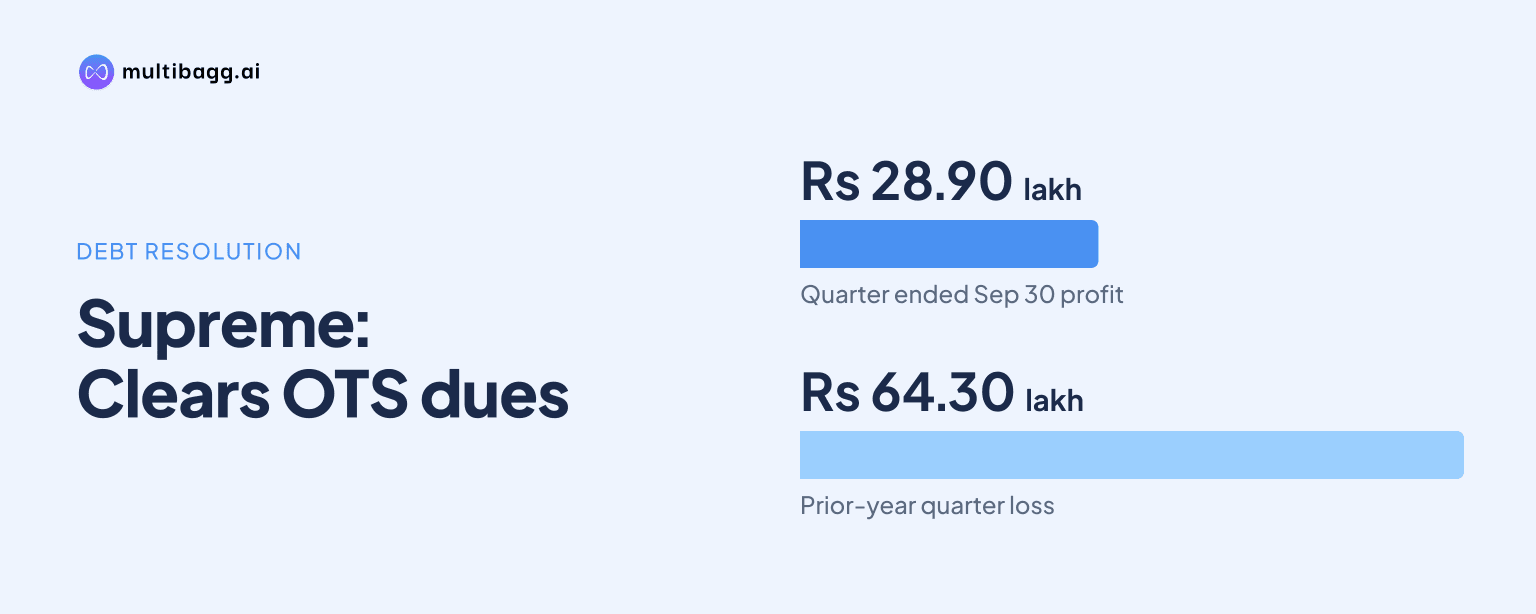
- Supreme Engineering reported Rs 28.90 lakh profit for the quarter ended 30 September 2026, against a Rs 64.30 lakh loss a year earlier.
- Supreme Engineering will recognise any OTS gain in the quarter ending 31 December 2026, not in September 2026 results.
powered by IRIS
Supreme Engineering Limited completed its lender-approved one-time settlement on 11 November 2026, received a no-dues certificate and discharged the borrowing classified as a non-performing asset since 19 August 2021. The September results exclude any settlement gain because the liability was extinguished after the 30 September 2026 reporting date.
Know Supreme Engineering inside out
Results, valuation, peers and who's buying, in one view.
When did Supreme Engineering complete the OTS settlement?
Supreme Engineering completed payment of the entire one-time settlement, or OTS, amount on 11 November 2026, after the 30 September 2026 reporting date. The lender issued a no-dues certificate confirming settlement of the outstanding loan dues and discharge of Supreme Engineering’s liability for the borrowing covered by the arrangement.
The lender had approved the OTS proposal on 13 August 2026, subject to terms in its approval or sanction letter. Supreme Engineering deposited an initial amount equal to 10% of the proposed settlement amount following that approval, then completed the remaining payment nearly three months later. The filing does not disclose either the agreed settlement consideration or the carrying amount of the specific liability.
The secured loan account had been classified as a non-performing asset, or NPA, by the lending bank on 19 August 2021. Supreme Engineering said it stopped servicing borrowing repayments and interest after that classification, while it incurred losses over prior years and remained under financial stress. It also said it informed the stock exchange after completing the OTS on 11 November 2026.
The settlement was completed before the unaudited September results and limited-review report were dated 14 November 2026. Supreme Engineering therefore disclosed the payment as a significant subsequent event rather than including its financial effect in the balance sheet as at 30 September 2026.
When will Supreme Engineering record the OTS gain?
Supreme Engineering will record any gain arising from the OTS in the quarter ending 31 December 2026, rather than in the quarter or half year ended 30 September 2026. The company said the gain will be measured as the difference between the carrying amount of the financial liability and the settlement consideration under Indian Accounting Standard 109, or Ind AS 109, Financial Instruments.
No gain from extinguishing the liability was recognised in the September 2026 financial results because full payment occurred only on 11 November 2026. The lender’s 13 August approval did not itself extinguish the borrowing, according to the accounting treatment set out in the filing.
This distinction affects interpretation of the half-year profit. Supreme Engineering reported profit for the period of Rs 1.78 crore for the half year ended 30 September 2026, compared with a loss of Rs 57.58 lakh in the corresponding half year ended 30 September 2025. That reported result excludes any benefit from the debt settlement completed after the period end.
The June 2026 quarter included an exceptional item of Rs 2.46 crore, while the September 2026 quarter showed no exceptional item. Supreme Engineering did not identify the OTS as the source of that June item, and its notes explicitly state that no OTS gain was recognised through 30 September 2026.
How did Supreme Engineering perform before the OTS completion?
Supreme Engineering reported a profit of Rs 28.90 lakh in the quarter ended 30 September 2026, compared with a loss of Rs 64.30 lakh in the quarter ended 30 September 2025. Revenue from operations increased to Rs 578.74 lakh from Rs 513.53 lakh, while total revenue rose to Rs 581.64 lakh from Rs 535.35 lakh.
The quarter-on-quarter comparison within the 2026 half year also changed materially. Revenue from operations rose from Rs 206.95 lakh in the quarter ended 30 June 2026 to Rs 578.74 lakh in the September quarter, while Supreme Engineering moved from profit of Rs 1.49 crore in June to Rs 28.90 lakh in September. The June result included the Rs 2.46 crore exceptional item.
For the half year, however, revenue from operations declined to Rs 9.86 crore from Rs 13.54 crore a year earlier, and total revenue fell to Rs 9.96 crore from Rs 14.00 crore. Supreme Engineering nevertheless moved to a half-year profit of Rs 1.78 crore from a Rs 57.58 lakh loss. The company also said earnings before interest, depreciation and tax, or EBITDA, was positive in the September 2026 quarter, without giving a separate EBITDA figure.
Got a follow-up? Ask IRIS
How had Supreme Engineering’s borrowings changed by September?
Supreme Engineering reported total current and non-current borrowings of Rs 95.38 crore as at 30 September 2026, compared with Rs 90.39 crore at 31 March 2026. Those balances cover all reported borrowings and do not establish the amount paid under the OTS, which the filing does not disclose.
The mix shifted during the six months ended 30 September 2026. Current borrowings fell by Rs 6.72 crore, while non-current borrowings rose by Rs 11.71 crore, producing a Rs 4.99 crore increase in total reported borrowings. As the OTS was completed on 11 November, the September balance sheet did not reflect the subsequent discharge confirmed by the no-dues certificate.
The balance sheet reported negative other equity of Rs 112.59 crore at 30 September 2026, compared with negative other equity of Rs 114.43 crore at 31 March 2026. The limited-review auditor said current liabilities exceeded total assets and that the company had negative net worth, conditions it identified as creating material uncertainty over going-concern status.
What does Supreme Engineering say about continuity after the settlement?
Supreme Engineering said management prepared the September 2026 results on a going-concern basis after considering its operational performance, the lender’s OTS approval and the subsequent completion of the settlement. Management also cited measures to improve the financial position and business operations, and said the OTS is expected to have a positive effect on financial position and the ability to continue operations.
To meet the OTS terms, Supreme Engineering said management explored fund infusion, preferential allotment and monetisation of assets. The filing does not say which of those measures supplied the settlement funds, nor does it quantify the expected financial impact of the discharge beyond the gain due for recognition in the December 2026 quarter.
The limited-review auditor said Supreme Engineering’s ability to continue as a going concern remains dependent on generating sufficient operating cash flows, improving its financial position and sustaining operations. The auditor said the ultimate outcome could not be determined with certainty as at 14 November 2026, despite the 11 November settlement completion.
The auditor also identified unresolved matters, including an unfiled income-tax audit report and return for financial year 2020-21, overdue statutory dues and no cost audit from financial year 2020-21 onward. It additionally cited ongoing income-tax and goods and services tax litigation, with the financial impact dependent on the outcomes of those proceedings.
Conclusion
Supreme Engineering’s full OTS payment on 11 November 2026 and the lender’s no-dues certificate settle the NPA-linked borrowing identified in the filing. The event follows the 13 August 2026 approval and a 10% initial deposit, while the September quarter had already returned to a Rs 28.90 lakh profit without including any settlement gain.
The next disclosed milestone is the quarter ending 31 December 2026, when Supreme Engineering says it will recognise any gain from the extinguished liability under Ind AS 109. Results from that period will also show whether operating cash generation and financial-position measures develop in line with the conditions the auditor said remain necessary for continuity.