










TACL reports record Q2 as EBITDA margin reaches 17.6% in FY27
Key highlights
- TACL’s Q2 FY27 revenue from operations rose 23% year on year to Rs 267.5 crore.
- TACL’s Q2 FY27 EBITDA increased 33% to Rs 47.2 crore and margin rose to 17.6% from 16.4%.
- TACL’s Q2 FY27 PAT rose 43% year on year to Rs 32.9 crore.
- MTCS total income grew 54% to Rs 60.8 crore in Q2 FY27 on a proportionate joint-venture basis.
powered by IRIS
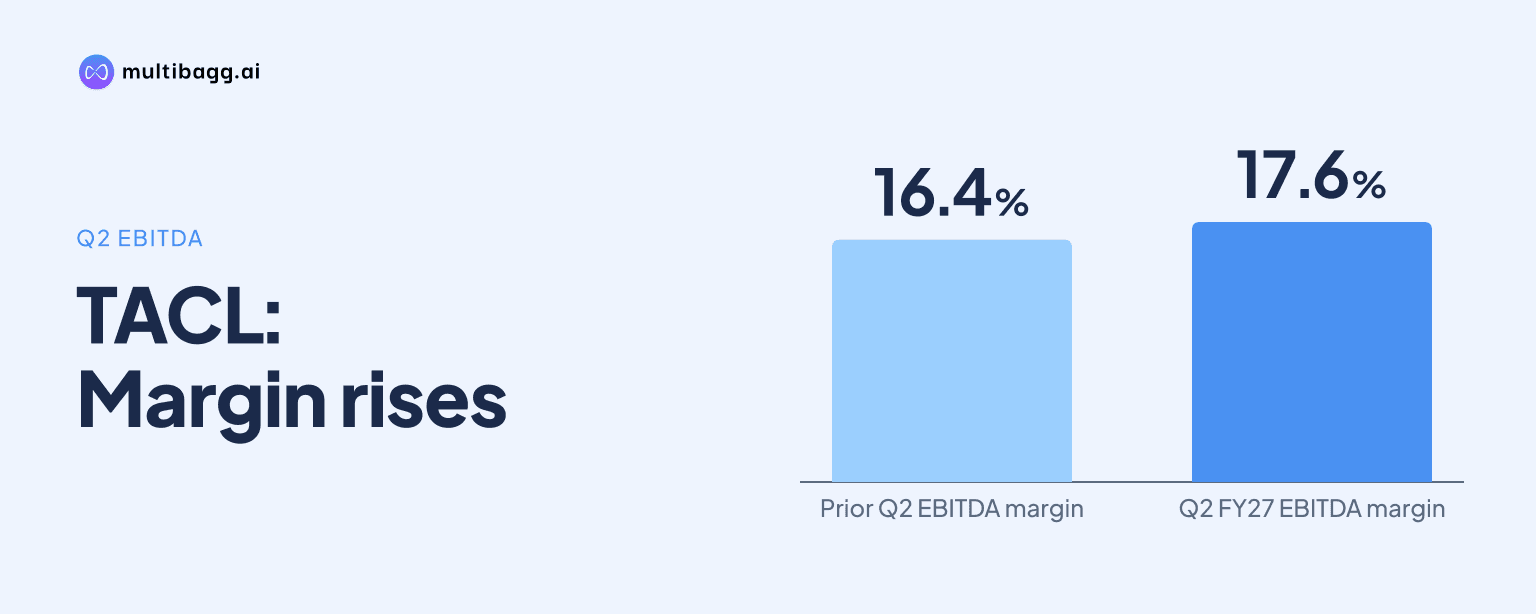
Talbros Automotive Components Limited, or TACL, reported its strongest-ever quarterly performance for Q2 FY27 ended 30 September 2026, with revenue from operations rising 23% year on year to Rs 267.5 crore and EBITDA margin expanding to 17.6% from 16.4%. Profit after tax increased 43% to Rs 32.9 crore.
Know Talbros Automotive Components inside out
Results, valuation, peers and who's buying, in one view.
How did TACL’s Q2 FY27 profit and margin change?
TACL’s Q2 FY27 operating profit grew faster than revenue, as earnings before interest, tax, depreciation and amortisation (EBITDA) rose 33% year on year to Rs 47.2 crore, compared with a 23% rise in revenue from operations to Rs 267.5 crore. EBITDA margin increased by 1.2 percentage points, or 120 basis points, from 16.4% in Q2 FY26 to 17.6% in Q2 FY27.
Profit after tax (PAT) rose 43% to Rs 32.9 crore from Rs 23.1 crore, while PAT margin moved to 12.3% from 10.7%. Profit before tax was Rs 42 crore, up 43% year on year, according to the company’s quarterly financial highlights. TACL’s stated figures include other income, which applies to both its revenue and EBITDA disclosures.
The half-year comparison showed a similar pattern. H1 FY27 revenue from operations increased 19% to Rs 509.7 crore from Rs 427.4 crore in H1 FY26, while EBITDA rose 28% to Rs 89.9 crore. The H1 EBITDA margin was 17.6%, compared with 16.5% a year earlier, and PAT increased 39% to Rs 63 crore from Rs 45.3 crore.
Which TACL businesses led revenue and EBITDA growth?
TACL’s Gasket and Heat Shield business was the largest reported operating division in Q2 FY27, with total income of Rs 176.4 crore, up 23% from Rs 142.8 crore in Q2 FY26. Its EBITDA rose 38% to Rs 33.3 crore from Rs 24.1 crore, the quickest EBITDA growth among the four reported businesses.
The Forgings business recorded Q2 FY27 total income of Rs 92.5 crore, up 23% from Rs 75.5 crore, while EBITDA increased 19% to Rs 15.3 crore. Management said Gasket and Heat Shield growth reflected sustained original equipment manufacturer, or OEM, demand and improved recovery of price increases, while the Forgings division also grew 23%.
TACL’s joint ventures contributed faster revenue growth than its two main divisions on the proportionate basis used in the release. Marelli Talbros Chassis Systems, or MTCS, recorded total income of Rs 60.8 crore, a 54% increase from Rs 39.6 crore, and EBITDA increased 31% to Rs 9.7 crore. Talbros Marugo Rubber, or TMR, reported income of Rs 23.3 crore, up 33%, with EBITDA up 19% to Rs 2.4 crore.
For H1 FY27, Gasket and Heat Shield income rose 22% to Rs 340.1 crore and Forgings income rose 13% to Rs 171 crore. MTCS income grew 49% to Rs 113.2 crore, while TMR income increased 32% to Rs 43.1 crore. The two joint-venture revenue measures are disclosed on a proportionate basis and should be read as such rather than added to consolidated revenue.
Got a follow-up? Ask IRIS
How did TACL’s revenue mix change in Q2 FY27?
TACL’s exports accounted for 28% of income from operations in Q2 FY27, up from 25% in Q2 FY26, while OEM business accounted for 62% of the market-based revenue mix, down from 64%. The export share was particularly high in Forgings, where exports represented 57% of revenue, compared with 15% for Gaskets, 27% for MTCS and 7% for TMR.
The domestic vehicle mix shifted towards commercial vehicles in the quarter. Heavy commercial vehicles and light commercial vehicles accounted for 22% of Q2 FY27 domestic revenue, up from 20%, while passenger vehicles represented 35%, up from 34%. Two- and three-wheelers declined to 15% from 17%, and agriculture and off-loader applications fell to 12% from 15%.
In H1 FY27, exports were 26% of income from operations, unchanged from H1 FY26. The OEM share was also unchanged at 63%, while aftermarket revenue remained 3% and other markets were 8%. Within domestic revenue, commercial vehicles rose to 23% from 22%, passenger vehicles remained 34%, and two- and three-wheelers declined to 15% from 16%.
Management said newly commercialised orders across chassis, forgings and heat shields were contributing to revenue growth after some had been awaiting customer launch timelines. It also identified data centres as a newer application for TACL gaskets used in engines that power backup generators, alongside the company’s traditional automotive markets.
What is TACL management expecting after H1 FY27?
TACL management expects H2 FY27 to be stronger than H1 FY27, supported by the ramp-up of recently commercialised orders and contributions from new orders. This is management’s outlook rather than a financial target, and the release notes near-term pressure from freight, energy, steel and other commodity prices.
Together with its joint ventures, TACL said it had secured new orders worth more than Rs 1,000 crore for execution over the next five years. Management said approximately Rs 700 crore of these orders came from export markets and Rs 100 crore from the electric-vehicle segment, providing what it described as medium-term revenue visibility.
Management said its response to cost pressures is disciplined execution and cost optimisation intended to protect margins. The Q2 FY27 EBITDA margin was 17.6%, compared with 16.4% a year earlier, while freight, energy, steel and other commodity prices remain identified near-term pressures.
TACL operates across gaskets, heat shields, forgings, suspension systems, anti-vibration products and hoses. The release states that TACL and its joint-venture alliances have 11 manufacturing facilities in Haryana, Uttarakhand and Maharashtra, plus a materials division in Gurgaon and a research and development technology centre in Faridabad.
Conclusion
TACL’s Q2 FY27 performance showed profit growing faster than revenue, with EBITDA increasing 33% and PAT increasing 43%, alongside a 120-basis-point expansion in EBITDA margin. The growth was spread across Gasket and Heat Shield, Forgings, MTCS and TMR, while exports increased to 28% of quarterly income from operations from 25% a year earlier.
The next disclosed period to watch is H2 FY27, which management expects to be stronger than H1 as recently commercialised orders ramp up and new orders begin contributing. Execution of more than Rs 1,000 crore of orders over five years, including about Rs 700 crore from exports and Rs 100 crore from electric vehicles, will occur alongside management’s stated efforts to manage freight, energy, steel and commodity-cost pressures.