










Tarini profit stays flat as associates contribute Rs 81.04 lakh
Key highlights
- Tarini reported consolidated profit of Rs 99.27 lakh for the six months ended September 30, 2026, versus Rs 99.09 lakh a year earlier.
- Tarini's share of profit from associates increased to Rs 81.04 lakh from Rs 73.08 lakh.
- Profit from continuing operations declined to Rs 18.23 lakh from Rs 26.01 lakh.
- Cash and cash equivalents fell to Rs 29.32 lakh at September 30, 2026 from Rs 48.27 lakh at March 31, 2026.
powered by IRIS
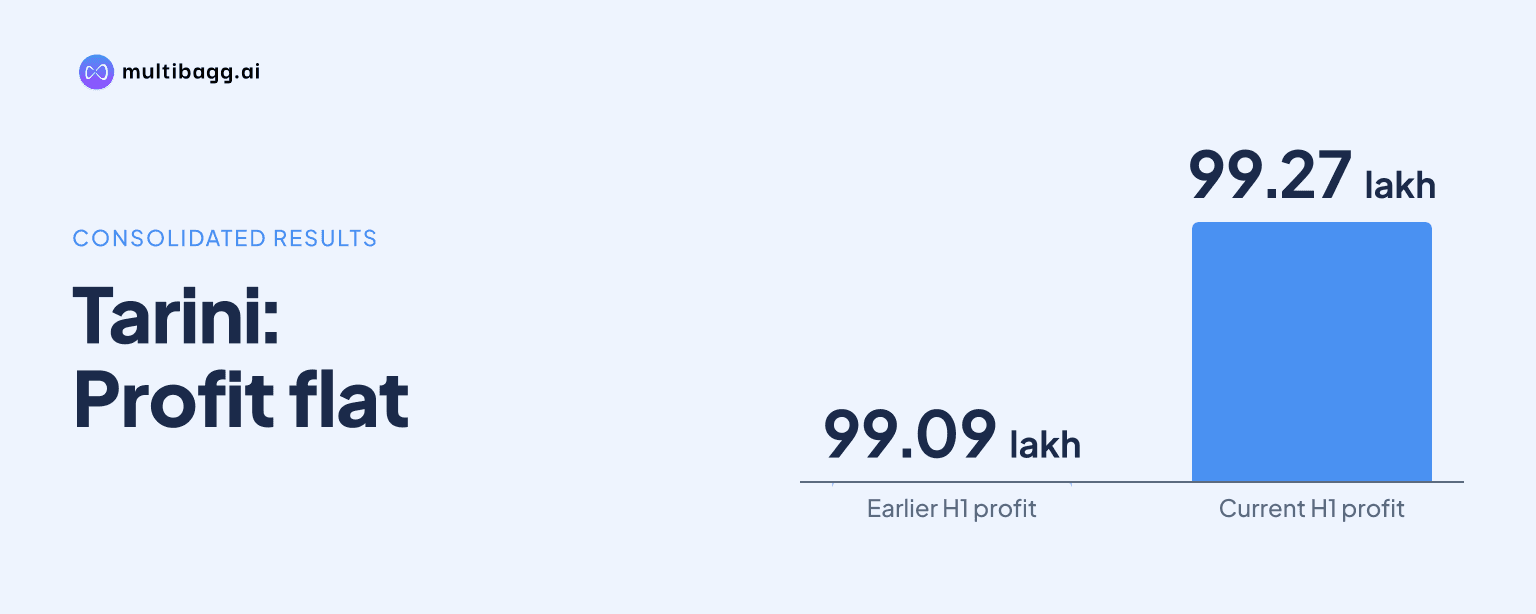
Tarini International Limited reported consolidated profit of Rs 99.27 lakh for the six months ended September 30, 2026, compared with Rs 99.09 lakh a year earlier, as Rs 81.04 lakh of profit from associates offset a fall in profit from continuing operations to Rs 18.23 lakh from Rs 26.01 lakh.
Know Tarini International inside out
Results, valuation, peers and who's buying, in one view.
What drove Tarini's September 2026 consolidated profit?
Tarini's consolidated profit was driven chiefly by its Rs 81.04 lakh share of profit from associates in the half year ended September 30, 2026. Profit from continuing operations was Rs 18.23 lakh after tax, while the consolidated results reported no profit or loss from discontinuing operations.
The associate contribution represented most of Tarini's Rs 99.27 lakh consolidated profit, compared with Rs 73.08 lakh of associate profit and Rs 99.09 lakh of total profit in the six months ended September 30, 2025. The Rs 7.96 lakh increase in the associates' contribution broadly offset the Rs 7.78 lakh reduction in continuing-operations profit.
Tarini's total income increased to Rs 125.35 lakh from Rs 117.04 lakh in the comparable 2025 half year. Revenue from operations was unchanged at Rs 108.00 lakh, while other income rose to Rs 17.35 lakh from Rs 9.04 lakh, accounting for the Rs 8.31 lakh increase in total income.
How did Tarini's continuing operations change year on year?
Tarini's profit from continuing operations declined to Rs 18.23 lakh in the September 2026 half year from Rs 26.01 lakh a year earlier because expenses increased faster than income. Profit before tax fell to Rs 35.64 lakh from Rs 43.39 lakh, although total income increased by Rs 8.31 lakh.
Total expenses rose to Rs 89.71 lakh from Rs 73.65 lakh, an increase of Rs 16.06 lakh. Employee benefits expense rose by Rs 11.71 lakh to Rs 54.79 lakh, other expenses increased by Rs 6.17 lakh to Rs 30.51 lakh, and depreciation and amortisation increased to Rs 4.19 lakh from Rs 4.01 lakh.
Finance cost was Rs 0.21 lakh in the latest half year, compared with Rs 0.22 lakh in the prior-year period. Tarini reported no cost of materials consumed, purchases of stock in trade, or inventory-change expense in either six-month period, indicating that the reported expense movement came from employee, other and depreciation costs.
Tax expense totalled Rs 17.42 lakh in the half year ended September 30, 2026, comprising Rs 10.52 lakh of current tax and Rs 6.90 lakh of deferred tax. The comparable tax expense was Rs 17.39 lakh, comprising Rs 13.25 lakh of current tax and Rs 4.14 lakh of deferred tax, so the lower continuing profit followed the decline in pre-tax profit rather than a higher total tax charge.
Basic and diluted earnings per equity share were Rs 0.69 for the September 2026 half year, compared with Rs 0.68 in the corresponding period of 2025. The full year ended March 31, 2026 had reported consolidated profit of Rs 164.82 lakh and earnings per share of Rs 1.27.
Got a follow-up? Ask IRIS
What does Tarini's September 2026 balance sheet show?
Tarini reported total assets and total equity and liabilities of Rs 42.28 crore at September 30, 2026, compared with Rs 42.26 crore at March 31, 2026. Share capital was unchanged at Rs 13.00 crore, while reserves and surplus increased to Rs 14.78 crore from Rs 14.46 crore.
Short-term loans and advances were the largest listed asset item at Rs 19.01 crore, compared with Rs 18.95 crore at the March 2026 year-end. Non-current investments stood at Rs 11.70 crore and current investments at Rs 1.16 crore, both broadly unchanged from March 31, 2026.
Trade receivables increased to Rs 1.73 crore at September 30, 2026 from Rs 1.53 crore at March 31, 2026. Cash and cash equivalents decreased to Rs 29.32 lakh from Rs 48.27 lakh, with the cash-flow statement recording a net decrease of Rs 18.96 lakh during the six-month period.
The cash-flow statement showed Rs 36.56 lakh of negative cash flow from operating activities for the half year, alongside Rs 17.35 lakh of cash flow from investing activities and Rs 0.25 lakh from financing activities. It showed working-capital movements of Rs 7.32 crore in current assets and Rs 7.91 crore in current liabilities, as presented in the filing.
Short-term borrowings declined to Rs 13.34 crore at September 30, 2026 from Rs 13.55 crore at March 31, 2026. Other current liabilities fell to Rs 78.74 lakh from Rs 87.70 lakh, and long-term borrowings declined to Rs 2.66 lakh from Rs 3.12 lakh.
What review qualifications and legal matters did Tarini disclose?
Tarini's statutory auditor issued a qualified review conclusion because two subsidiaries had accumulated losses, recurring losses and net capital deficiency at September 30, 2026. Management prepared their financial statements on a going-concern basis and did not provide for diminution in an investment of Rs 1.22 crore in those subsidiaries.
The auditor also drew attention to receivables, loans and advances that remained subject to confirmation. Management considered the balances good and recoverable, but the auditor said it could not comment on their recoverability in the absence of confirmation and given the age of certain balances; short-term loans and advances were Rs 19.01 crore and trade receivables were Rs 1.73 crore.
The consolidated results included two subsidiaries whose unaudited financial information showed total assets of Rs 40.80 lakh, revenue of Rs 9.00 lakh and net loss after tax of Rs 3.79 lakh for the September 2026 half year. They also included Tarini's Rs 81.04 lakh share of net profit from two associates based on financial information not reviewed by those associates' auditors.
The auditor said management represented that the unreviewed subsidiary and associate information was not material to the group, and did not modify its conclusion on that basis. Tarini said it has one reportable primary segment under Accounting Standard 17, or AS 17, and therefore did not provide separate segment-wise results.
Tarini also disclosed that a farmhouse of the parent company, provisionally attached by the Enforcement Directorate in October 2017, remained covered by a Delhi High Court stay dated March 6, 2018. Its appeal against a Securities Appellate Tribunal order dated May 2, 2022 imposing a Rs 5.05 crore penalty was admitted by the Supreme Court and was to be listed for final hearing under an order dated December 18, 2024; the filing also said courts had dismissed nine Registrar of Companies cases in Tarini's favour.
Conclusion
Tarini's September 2026 half-year result showed consolidated profit holding at Rs 99.27 lakh despite a Rs 7.78 lakh decline in profit from continuing operations. The Rs 7.96 lakh increase in associate profit was the principal offset, while unchanged operating revenue of Rs 108.00 lakh was accompanied by higher employee and other expenses.
The next disclosures to watch are management's stated expectation of improved future operations at the loss-making subsidiaries, the treatment of the Rs 1.22 crore investment in them, and confirmation of receivables and advances. The filing also identifies a pending final hearing listing in Tarini's Supreme Court appeal against the Rs 5.05 crore penalty.