










TCC Concept auditor cannot verify Rs 9.32 crore receivables
Key highlights
- TCC Concept’s auditor could not comment on recovery of Rs 9.32 crore of receivables at September 30, 2026.
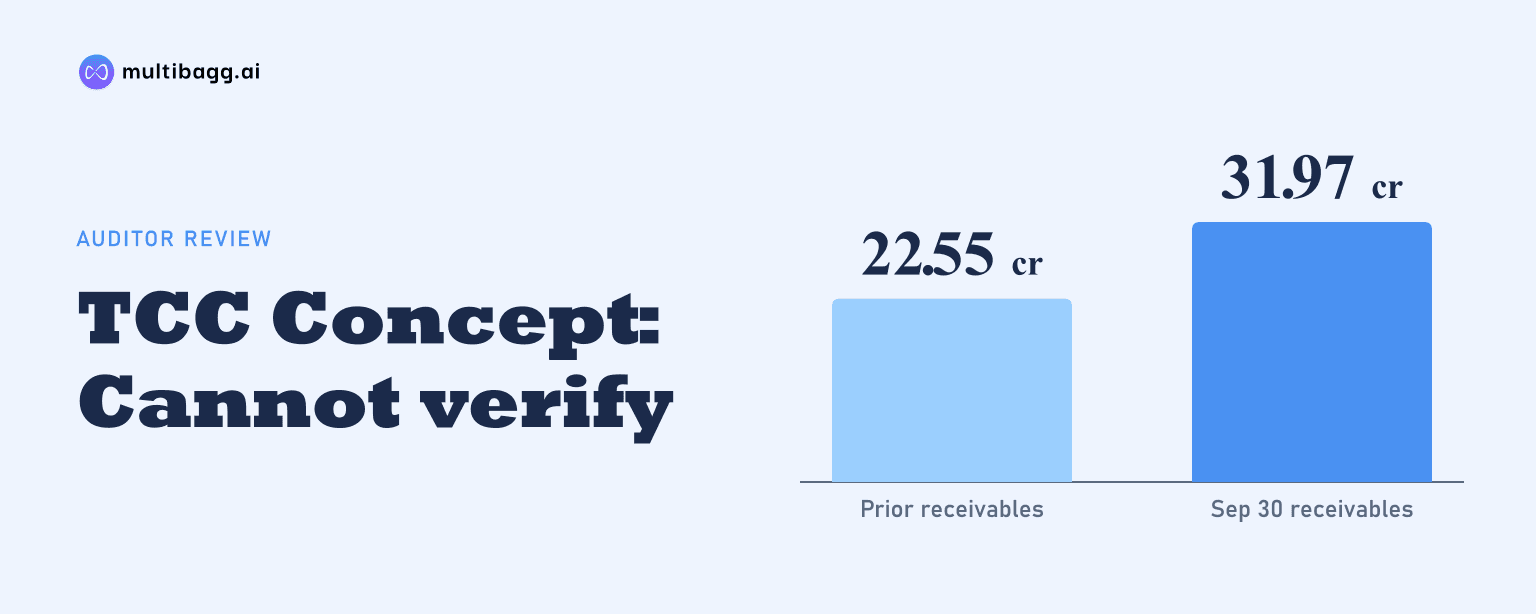
- TCC Concept’s standalone trade receivables rose to Rs 31.97 crore from Rs 22.55 crore in six months.
- TCC Concept reported half-year revenue from operations of Rs 31.76 crore, compared with Rs 24.52 crore a year earlier.
- TCC Concept’s half-year profit before tax was Rs 21.40 crore, versus Rs 21.55 crore in the prior-year period.
powered by IRIS
TCC Concept Limited’s auditor could not comment on the recoverability of Rs 9.32 crore of trade receivables outstanding since the beginning of the year at September 30, 2026, citing insufficient evidence such as customer confirmations or subsequent receipts. TCC Concept management considers its expected credit loss provision adequate, while its assessment continues.
Know TCC Concept inside out
Results, valuation, peers and who's buying, in one view.
What did TCC Concept’s auditor say about the receivables?
Mehra Goel & Co. LLP said it had not received sufficient appropriate evidence to support TCC Concept management’s assessment of Rs 9.32 crore of receivables outstanding since the start of the year. The auditor specifically identified external third-party direct balance confirmations and evidence of subsequent receipts as examples of evidence that had not been provided.
The matter appeared under “Basis of Qualified Conclusion” in the November 4, 2026 limited review report on TCC Concept’s standalone results for the quarter and half year ended September 30, 2026. The auditor said it was unable to comment on recoverability and on any consequential impact on the statement, if any.
The review was conducted under Standard on Review Engagements 2410, covering the period from April 1, 2026 to September 30, 2026. Mehra Goel & Co. LLP said a review is substantially narrower in scope than an audit and that it did not perform an audit or express an audit opinion.
The report otherwise said that, except for the possible effects of the receivables matter, nothing had come to the auditor’s attention indicating that the standalone statement failed to make required disclosures or contained a material misstatement. It also stated that the auditor’s conclusion was not modified in respect of the matter.
How large is the receivables issue on TCC Concept’s balance sheet?
TCC Concept reported standalone trade receivables of Rs 31.97 crore at September 30, 2026, compared with Rs 22.55 crore at March 31, 2026. The increase of Rs 9.42 crore over the six-month period was close to the Rs 9.32 crore balance identified in the auditor’s report, although the filing does not state that they are the same balances.
Total current assets increased to Rs 40.99 crore at September 30, 2026 from Rs 27.60 crore at March 31, 2026. Cash and cash equivalents moved lower to Rs 66.20 lakh from Rs 2.89 crore over the same dates.
The standalone cash-flow statement recorded a Rs 9.59 crore increase in trade receivables during the half year ended September 30, 2026. It was shown as a working-capital use of cash in the reconciliation from operating profit to operating cash flow.
What is management’s expected credit loss assessment?
TCC Concept management updated its expected credit loss assessment under Indian Accounting Standard 109, or Ind AS 109, and considers the provision held to be adequate. The company also said its assessment of the relevant balances is continuing as of the September 30, 2026 reporting date.
Expected credit loss is the accounting approach under Ind AS 109 for recognising potential losses on financial assets, including trade receivables. The auditor did not say the existing provision was inadequate, but said it could not assess management’s conclusion because supporting evidence was insufficient.
The filing does not disclose the provision amount held against the Rs 9.32 crore balance, individual counterparties, or ageing buckets beyond the statement that the receivables had been outstanding since the beginning of the year. It also gives no date by which TCC Concept expects to obtain customer confirmations or subsequent collections.
TCC Concept operates in one standalone reportable segment, Brokerage & Other Services. As a result, the September 30 results do not assign the questioned receivables to a particular service line or provide segment-level information on collection risk.
Got a follow-up? Ask IRIS
How did TCC Concept’s half-year financial results change?
TCC Concept reported revenue from operations of Rs 31.76 crore for the half year ended September 30, 2026, up from Rs 24.52 crore in the corresponding half year ended September 30, 2025. Total income increased to Rs 34.45 crore from Rs 27.38 crore over the same comparison.
Profit before tax was Rs 21.40 crore for the six months ended September 30, 2026, compared with Rs 21.55 crore a year earlier. Profit for the period declined to Rs 15.55 crore from Rs 16.12 crore, while total comprehensive income was Rs 15.55 crore.
Total equity rose to Rs 1,499.15 crore at September 30, 2026 from Rs 1,479.09 crore at March 31, 2026. Total current liabilities declined to Rs 35.01 crore from Rs 37.88 crore, while non-current borrowings increased to Rs 9.86 crore from Rs 6.04 crore.
What other September 2026 developments did TCC Concept disclose?
TCC Concept completed a share subdivision from a face value of Rs 10 per equity share to Rs 2 per share, following shareholder approval on August 22, 2026. The subdivision took effect on September 4, 2026 and increased issued shares from 4,75,28,061 to 23,76,40,305 without changing authorised, issued or paid-up share capital.
The board approved a scheme to amalgamate wholly owned subsidiary Altrr Software Services Limited with TCC Concept. The company filed its application seeking National Company Law Tribunal approval on September 10, 2026, and the filing does not provide an approval date or completion schedule.
TCC Concept reported Rs 9.24 crore of borrowing proceeds and Rs 5.42 crore of borrowing repayments in the half-year cash-flow statement. Net cash used in operating activities was Rs 6.27 crore for the period ended September 30, 2026, while cash and cash equivalents closed at Rs 66.20 lakh.
The filing was approved by TCC Concept’s board on November 4, 2026 and covers unaudited standalone results. The auditor’s stated evidence limitation concerns the Rs 9.32 crore receivables balance rather than the company’s disclosed share subdivision or proposed subsidiary amalgamation.
Conclusion
TCC Concept’s September 30, 2026 standalone filing combines higher revenue and a Rs 9.42 crore increase in trade receivables with an auditor evidence limitation over Rs 9.32 crore of receivables outstanding since the beginning of the year. Management considers the expected credit loss provision adequate, but the auditor could not comment on recovery or any resulting financial-statement effect.
The next items to watch are whether TCC Concept discloses customer confirmations, subsequent receipts or a changed expected-credit-loss provision for the receivables under assessment. The company also disclosed that its National Company Law Tribunal application for the Altrr Software Services Limited amalgamation was filed on September 10, 2026, with no timetable stated in the results.