










TCIL shareholders receive 81 SHRL shares per 100 holdings
Key highlights
- Eligible TCIL shareholders would receive 81 fully paid SHRL shares for every 100 TCIL shares of Rs 1 each.
- Each SHRL equity share issued under the entitlement has a face value of Rs 10.
- The scheme proposes to consolidate 4 TCIL shares of Rs 1 into 1 share of Rs 4, followed by a reduction to Rs 3.
- BSE and NSE issued scheme observation or no-objection letters on August 31, 2026 and September 1, 2026, respectively.
powered by IRIS
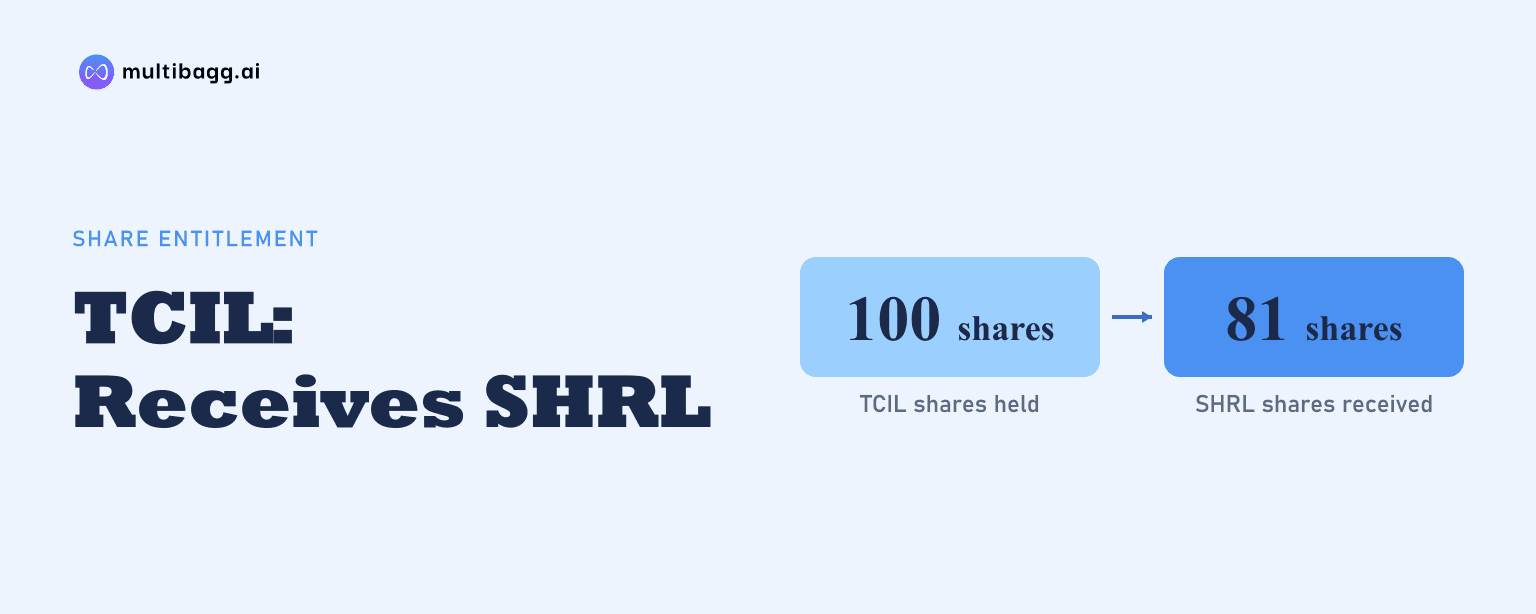
Thomas Cook (India) Limited (TCIL) proposes to issue eligible shareholders 81 fully paid equity shares of Sterling Holiday Resorts Limited (SHRL) for every 100 TCIL shares held, once its composite scheme becomes effective. The consideration applies to TCIL shares with a face value of Rs 1 each and transfers TCIL’s resort business to SHRL on a going-concern basis.
Know Thomas Cook (India) inside out
Results, valuation, peers and who's buying, in one view.
How many SHRL shares will TCIL shareholders receive?
Eligible TCIL shareholders will receive 81 SHRL equity shares for every 100 fully paid TCIL equity shares under the stated share entitlement ratio. TCIL shares used for the ratio have a face value of Rs 1 each, while each newly issued SHRL equity share will have a face value of Rs 10 and will be credited as fully paid.
The 81-for-100 ratio is non-cash consideration for the transfer and vesting of the demerged undertaking, identified as TCIL’s resort business, into SHRL. SHRL is to issue and allot the shares without further application, act or deed by eligible shareholders, but only upon the scheme coming into effect.
The supplied scheme text does not state an eligibility date, a record date, a cash alternative or treatment for fractional holdings. It does, however, specify that the entitlement is consideration for a Part II demerger, rather than consideration for the merger of TCIL’s three wholly owned subsidiaries.
What business will move from TCIL to SHRL?
TCIL’s resort business will move to SHRL as the demerged undertaking on a going-concern basis under Part II of the six-part scheme. The filing says TCIL owns or operates multiple resorts across India, while SHRL has experience of running resort businesses and offering curated experiences to a different demographic.
The disclosed resort products include adventure holidays involving trekking, kayaking, rafting and zip lining; educational trips covering survival skills, self-defence and nature appreciation; and corporate getaways. The corporate offering includes team-building, wellness and leadership-development programmes, distinguishing the transferred resort operation from TCIL’s broader travel-related services.
Assets, employees, operations, insurance policies and proceedings relating to the resort business are among the items addressed by the scheme. Where a specified asset or liability is disputed as belonging to the demerged undertaking, the boards of TCIL and SHRL, or their board-appointed subcommittees, are to resolve the matter by mutual agreement.
Management says the transfer would let SHRL use its hospitality expertise and pursue a separate growth path as a listed entity. It also says the proposed separation is intended to give the two listed entities scope to pursue opportunities aligned with their respective industry dynamics, but the supplied pages give no revenue, profit or valuation forecast for the resort business.
Got a follow-up? Ask IRIS
How will TCIL’s other share changes work?
The proposed demerger is accompanied by a consolidation of four TCIL equity shares with a face value of Rs 1 each into one TCIL share with a face value of Rs 4. The 81 SHRL shares for every 100 TCIL shares are expressly calculated using the pre-consolidation Rs 1 TCIL shares.
Part V then proposes to reduce the face value of each TCIL equity share from Rs 4 to Rs 3. Management says this capital reduction is intended to right-size TCIL’s balance sheet and capital structure, and the filing states that no payout will result from the reduction.
The Part IV amalgamation covers TCVSL, JTSL and BTSL, which the filing describes as wholly owned TCIL subsidiaries. Since TCIL and its nominees already hold their shares, TCIL will not issue shares to itself; the subsidiaries’ shares and TCIL’s corresponding investments will instead be cancelled when the scheme takes effect.
Management says the four-for-one consolidation is expected to improve certain financial ratios and better reflect what it calls TCIL’s market value. It separately states that the Rs 4-to-Rs 3 reduction should not adversely affect creditors or TCIL’s ability to meet ordinary-course obligations because there is no payout under that step.
What approvals and creditor steps has TCIL disclosed?
TCIL disclosed that BSE Limited issued an observation or no-objection letter for the scheme on August 31, 2026, while the National Stock Exchange of India Limited (NSE) issued its letter on September 1, 2026. The applicant companies also submitted board resolutions approving the scheme dated March 20, 2026, and audited financial statements for the year ended March 31, 2026.
Those dates record procedural steps, but the supplied pages do not state that the scheme has become effective. The 81-for-100 entitlement therefore remains conditional on effectiveness under the scheme’s stated mechanism, rather than being described as an allotment already completed.
TCIL had 6 secured creditors, and it obtained consent from them representing 100% in value of its secured liabilities, leading to a dispensation from convening their meeting. By comparison, the second through fifth applicant companies had no secured creditors, so meetings for those creditor groups did not arise.
As of June 30, 2026, unsecured creditors across the five applicant companies were described as predominantly trade payables, including amounts payable on demand, to be settled in the ordinary course through working-capital cycles. The filing says no compromise or arrangement with unsecured creditors is contemplated, and that their rights are not affected by the scheme.
Conclusion
The disclosed economic term is clear: 100 eligible TCIL shares with a face value of Rs 1 each would carry an entitlement to 81 fully paid SHRL shares with a face value of Rs 10 each. The demerger sits alongside a four-for-one TCIL share consolidation, a Rs 4-to-Rs 3 face-value reduction and the cancellation of shares in three wholly owned subsidiaries.
Next, shareholders will need to watch for the scheme becoming effective and for any later disclosure of the eligibility date and fractional-entitlement treatment, neither of which appears on the supplied pages. Management’s disclosed plan is for SHRL to operate as a separate listed entity after the resort-business transfer, following the BSE letter of August 31, 2026 and the NSE letter of September 1, 2026.