










Time Technoplast Revenue and PAT Reach Records, Margins Fall
Key highlights
- Time Technoplast reported H1FY27 total income of Rs 3,689.9 crore, up 29% year on year.
- H1FY27 PAT rose 25% to Rs 262.4 crore, while EBITDA increased 17% to Rs 490.4 crore.
- Consolidated EBITDA margin declined to 13.3% in H1FY27 from 14.6% in H1FY26.
- Time Technoplast generated Rs 343.8 crore from operating activities and reduced net debt by Rs 95.9 crore in H1FY27.
powered by IRIS
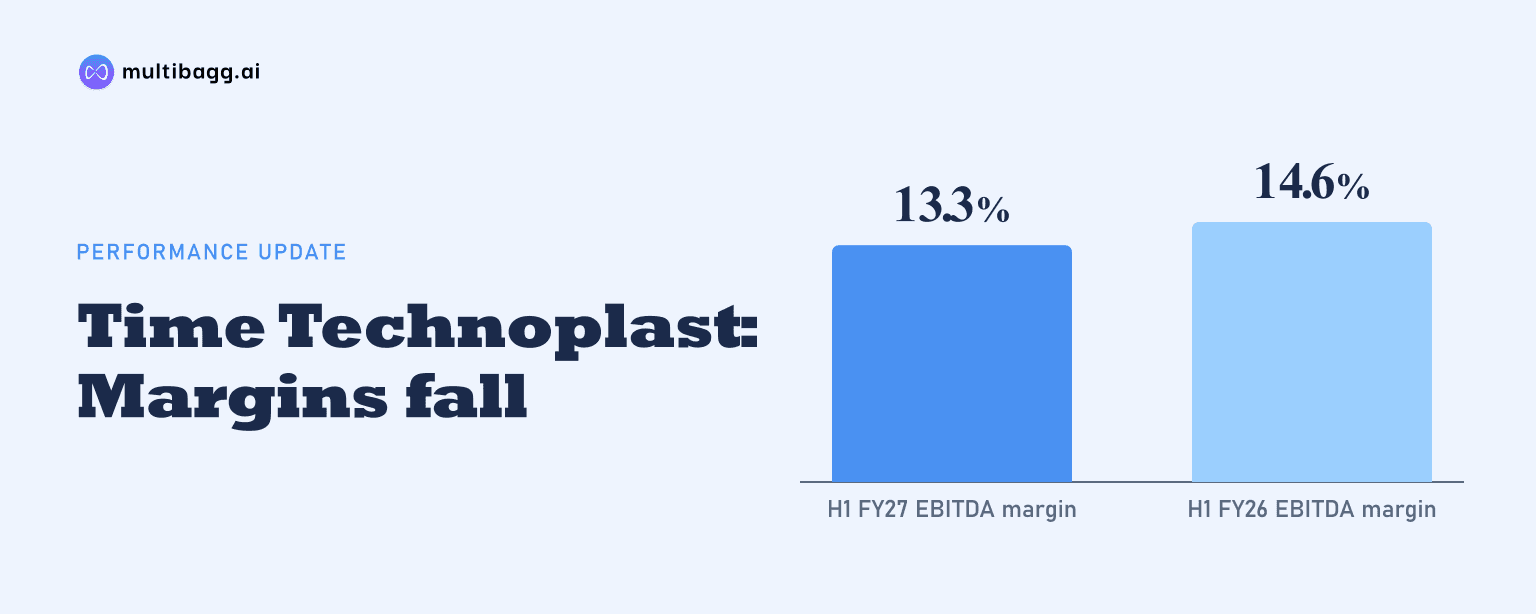
Time Technoplast Limited reported record H1FY27 total income of Rs 3,689.9 crore and profit after tax (PAT) of Rs 262.4 crore, up 29% and 25% year on year, respectively, while consolidated earnings before interest, tax, depreciation and amortisation (EBITDA) margin declined to 13.3% from 14.6%. Time Technoplast also reported its highest quarterly revenue, EBITDA and PAT in Q2FY27.
Know Time Technoplast inside out
Results, valuation, peers and who's buying, in one view.
What did Time Technoplast report for Q2FY27?
Time Technoplast reported Q2FY27 total income of Rs 1,996.1 crore, EBITDA of Rs 265 crore and PAT of Rs 146.1 crore, which the presentation describes as its highest-ever quarterly results on all three measures. Total income rose 32% from Rs 1,511.2 crore in Q2FY26, while EBITDA increased 18% from Rs 223.8 crore and PAT grew 27% from Rs 115.4 crore.
The pace of revenue growth exceeded the 13.8% consolidated volume increase in Q2FY27. India contributed 66% of revenue and overseas markets 34%; their respective revenue growth rates were 32.7% and 30.7%, while volume increased 14.1% in India and 13.1% overseas. The presentation attributes EBITDA growth relative to volume growth to pricing, product mix and operating efficiencies.
How did Time Technoplast perform in H1FY27?
Time Technoplast delivered H1FY27 total income of Rs 3,689.9 crore, EBITDA of Rs 490.4 crore and PAT of Rs 262.4 crore, all described in the presentation as all-time highs. Against H1FY26, total income grew 29% from Rs 2,865.8 crore, EBITDA rose 17% from Rs 419.6 crore, and PAT increased 25% from Rs 210.5 crore.
Consolidated volume growth was 12.9% for H1FY27, below the 28.8% revenue increase. India accounted for 65% of first-half revenue and overseas operations for 35%; India revenue rose 31.5%, compared with 23.9% overseas. India volume increased 13.3%, while overseas volume rose 12.4%, showing that both geographies contributed to the reported growth.
Why did Time Technoplast EBITDA margin fall despite higher profit?
Time Technoplast's consolidated EBITDA margin fell to 13.3% in Q2FY27 from 14.8% in Q2FY26, a decline of 150 basis points, even as EBITDA increased by Rs 41.2 crore. In H1FY27, the margin decreased to 13.3% from 14.6%, or 130 basis points, while EBITDA rose by Rs 70.8 crore. A basis point is one-hundredth of a percentage point.
The presentation does not quantify a specific cause for the reported margin contraction, nor does it provide a finance-cost line item for Q2FY27 or H1FY27. It says Time Technoplast uses mutually agreed monthly or quarterly pricing formulas with business-to-business customers and aims to maintain absolute EBITDA, while margin levels depend on key inputs. Management also says revenue growth can differ from volume growth because polymer, a key input, is a derivative of oil and gas.
At the regional level, EBITDA margins were close together in H1FY27, at 13.4% for India and 13.0% for overseas operations. The same 13.4% and 13.0% split applied in Q2FY27. PAT margin, however, was higher overseas at 8.0% in Q2FY27 and 7.8% in H1FY27, compared with 7.0% and 6.8%, respectively, in India.
Got a follow-up? Ask IRIS
Which operating measures and businesses supported Time Technoplast?
Time Technoplast generated Rs 343.8 crore from operating activities in H1FY27, spent Rs 174.1 crore on capital expenditure and reduced debt net of cash by Rs 95.9 crore. The company reported return on capital employed (ROCE) of 18.0% for H1FY27, compared with stated FY26 ROCE of 18.9%, which management said reflected the near-term effect of automation investments funded through the OIP.
Composite cylinders for compressed natural gas (CNG) recorded 28.6% growth in H1FY27. Time Technoplast also disclosed a Rs 375 crore confirmed tender for packaging products, an order book of Rs 210 crore for composite cylinders used in CNG cascades, and a Rs 195 crore order book for polyethylene (PE) pipes. These figures show exposure to packaging, gas-storage equipment and pipe products alongside the 65:35 India-overseas revenue split.
Time Technoplast completed the acquisition of a 76% stake in Systoverse Private Limited on June 10, 2026, to expand its high-density polyethylene (HDPE) pipe business in Maharashtra. The projected investment is about Rs 25 crore, including the acquisition, plant upgrading, modernisation and capacity expansion. Separately, it decided not to proceed with the proposed acquisition of Ebullient Packaging Private Limited after reviewing business conditions.
What is Time Technoplast planning to improve margins and returns?
Time Technoplast targets consolidated volume growth of 15% a year, with segment targets of 11% to 13% for packaging products, 25% to 30% for composite products, 20% to 25% for PE pipes, and 10% to 12% for other products including MOX films, auto products, turf and matting. These are management targets rather than reported results, and the company notes that revenue growth may differ with polymer input prices.
Management lists centralising moulds and machinery, product and unit consolidation, workforce optimisation, automation, solar power and long-term power purchase agreements as EBITDA-improvement measures. It also plans to reduce finance costs through lower debt using qualified institutional placement proceeds and internal cash generation, and to redeploy non-core assets toward higher-margin value-added products. The presentation does not report the amount of qualified institutional placement proceeds or a finance-cost reduction achieved in the period.
Time Technoplast identified non-core assets worth about Rs 134 crore as of March 31, 2026, of which Rs 18 crore had been disposed of in H1FY27. Management expects to monetise the remaining Rs 116 crore over the next 18 to 24 months and says this is expected to support EBITDA margin and ROCE. It aims to increase ROCE by 1.5 to 2.0 percentage points annually through automation, machinery and mould re-engineering, and working-capital optimisation.
Conclusion
Time Technoplast's Q2FY27 and H1FY27 results combine faster revenue and PAT growth with lower EBITDA margins. H1 income rose Rs 824.1 crore year on year and PAT increased Rs 51.9 crore, while the 130-basis-point margin decline meant EBITDA did not grow as quickly as revenue. India remained the larger market at 65% of H1 revenue, although overseas operations reported the higher H1 PAT margin of 7.8%.
The next points to watch are management's 15% annual consolidated volume-growth target, the planned monetisation of Rs 116 crore of non-core assets over 18 to 24 months, and regulatory approvals for the proposed merger of 75%-owned TPL Plastech Limited into Time Technoplast. The merger is proposed to take effect from April 1, 2026, subject to an order from the National Company Law Tribunal and other approvals.