










Toyam Sports auditors leave impairment effect unquantified
Key highlights
- Toyam Sports auditors said finance activities represented more than 50% of funds and did not quantify possible impairment effects.
- Consolidated loans were Rs 75.3982 crore at September 30, 2026, compared with Rs 75.5982 crore at March 31, 2026.
- Consolidated total assets increased to Rs 307.9054 crore at September 30, 2026 from Rs 298.8796 crore at March 31, 2026.
- Net operating cash flow was Rs 1.06 lakh for the half year ended September 30, 2026, versus Rs 85.37 lakh in 2025-26.
powered by IRIS
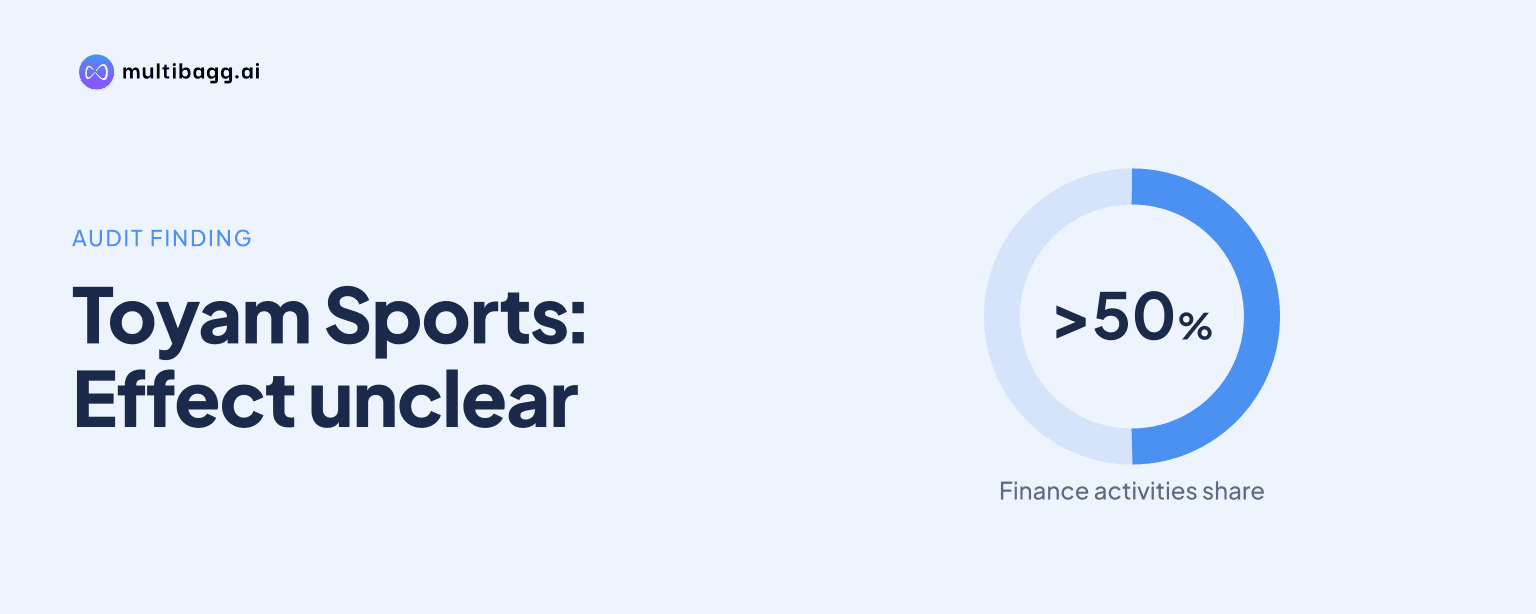
Toyam Sports Limited’s auditors could not quantify the effect on September 30, 2026 results of unrecognised impairment on financial assets, after the company did not apply expected-credit-loss provisioning or analyse certain loans and advances; finance activities accounted for more than 50% of funds.
Know Toyam Sports inside out
Results, valuation, peers and who's buying, in one view.
Why did Toyam Sports receive a qualified conclusion?
Toyam Sports received a qualified conclusion because the auditors could not determine the effect of several unresolved matters, principally impairment of financial assets and loans and advances, on the September 30, 2026 standalone results. A S G R & Co issued its limited review report on November 14, 2026 for the quarter and half year ended September 30, 2026.
The engagement was a limited review under Standard on Review Engagements 2410, rather than a full audit. The auditor said the review involved management inquiries and analytical procedures and therefore provided less assurance than an audit; subject to the qualified matters, it found nothing indicating non-compliance with disclosure requirements under Regulation 33 of the Securities and Exchange Board of India listing regulations.
The standalone annexure labels the qualification “repetitive” and says its impact was not quantified. It reported standalone total assets of Rs 295.1377 crore, total liabilities of Rs 7.1553 crore and net worth of Rs 287.9824 crore before adjustment, with the same figures shown after adjustment because no quantified adjustment was made.
What did auditors say about expected credit losses?
Auditors said Toyam Sports had not provided for impairment of financial assets using the expected credit loss, or ECL, approach required by Indian Accounting Standard 109, or Ind AS 109. The ECL method estimates the probability of loss over a financial asset’s life using past events, current conditions and forecasts that may affect credit quality.
The review linked that omission to loans and advances, noting that finance activities accounted for more than 50% of funds. Because management had not provided for or assessed the financial assets, the auditors said they could not assess or quantify the potential effect of unrecognised impairment on the September 2026 financial results.
Management said it did not consider an ECL provision necessary because it did not foresee potential credit losses. Its internal assessment considered the instruments secure and the parties creditworthy, but that was management’s assessment and not a quantified auditor adjustment; the standalone annexure reported a loss of Rs 42.02 lakh for the period.
Which loans and financial assets are involved?
The finding covers loans and advances to various companies, apart from loans for which provision had already been made. Auditors said Toyam Sports had not completed the impairment analysis required under Indian Accounting Standard 36, or Ind AS 36, despite an indication of impairment, and they could not determine materiality, recoverability or the financial-statement effect.
Management said it had not performed that analysis because no current impairment loss was anticipated on advances to various parties. It also said loans and advances identified as non-recoverable in earlier periods had already been written off, although the September 2026 filing does not identify borrowers, disclose past write-off amounts, or provide a timetable for completing the assessment.
The consolidated balance sheet shows Rs 75.3982 crore of loans at September 30, 2026, down Rs 20 lakh from Rs 75.5982 crore at March 31, 2026. This balance is not a standalone impairment schedule, but it provides context for the auditors’ concern over financial assets and advances.
Got a follow-up? Ask IRIS
What other issues did Toyam Sports auditors identify?
Auditors said Toyam Sports had substantial investments, loans and advances but had not supplied a detailed assessment of whether Section 45-IA of the Reserve Bank of India Act, 1934 applies. Without an evaluation of the Reserve Bank of India’s principal business criteria, they could not determine whether registration was required or the resulting effect, if any, on the financial statements.
The review also cited notices received from the Securities and Exchange Board of India, or SEBI, during the quarter. Pending completion of the SEBI investigation, auditors said the impact on the quarter and year ended March 31, 2026 was not ascertainable; they also referred to disclosure concerning shareholding and the freezing of some shares by the Enforcement Directorate.
Management said it was cooperating with SEBI and had responded to the notices. It added that, to its knowledge, there were no other proceedings related to the share freeze, but said any financial impact could not be determined while the SEBI investigation remains underway.
Auditors further said Toyam Sports had not considered the realisable economic benefits from merchandising agreements over the following 12 months. Management replied that the counterparty had agreed to pay interest under the merchandise agreement, which it described as the economic benefit derived from advances provided for merchandise.
How did Toyam Sports' financial position change by September 2026?
Toyam Sports reported consolidated total assets of Rs 307.9054 crore at September 30, 2026, up from Rs 298.8796 crore at March 31, 2026. Total equity fell to Rs 272.5092 crore from Rs 276.9932 crore, while current liabilities rose to Rs 35.3962 crore from Rs 21.8864 crore.
The increase in current liabilities included borrowings of Rs 5.9554 crore at September 30, 2026, compared with nil at March 31, 2026. Other current assets increased to Rs 60.7001 crore from Rs 48.9001 crore, while goodwill on consolidation was unchanged at Rs 163.6487 crore.
Net cash from operating activities was Rs 1.06 lakh for the half year ended September 30, 2026, versus Rs 85.37 lakh in 2025-26. Closing cash and cash equivalents rose to Rs 10.26 lakh from Rs 9.20 lakh, while management said losses in the LLC T20 Cricket League had created a funding shortage that prevented payment of tax deducted at source, professional tax and other statutory liabilities.
Conclusion
Toyam Sports’ September 2026 limited review leaves the measurement of potential impairment unresolved. Auditors could not quantify whether its financial assets, loans and advances require provisions, even though finance activities represented more than 50% of funds and consolidated loans were Rs 75.3982 crore at the September 2026 balance-sheet date.
The next disclosures to watch are management’s ECL and Ind AS 36 assessments, its evaluation of possible registration under Section 45-IA, and the outcome of the SEBI investigation. Auditors also identified the next 12 months as the period in which economic benefits under merchandising agreements may need to be realised, while management disclosed unpaid statutory liabilities linked to the LLC T20 Cricket League funding shortage.