










Triveni Turbine Q2 FY27 margin falls to 17.5% amid costs
Key highlights
- Triveni Turbine’s Q2 FY27 EBITDA margin fell to 17.5% from 26.3% in Q2 FY26.
- Q2 FY27 EBITDA declined 35.4% year on year to Rs 85.8 crore while revenue fell 3.0% to Rs 491 crore.
- Q2 FY27 order booking reached a record Rs 764.4 crore, up 17.2% year on year.
- The H1 FY27 closing order book was Rs 2,452.9 crore, with aftermarket orders up 105.4% to Rs 639 crore.
powered by IRIS
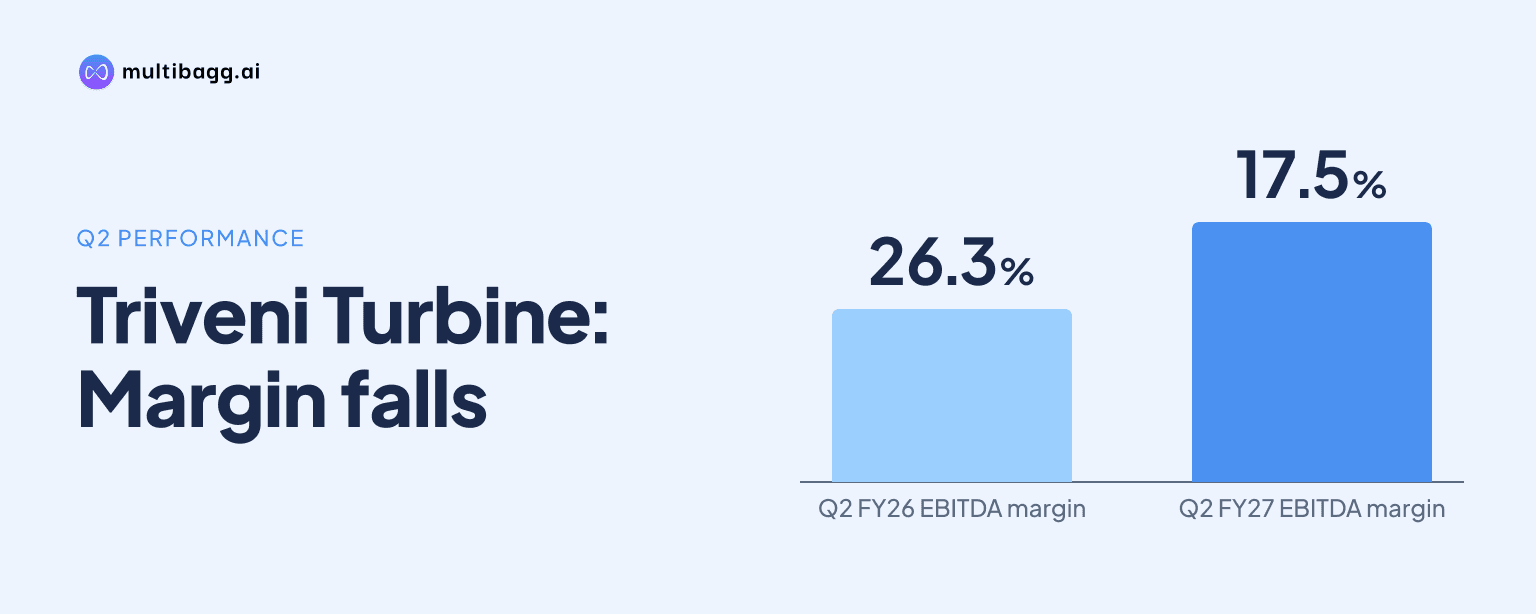
Triveni Turbine Limited reported an earnings before interest, tax, depreciation and amortisation (EBITDA) margin of 17.5% in the second quarter of financial year 2027 (Q2 FY27), down from 26.3% a year earlier, as deliveries of older lower-mix orders, a strategic order and higher input and logistics costs reduced EBITDA to Rs 85.8 crore.
Know Triveni Turbine inside out
Results, valuation, peers and who's buying, in one view.
Why did Triveni Turbine’s Q2 FY27 EBITDA margin decline?
Triveni Turbine’s Q2 FY27 margin decline resulted from the product mix on deliveries tied to orders won around a year earlier, a strategic order under execution, and higher input and logistics costs, according to management. These factors reduced EBITDA to Rs 85.8 crore in Q2 FY27 from Rs 133 crore in Q2 FY26, while the margin fell 8.8 percentage points to 17.5%.
Management said current deliveries largely reflected older orders rather than newer order intake, which reached a quarterly record of Rs 764.4 crore in Q2 FY27. Management expects the cost and mix pressures to ease in coming quarters, although the presentation does not quantify the timing of an easing or a future EBITDA-margin level.
How much did Triveni Turbine’s profit fall in Q2 FY27?
Triveni Turbine’s Q2 FY27 profit deterioration was sharper than its revenue decline: revenue fell 3.0% year on year to Rs 491 crore, EBITDA declined 35.4%, and profit after tax (PAT) fell 41.7% to Rs 53.3 crore. The same pattern extended into the first half of FY27 (H1 FY27), when revenue rose 6.4% but EBITDA and PAT both declined from H1 FY26.
For H1 FY27, EBITDA margin was 17.7%, compared with 26.1% in H1 FY26, and EBITDA decreased 27.6% to Rs 165.5 crore. PAT margin fell to 11.2% from 17.8%, with PAT down 32.9% to Rs 104.4 crore, showing that the margin pressure extended beyond the Q2 reporting period.
Can Triveni Turbine’s record orders support later revenue?
Triveni Turbine’s record Q2 FY27 order booking and Rs 2,452.9 crore closing order book provide a larger base for future execution, but they did not prevent lower Q2 revenue and margin. Quarterly order booking rose 17.2% year on year to Rs 764.4 crore, whereas Q2 revenue was Rs 491 crore, down from Rs 506.2 crore a year earlier.
For H1 FY27, order booking increased 12.2% to Rs 1,332.7 crore from Rs 1,187.8 crore in H1 FY26, while the closing order book rose 10.5% from Rs 2,219.7 crore to Rs 2,452.9 crore. The contrast with the 17.5% Q2 margin reflects the timing issue identified by management: current results are shaped by prior orders, while recently booked orders remain to be converted into delivery and revenue.
Got a follow-up? Ask IRIS
Which order segments are driving Triveni Turbine’s backlog?
Triveni Turbine’s Q2 FY27 order intake was led by exports and product business, with export orders rising 49.8% year on year and representing 48.1% of Rs 764.4 crore of quarterly booking. Product order booking increased 32.5% to Rs 601 crore, even as management said lower export revenue offset 51.8% domestic revenue growth during the quarter.
The H1 FY27 mix differed from the quarter because exports represented 56% of Rs 1,332.7 crore of order booking and aftermarket represented 29%. Closing aftermarket orders more than doubled, rising 105.4% year on year to Rs 639 crore, while export orders accounted for 59.2% of the Rs 2,452.9 crore closing order book.
Management linked the higher aftermarket backlog to contract wins in thermal renewables, including waste heat recovery and biomass, as well as combined-cycle and utility applications. It also reported Q2 FY27 inroads in combined-cycle power plants and secured boiler feedwater pump packages with drive turbines for an ultra-supercritical project in India.
What is Triveni Turbine doing to improve execution in H2 FY27?
Triveni Turbine is strengthening supply-chain and operating processes as it prepares to execute its Rs 2,452.9 crore order book in the second half of FY27 (H2 FY27). Measures disclosed include artificial-intelligence-driven predictive maintenance, localised global services, digitalised hydro testing for turbine casings, and advanced laser-hardening processes.
Management said its enquiry pipeline spans biomass, waste-to-energy, utility, geothermal and process co-generation internationally, while domestic enquiries cover steel, cement, sugar and distillery applications. It expects improved H2 FY27 performance based on its geographical presence, segment coverage, order book and execution capabilities, but did not provide a revenue, EBITDA-margin or profit target for the half year.
Conclusion
Triveni Turbine entered H2 FY27 with record quarterly orders of Rs 764.4 crore and a closing order book of Rs 2,452.9 crore, yet its Q2 results show that a growing backlog does not immediately determine reported profitability. Revenue fell 3.0%, while older lower-mix orders, a strategic project and higher costs pushed EBITDA margin down to 17.5%.
The next measure to watch is whether H1 FY27 order intake of Rs 1,332.7 crore, including a 105.4% increase in closing aftermarket orders to Rs 639 crore, converts into the improved H2 FY27 performance management expects. The presentation also leaves unresolved the pace at which input and logistics costs ease and newer orders replace the legacy delivery mix in reported revenue.