










Venus plans phased spooling expansion, nuclear margin 35%-40%
Key highlights
- Venus received an approximately Rs 29 crore data-centre spooling order from a Rs 185 crore letter of intent.
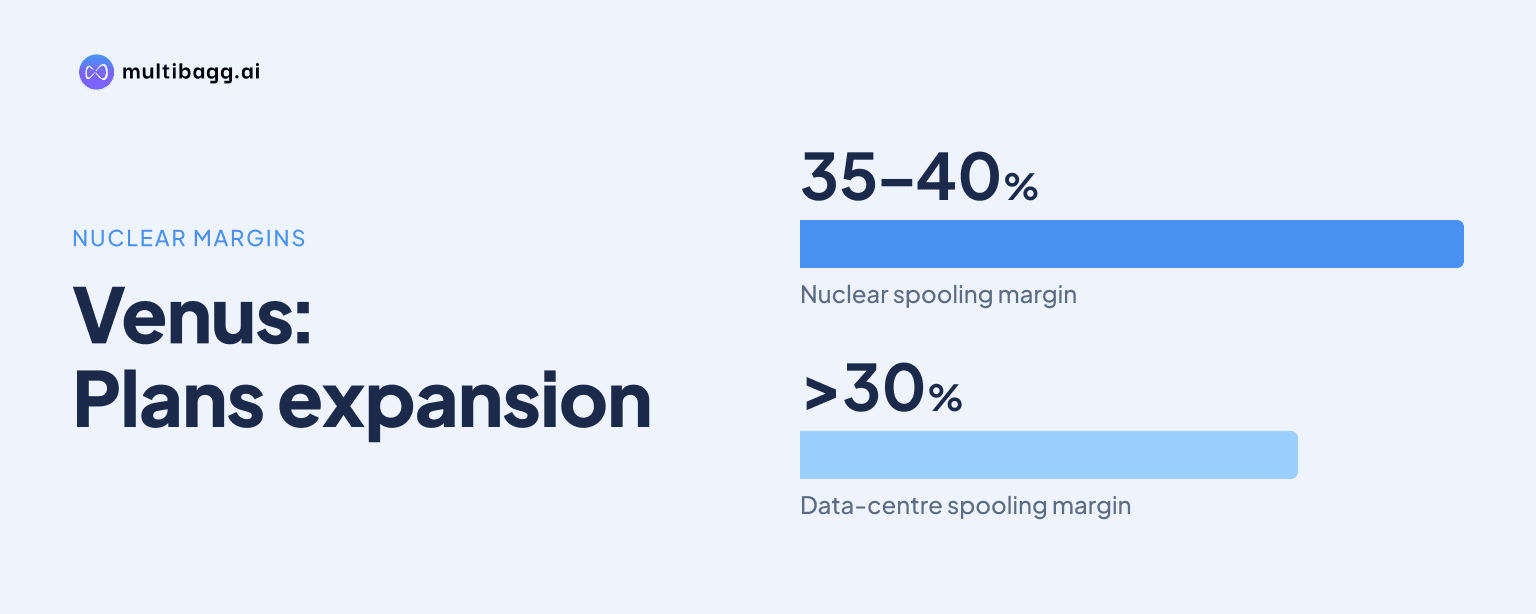
- Management expects data-centre spooling EBITDA margins above 30% and nuclear spooling margins of more than 35%-40%.
- Venus is contemplating about Rs 70 crore of data-centre spooling revenue in H2 FY27, versus zero in H1 FY27.
- Q2 FY27 EBITDA margin was 14.3%, compared with 16.3% in Q2 FY26, with freight and fuel costs affecting profitability.
powered by IRIS
Venus Pipes and Tubes Limited said on November 5, 2026, that it will take spooling from data centres to power, oil and gas, and nuclear in phases, with management expecting nuclear EBITDA margins of more than 35%-40%; its first firm data-centre order is about Rs 29 crore.
Know Venus Pipes & Tubes inside out
Results, valuation, peers and who's buying, in one view.
What is Venus's spooling expansion plan?
Venus's plan is to establish spooling in data centres first and then enter power, oil and gas, and nuclear in that order. The company commenced spooling operations ahead of its original timeline to prepare for conversion of a data-centre customer's letter of intent, which has produced a firm order of approximately Rs 29 crore.
The remaining data-centre letter of intent is expected to convert in phases as the customer finalises project designs. Management described the original letter of intent as Rs 185 crore, while citing an unconverted balance of Rs 156 crore in prepared remarks and Rs 155 crore later in the call. Venus has started executing the firm order rather than waiting for conversion of the entire letter of intent.
Venus is pursuing spooling as part of forward integration beyond its core pipes and tubes business. Its earlier integration steps include cutting, while management also said it is developing additional stainless-steel component products from existing pipe and tube output. The company said these products can improve realisation, but gave no revenue target for the planned component categories.
Which sectors will Venus target and what margins does it expect?
Venus will target data centres, power, oil and gas, and nuclear sequentially, with management assigning different EBITDA, or earnings before interest, tax, depreciation and amortisation, margin expectations to each sector. The company did not disclose signed spooling orders in power, oil and gas, or nuclear, so these figures are management projections rather than reported segment margins.
Nuclear has the highest margin range cited by management, at more than 35%-40%, while oil and gas has the lowest, at 20%-25%. Data-centre work and power work are each expected to generate around or above 30%, according to management. The comparison reflects anticipated sector economics, not a single margin target for Venus.
How much could spooling contribute in H2 FY27?
Venus said it is contemplating about Rs 70 crore of data-centre spooling revenue in H2 FY27, compared with zero in H1 FY27, at an EBITDA margin exceeding 30%. The estimate depends on phased capacity ramp-up and execution of received and subsequently converted data-centre orders, because management said the full data-centre capacity will come live in phases.
Fittings are the other value-added product expected to affect the second half. Venus reported fitting revenue of about Rs 9 crore in H1 FY27 and said it expects Rs 40 crore to Rs 50 crore in H2 FY27, with EBITDA margins exceeding 17%-18%. Management said fittings would receive the benefit of a full second half, unlike the limited H1 contribution.
Pipes remained the main revenue source in Q2 FY27. Seamless pipes represented 54.7% of quarterly revenue, welded pipes 37.6%, fittings 2.5%, and other products 5.2%. Revenue from operations rose 23.9% year on year to Rs 361.1 crore from Rs 291.5 crore, with management attributing about 12% growth to prices, about 8% to quantity, and part of the balance to fittings.
Got a follow-up? Ask IRIS
What changed in Venus's margins before spooling scales up?
Venus's reported Q2 FY27 EBITDA margin declined to 14.3% from 16.3% in Q2 FY26, despite EBITDA increasing 9.1% to Rs 51.7 crore from Rs 47.4 crore. Management said a roughly 12% year-on-year increase in selling prices reduced the percentage margin on a higher revenue base, and that higher export freight and fuel costs also affected profitability.
Management said the Q2 FY27 EBITDA margin would have been about 15.5% without the price effect and above 16% after excluding freight and fuel costs as well. Pipe EBITDA excluding fittings was Rs 62 per kg in Q2 FY27, down from about Rs 64 per kg a year earlier, with freight identified as the main cause of the Rs 2 per kg reduction.
Exports rose to Rs 147.2 crore in Q2 FY27 from Rs 115.6 crore in Q2 FY26 and accounted for 41% of revenue. That growth increased exposure to export freight costs during the quarter. Management said freight had started declining in the days before the November 5 call and that a continued reduction could improve pipe EBITDA per kg by Rs 2 to Rs 3.
When will Venus complete the data-centre opportunity?
Venus expects the data-centre letter of intent to be completed over the next 12 months and by Q2 FY28, with orders broadly divided over four quarters. Management said it expected some order flow in Q4 FY27, subject to the customer completing designs that determine when individual orders are issued.
Management also gave a later execution reference of before December 2027 for the entire data-centre opportunity. The two dates were not reconciled during the call. Venus's order book exceeded Rs 670 crore, including the approximately Rs 30 crore data-centre order, while management said the Rs 640 crore pipe order book had an execution period of four to five months.
Venus retained its FY27 target of around 15% pipe-volume growth after recording about 8% growth in H1 FY27. Management cited demand in domestic and export markets, expected growth in welded and seamless pipes, and output from the second seamless pipe facility that began operating in May 2026. It separately identified fittings and spooling as additions to, rather than replacements for, pipe growth.
Conclusion
Venus is using a Rs 29 crore data-centre order to begin a phased shift toward higher-processing products alongside seamless and welded pipes. Management's disclosed spooling margin ranges vary by end market, from 20%-25% for oil and gas to more than 35%-40% for nuclear, while Q2 FY27's reported EBITDA margin was 14.3% amid freight and fuel pressure.
The next disclosures to watch are further conversion of the Rs 155 crore to Rs 156 crore unconverted data-centre letter of intent, progress toward the contemplated Rs 70 crore of H2 FY27 spooling revenue, and phased capacity commissioning. Management's stated milestones are completion by Q2 FY28 and, separately, execution before December 2027, leaving the timing relationship between those dates unresolved.