










VIP Industries Posts 15% Q2 FY27 Growth After Four Declines
Key highlights
- VIP Industries reported Q2 FY27 income from operations of Rs 468 crore, up 15% year on year from Rs 406 crore.
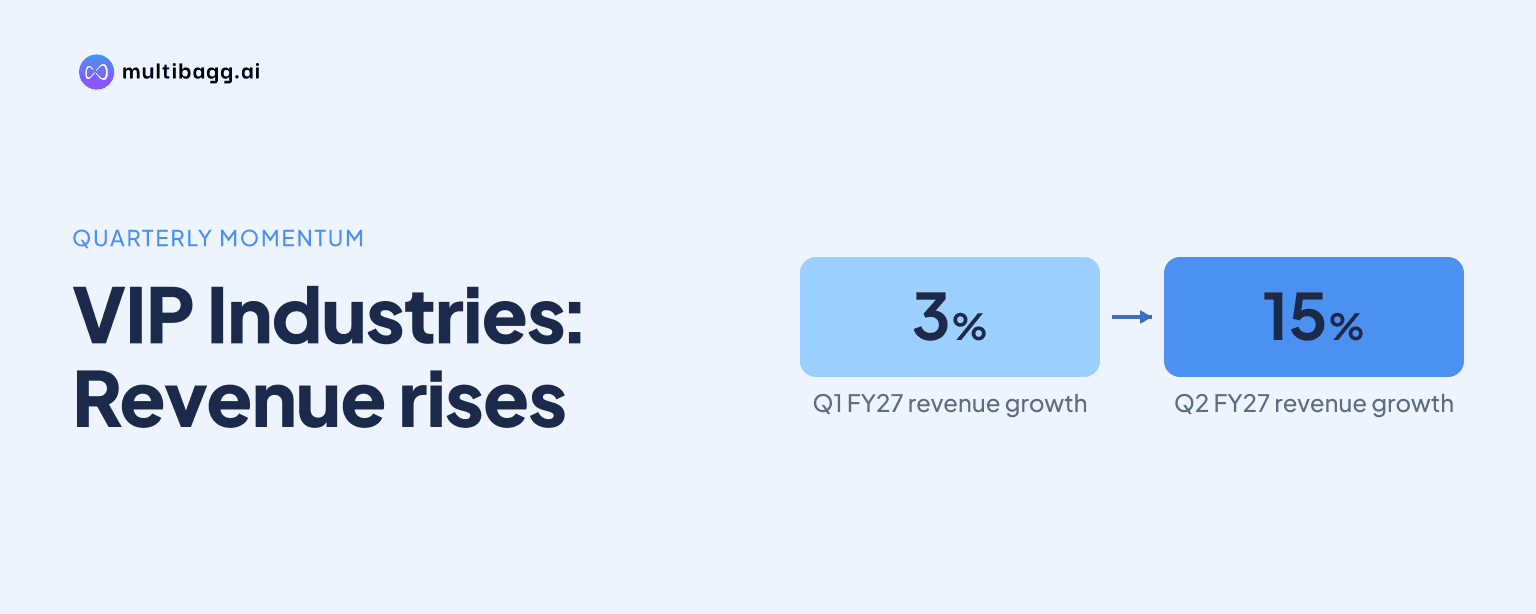
- Revenue growth moved from four quarterly declines in 2026 to 3% in Q1 FY27 and 15% in Q2 FY27.
- More than 50 ranges launched in H1 FY27 generated about 45% of hard luggage and backpack sales.
- VIP Industries' Q2 FY27 EBITDA loss narrowed to Rs 27 crore from Rs 96 crore in Q2 FY26.
powered by IRIS
V.I.P. INDUSTRIES LIMITED reported 15% year-on-year revenue growth in the second quarter of financial year 2027 (Q2 FY27), with income from operations of Rs 468 crore for the quarter ended September 30, 2026, after four quarterly declines shown for 2026. VIP Industries said more than 50 new ranges launched in H1 FY27 contributed about 45% of hard luggage and backpack sales.
Know V I P Industries inside out
Results, valuation, peers and who's buying, in one view.
How did VIP Industries return to revenue growth?
VIP Industries returned to double-digit growth with Q2 FY27 income from operations of Rs 468 crore, compared with Rs 406 crore in Q2 FY26. The 15% year-on-year increase accelerated from 3% growth in Q1 FY27, making Q2 FY27 the second consecutive quarter of growth. The company described the rate as its highest revenue growth in more than two years.
The recovery followed four consecutive year-on-year declines in the quarters shown for 2026: 12% in Q1 2026, 25% in Q2 2026, 9% in Q3 2026 and 12% in Q4 2026. The Q2 FY27 growth comparison was against Q2 FY26, not the immediately preceding quarter, as revenue was Rs 578 crore in Q1 FY27 and Rs 468 crore in Q2 FY27.
How did Q2 FY27 compare with VIP Industries' previous quarters?
Q2 FY27 delivered the fastest year-on-year growth rate in the six-quarter series presented by VIP Industries, following four declines in 2026 and 3% growth in Q1 FY27. The shift from a 25% decline in Q2 2026 to 15% growth in Q2 FY27 was a 40-percentage-point change in the reported growth rate, while revenue rose by Rs 62 crore from Rs 406 crore.
VIP Industries reported double-digit growth across its core channels in Q2 FY27, but did not disclose channel-level sales or growth figures. The presentation identifies the sequence as restarting growth, reaching double-digit growth and sustaining double-digit growth after a new managing director was appointed at the end of September 2025 and a senior team was onboarded by Q4 2026 and Q1 2027.
What drove VIP Industries' Q2 FY27 sales recovery?
VIP Industries attributed Q2 FY27 growth to new consumer-led products, with more than 50 ranges launched in H1 FY27 contributing about 45% of hard luggage and backpack sales. The company listed front-opening laptop access, silent wheels, suspension wheels, coffee and mobile holders, a 90:10 packing split and vanity-case sets among the product features.
The new launches covered VIP, Skybags and Aristocrat, the three brands cited by the company in its Q2 FY27 release. Its price-point architecture places Savoy Paris in premium, VIP and Skybags in mid-premium, and Aristocrat and VIP Alfa in mass, although the presentation provides no revenue split by brand or price segment.
VIP Industries also said outlets billed for VIP and Skybags doubled year on year, with both brands returning to growth in Q2 FY27. The company cited a national campaign across television, over-the-top streaming services and airports, but did not disclose outlet numbers, campaign spending or the sales contribution of those activities.
Got a follow-up? Ask IRIS
How is premiumisation affecting VIP Industries' margins?
VIP Industries is using premium launches and portfolio pricing to move up the price ladder while seeking to improve gross margin. Savoy Paris was soft-launched in September 2026 as the premium brand, while Aristocrat received premium, feature-rich launches; the company reported strong initial traction without providing sales or distribution data.
Gross margin excluding inventory provisions rose sequentially to 44% in Q2 FY27 from 39% in Q1 FY27, despite what management described as unprecedented raw-material inflation. Reported gross margin was 47% in Q2 FY27 and 41% in Q1 FY27, and the presentation identified price increases, cost-out actions and premium sales mix as the relevant mechanisms.
The margin improvement did not yet produce positive earnings before interest, tax, depreciation and amortisation, or EBITDA. VIP Industries reported an EBITDA loss of Rs 27 crore, equal to 6% of revenue, in Q2 FY27, compared with a Rs 96 crore loss, or 24% of revenue, in Q2 FY26.
What is VIP Industries targeting after Q2 FY27?
VIP Industries is targeting sustained double-digit revenue growth after reporting 3% growth in Q1 FY27 and 15% in Q2 FY27. Management said it plans to build on channel and new-launch momentum, while maintaining a stated path towards break-even and profitability rather than providing a Q3 FY27 or full-year revenue forecast.
For Q3 and H2 FY27, management listed margin expansion as a priority after gross margin excluding inventory provisions increased from 39% to 44% between Q1 FY27 and Q2 FY27. The disclosed levers are pricing, cost-out actions, fixed-cost savings and premiumisation, while the presentation does not give a gross-margin target, break-even date or projected EBITDA figure.
Conclusion
VIP Industries' Q2 FY27 revenue growth of 15% to Rs 468 crore marks a reversal from the four quarterly contractions reported during 2026, including the 25% decline in Q2 2026. The company links the recovery to more than 50 new product ranges, which accounted for about 45% of hard luggage and backpack sales, alongside renewed growth at VIP and Skybags.
The next results will test management's plan to sustain double-digit growth in Q3 and H2 FY27 while expanding margins through pricing, cost-out actions, fixed-cost savings and premiumisation. The remaining operating measure to watch is whether those actions further reduce the Rs 27 crore EBITDA loss reported in Q2 FY27 on the stated route to break-even.