










VIP Industries lifts Q2 FY27 gross margin to 44% ex-provisions
Key highlights
- VIP's gross margin excluding inventory provisions rose to 44% in Q2 FY27 from 39% in Q1 FY27.
- VIP reported gross margin of 47% in Q2 FY27, compared with 31% in Q2 2026.
- VIP's Q2 FY27 EBITDA was negative Rs 27 crore, versus negative Rs 96 crore a year earlier.
- VIP reported 15% growth in Q2 FY27 after 3% growth in Q1 FY27.
powered by IRIS
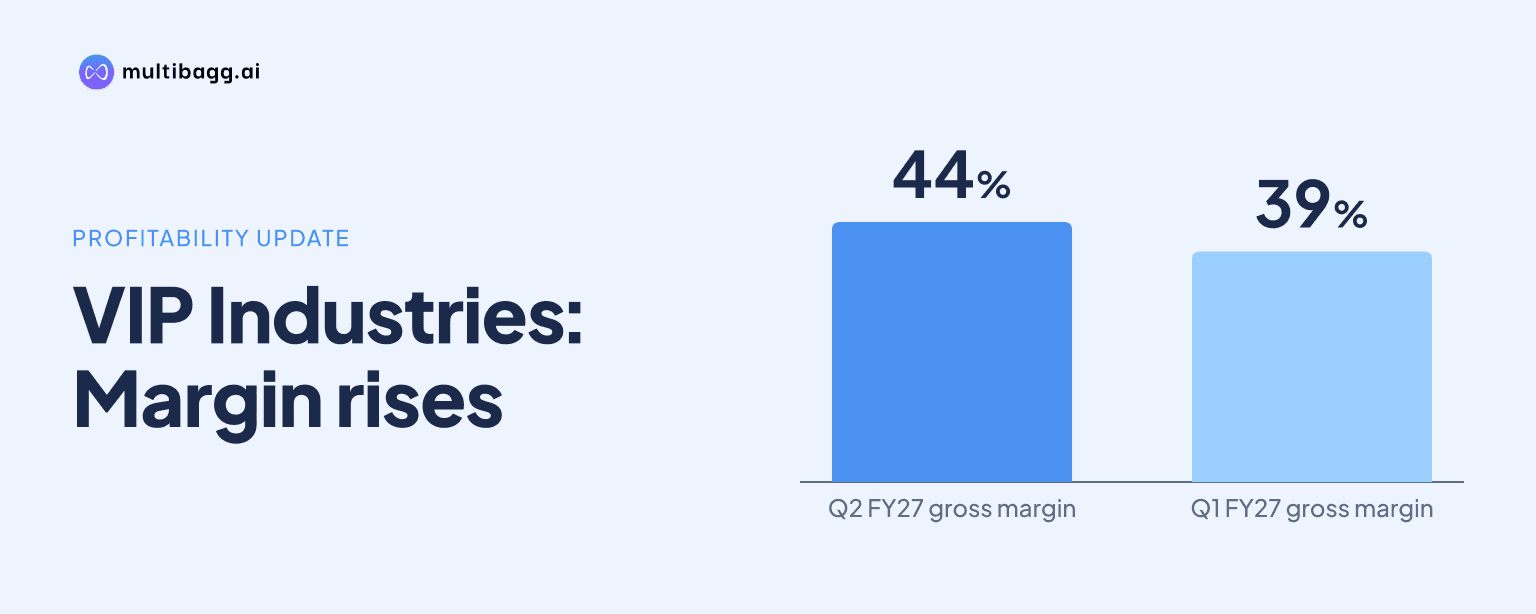
VIP Industries lifted gross margin excluding inventory provisions to 44% in Q2 FY27 from 39% in Q1 FY27, while reported gross margin reached 47%. The presentation lists price increases, cost-outs and premium mix as recovery measures despite war-related raw-material inflation; earnings before interest, tax, depreciation and amortisation (EBITDA) remained negative Rs 27 crore, or negative 6%.
Know V I P Industries inside out
Results, valuation, peers and who's buying, in one view.
How did VIP's Q2 FY27 gross margin change?
VIP's gross margin excluding inventory provisions rose by 5 percentage points sequentially to 44% in Q2 FY27 from 39% in Q1 FY27. Reported gross margin increased by 6 percentage points to 47% from 41% over the same period, leaving a 3-percentage-point difference between the two measures in Q2.
The Q2 result was also higher than the corresponding prior-year quarter in the disclosed series. Reported gross margin was 31% in Q2 2026 and 47% in Q2 2027, an increase of 16 percentage points. It had reached a low of 29% in Q3 2026 before recovering to 37% in Q4 2026, 41% in Q1 2027 and 47% in Q2 2027.
The latest two quarters are the only periods in the presentation with both measures disclosed. The excluding-provisions measure improved from 39% to 44%, while reported margin moved from 41% to 47%; the gap widened from 2 percentage points in Q1 2027 to 3 percentage points in Q2 2027.
Why did VIP's margins recover despite raw-material inflation?
VIP lists price increases, cost-outs and premium mix as the factors supporting gross-margin recovery, while noting that war-related raw-material inflation affected margins. These measures accompanied an 18-percentage-point increase in reported gross margin from 29% in Q3 2026 to 47% in Q2 2027. The presentation does not quantify the contribution from each action.
The disclosed portfolio activity provides context for the premium-mix plan. VIP and Skybags returned to growth in Q2 2027, and outlets billed for those brands rose 2x year on year. VIP also conducted a national campaign across television, over-the-top platforms and airports, while Savoy Paris had a soft launch in September 2026 and, according to the presentation, showed strong initial traction.
Growth accelerated during the margin recovery, although the disclosed quarterly amount declined sequentially. Growth rose from 3% in Q1 2027 to 15% in Q2 2027, the second straight quarter of growth after four declining quarters in 2026. The quarterly amount was Rs 578 crore in Q1 2027 and Rs 468 crore in Q2 2027, versus Rs 406 crore in Q2 2026; the presentation does not explain the sequential change.
Got a follow-up? Ask IRIS
Why was VIP's EBITDA still negative in Q2 FY27?
VIP reported EBITDA of negative Rs 27 crore, or negative 6%, in Q2 2027 despite reported gross margin of 47%. This was worse than negative Rs 7 crore, or negative 1%, in Q1 2027. The figures show that the gross-margin improvement had not translated into positive EBITDA in the latest quarter.
The year-on-year comparison was more favourable. EBITDA was negative Rs 96 crore, or negative 24%, in Q2 2026, compared with negative Rs 27 crore and negative 6% in Q2 2027. The reported EBITDA loss was therefore Rs 69 crore lower and the EBITDA margin was 18 percentage points less negative, alongside a rise in reported gross margin from 31% to 47%.
The six-quarter series also shows that the EBITDA recovery was uneven. EBITDA was positive Rs 29 crore, or 5%, in Q1 2026, then negative Rs 96 crore in Q2 2026, negative Rs 73 crore in Q3 2026 and negative Rs 78 crore in Q4 2026. It improved to negative Rs 7 crore in Q1 2027 before declining to negative Rs 27 crore in Q2 2027.
What is VIP planning for H2 FY27?
VIP's H2 FY27 priorities are to sustain double-digit growth, expand margins and premiumise the portfolio. Management says margin actions will include continued pricing and cost-outs, with fixed-cost savings starting to flow. Its premiumisation objective is to increase average selling prices (ASPs) across the portfolio.
The growth plan is linked to channel and new-launch momentum. Q2 2027 growth of 15% followed 3% growth in Q1 2027, after declines of 12% in Q1 2026, 25% in Q2 2026, 9% in Q3 2026 and 12% in Q4 2026. Savoy Paris was soft-launched in September 2026, while VIP and Skybags outlets billed were 2x higher year on year.
The presentation also records execution milestones before the return to growth. A new managing director was appointed at the end of September 2025, a transaction was completed at the end of December 2025, and the senior team was onboarded by Q4 2026 and Q1 2027. The slides do not disclose a numerical gross-margin or EBITDA target for H2 FY27.
Conclusion
VIP's Q2 FY27 figures show that gross-margin recovery is ahead of EBITDA recovery. Gross margin excluding inventory provisions reached 44%, up from 39% in Q1 FY27, and reported gross margin was 47%, compared with 31% in Q2 2026. EBITDA nevertheless remained negative Rs 27 crore, indicating that the improvement in pricing, cost-outs and premium mix had not yet produced positive quarterly EBITDA.
The next disclosed test is whether VIP can sustain double-digit growth through Q3 and H2 FY27 while fixed-cost savings begin to flow. The next quarterly update can be assessed against Q2 2027's 15% growth, 47% reported gross margin and negative 6% EBITDA margin, as well as management's plan to raise ASPs across the portfolio.