










V.I.P. Industries Q2 FY27 Results to Test Revenue Recovery
Key highlights
- V.I.P. Industries reported Q1 FY27 consolidated revenue of ₹578.36 crore, up 3% year on year.
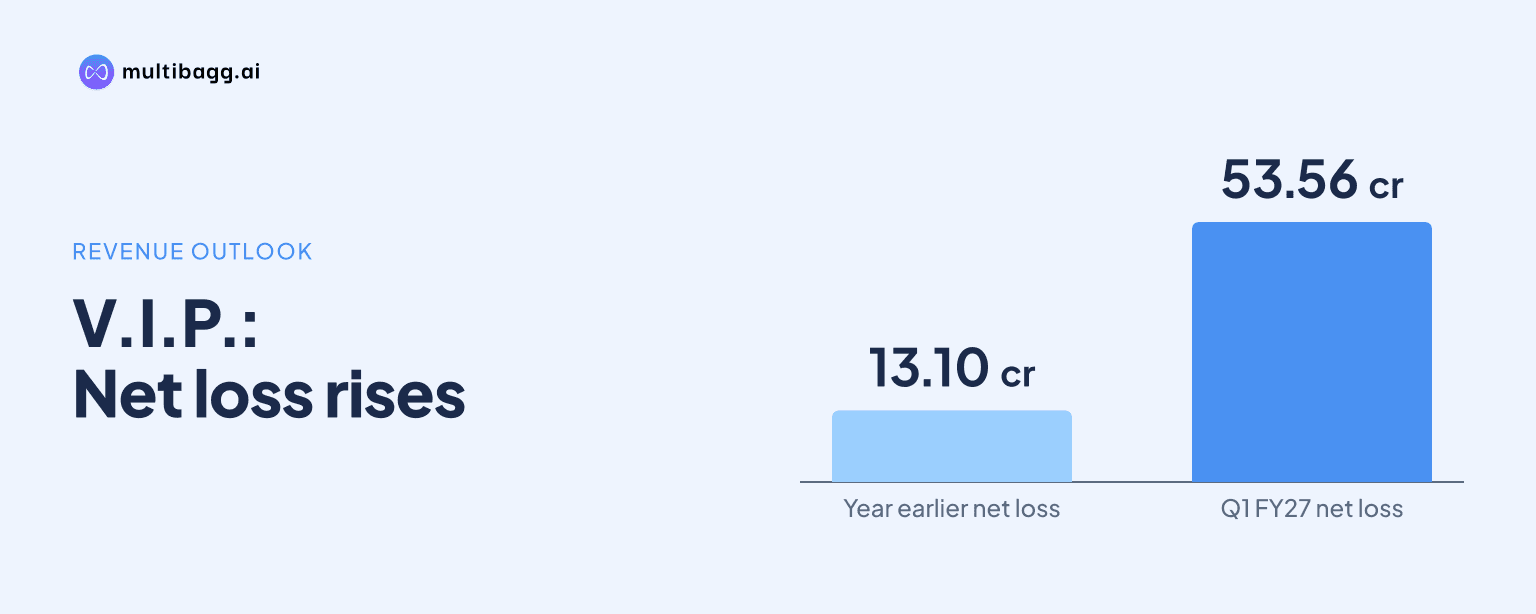
- V.I.P. Industries posted a consolidated net loss of ₹53.56 crore in Q1 FY27 versus a ₹13.10 crore loss a year earlier.
- Market estimates place Q2 FY27 revenue at ₹580 crore to ₹600 crore, implying 2% to 4% year-on-year growth.
- V.I.P. Industries has board approval to raise up to ₹500 crore in FY27 through equity, debt or convertible securities.
powered by IRIS
V.I.P. Industries Limited’s Q2 FY27 results, scheduled for board consideration on November 12, 2026, will test whether its Q1 revenue recovery can hold after consolidated revenue rose 3% year on year to ₹578.36 crore while net loss widened to ₹53.56 crore. The update matters because the luggage maker is seeking to restore growth and improve a pressured balance sheet.
Know V I P Industries inside out
Results, valuation, peers and who's buying, in one view.
When will V.I.P. Industries Limited report Q2 FY27 results?
V.I.P. Industries Limited will consider and approve unaudited standalone and consolidated financial results for the quarter and half year ended September 30, 2026, at its board meeting on November 12, 2026. The company had issued the meeting intimation on November 6, confirming that the agenda covers Q2 FY27 and first-half results.
The company also closed its trading window from October 1 to November 14, 2026, under insider-trading compliance requirements. The announcement does not include management guidance for the quarter. As a result, market attention will be focused on reported sales, operating profitability, net loss and any comments that accompany the results.
The Q2 release follows a Q1 FY27 performance in which revenue growth returned after a prolonged weak period. But the sales improvement was not accompanied by a return to net profitability, making the September-quarter margin outcome important for investors assessing the recovery.
What does V.I.P. Industries Limited’s Q1 FY27 performance show?
V.I.P. Industries reported consolidated revenue from operations of ₹578.36 crore in Q1 FY27, up 3% year on year and 33% sequentially. The company’s Q1 investor presentation reported EBITDA of ₹29 crore and an EBITDA margin of 5% for the quarter.
However, the company recorded a consolidated net loss of ₹53.56 crore in the June 2026 quarter, compared with a net loss of ₹13.10 crore in the year-earlier quarter. This means that the return to revenue growth has yet to translate into a recovery in bottom-line performance.
The June-quarter sales base was ₹561 crore in the available quarterly data, while revenue had fallen to ₹406 crore in September 2025, ₹454 crore in December 2025 and ₹436 crore in March 2026. The Q1 FY27 rebound therefore marked a break from four consecutive quarters of year-on-year revenue declines shown in the company’s investor material.
V.I.P. Industries also said its Q1 revenue performance was supported by more than 80 new product launches. The company has not published an earnings-call transcript for that quarter, so the available information does not provide management guidance on the pace of sales or profit recovery for the rest of FY27.
What are the market expectations for V.I.P. Industries Limited’s Q2 FY27 results?
Available market estimates place V.I.P. Industries’ Q2 FY27 revenue at about ₹580 crore to ₹600 crore, representing growth of roughly 2% to 4% year on year. These are estimates rather than company guidance, and they broadly imply that the Q1 sales run rate is sustained into the September quarter.
The same estimates indicate an EBITDA margin of around 12% to 13% and net profit of approximately ₹20 crore to ₹30 crore. These figures should be treated as expectations, not reported results. V.I.P. Industries has not disclosed Q2 FY27 financial figures ahead of the board meeting.
A revenue outcome of ₹590 crore or above, along with an EBITDA margin of at least 13%, has been identified in market commentary as a stronger result. Any forward outlook from management would be relevant because the company has not given formal FY27 growth guidance in the material provided.
Got a follow-up? Ask IRIS
Why do margins and fundraising matter for V.I.P. Industries Limited?
Margins remain central because revenue expansion alone did not prevent a Q1 net loss. The company operates in a competitive consumer goods segment, and its recent financial record shows a sharp deterioration in profitability through FY26. Operating margins in the available quarterly data were negative in the September 2025, December 2025, March 2026 and June 2026 periods.
The estimated Q2 EBITDA margin of 12% to 13%, if achieved, would represent a significant improvement from the 5% EBITDA margin reported in the Q1 FY27 investor presentation. The reported result will show whether this expectation is supported by operating performance or whether costs and competitive conditions continue to constrain profitability.
The board has also approved fundraising of up to ₹500 crore in FY27 through equity, debt or convertible securities, in one or more tranches. The stated purpose is to support working capital and strengthen the balance sheet. The approval does not mean that the full amount has been raised, nor does the available disclosure specify the timing, instrument mix or final terms of any issuance.
Promoter holding stood at 42.4% from Q3 FY26 through Q2 FY27 in the shareholding data provided. Investors will therefore also watch for further disclosures on the proposed capital raise, particularly because an equity-linked issue could affect the share count while debt funding could increase financing obligations.
How could the Q2 FY27 release affect investors and operations?
The results will provide a near-term measure of whether V.I.P. Industries can build on Q1’s 3% year-on-year sales growth. Continued positive growth would support the view that demand and product activity have improved from the FY26 period, when quarterly revenue had contracted year on year for four straight quarters.
Profitability will be equally important for shareholders because the company’s Q1 FY27 net loss widened despite higher revenue. A better margin or a move toward profit would indicate improved operating conversion, while another loss would underline that the sales recovery has not yet resolved the company’s earnings pressure.
The stock had experienced a 68% drawdown according to the provided market commentary. That context increases the importance of the company’s commentary on full-year demand, margin discipline and capital requirements. No outcome should be assumed before the board releases the unaudited financial statements and related disclosures.
Conclusion
V.I.P. Industries enters its Q2 FY27 result announcement with a clearer revenue recovery signal but unresolved profitability concerns. Q1 revenue rose 3% year on year to ₹578.36 crore, yet the company posted a ₹53.56 crore consolidated net loss. The September-quarter result will show whether higher sales are beginning to produce a more durable operating improvement.
Investors should watch the reported revenue growth against the ₹580 crore to ₹600 crore market estimate, EBITDA margin performance, net profit or loss, and any statement on FY27 demand conditions. Further disclosures on the board-approved fundraising of up to ₹500 crore, including its timing and structure, will also remain relevant after the results announcement.