










Viviana maintains FY27 target as H1 contribution rises to 30%
Key highlights
- Viviana reported H1 FY27 revenue from operations of Rs 189.07 crore, up about 173% from Rs 69.33 crore a year earlier.
- Management maintained FY27 revenue guidance of Rs 850 crore to Rs 900 crore.
- Management expects the FY27 revenue mix to shift to 30% in H1 and 70% in H2, from 20:80 last year.
- Viviana's unexecuted order book excluding BESS exceeded Rs 1,800 crore.
powered by IRIS
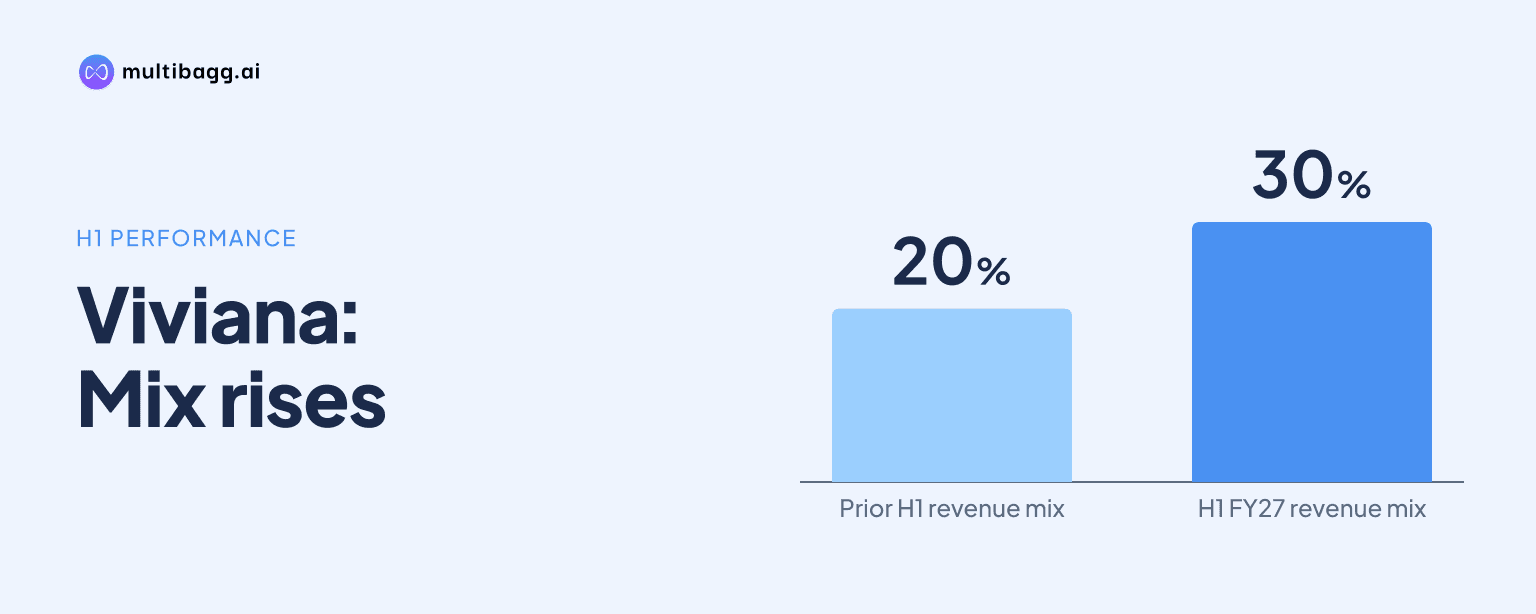
Viviana Power Tech Limited maintained its FY27 revenue target of Rs 850 crore to Rs 900 crore and said H1 should contribute 30% of annual sales, compared with a 20% H1 and 80% H2 split last year. Management expects the first-half share to rise further to 40% to 45% from next year.
Know Viviana Power Tech inside out
Results, valuation, peers and who's buying, in one view.
How is Viviana guiding FY27 revenue?
Viviana is guiding for FY27 revenue of Rs 850 crore to Rs 900 crore, and management said it remained on track after H1 revenue from operations reached Rs 189.07 crore. That compared with Rs 69.33 crore in the corresponding prior-year period, which management described as growth of about 173%.
H1 also delivered profit before tax of Rs 25.60 crore, against Rs 9.13 crore a year earlier, and profit after tax of Rs 18.61 crore, compared with Rs 6.92 crore. Management said net margin exceeded 9% in H1 and that employee costs are relatively fixed during the year, allowing higher H2 revenue to absorb those costs across a larger sales base.
Management attributed the H1 increase to execution capability, the existing order book and project teams rather than revenue from newly won work. It said projects executed during H1 were from existing orders with typical timelines of 9 to 24 months, while orders added during the half were about Rs 1,090 crore.
Why does Viviana expect H1 revenue contribution to increase?
Viviana expects a 30:70 H1-H2 revenue split in FY27, compared with 20:80 last year, because management says the order book is being executed more evenly during the year. Management said sales had earlier been concentrated in the fourth quarter, while projects are now progressing on a timely basis rather than accruing in one month or quarter.
The 30% H1 mix is management's expectation for the full year rather than a restatement of reported H1 revenue. Reported H1 revenue of Rs 189.07 crore represents roughly 21% to 22% of the Rs 850 crore to Rs 900 crore guidance range, and management did not reconcile that calculation with the 30:70 seasonal split during the call.
Management said the shift should continue beyond FY27 as Viviana participates in larger-value government orders and builds a steadier execution cadence. From next year, it expects H1 to account for 40% to 45% of annual revenue, leaving 55% to 60% for H2 instead of the historical dependence on year-end delivery.
That expectation remains linked to project timelines of 9 to 24 months and the pace at which orders are executed. Management's stated basis is that a larger order base permits revenue to accrue throughout the financial year, although it did not give quarterly FY27 revenue guidance or project-level revenue contributions.
Got a follow-up? Ask IRIS
What order book supports Viviana's revenue target?
Viviana said its unexecuted order book, excluding battery energy storage systems, or BESS, exceeded Rs 1,800 crore at the time of the call. It had also participated in bids worth more than Rs 1,900 crore and said it expected to carry forward an order book of at least Rs 800 crore to Rs 900 crore into the next financial year.
The customer mix has changed since FY24. Management said 90% of the order book came from private entities and 10% from government utilities until FY24, whereas more than 90% currently comes from government utilities. Viviana is executing projects in Punjab, Gujarat and Kerala, and management said none faced land-acquisition or execution challenges at present.
BESS is an additional activity for Viviana, which said it is bidding as an engineering, procurement and construction, or EPC, contractor rather than as a developer. Management put its bid conversion rate at 25% to 30% since last year, while cautioning that outcomes depend on several factors; technical and commercial bid openings were expected by the end of Q3 or in January.
What could determine whether Viviana achieves FY27 guidance?
Viviana's conversion of its order book into revenue depends on project execution, working capital and cost management, according to management. It said it works continuously with banks to arrange facilities and assignments based on forecast execution requirements, seeking to prevent project delays caused by a lack of financial instruments or working capital.
Management stated a long-term operating-margin range of 12.5% to 15%. It said parts of the order book contain price-variation clauses intended to protect against sudden commodity shocks, while fixed-price commodity exposure is addressed through procurement of material inputs at the time of project award.
Management identified manpower and finance costs as the two major expense areas relevant to its projected H2 turnover of around Rs 650 crore. Its plan is to improve cost optimisation, operational efficiency and working-capital management, including receivable collections and cash conversion, as H2 execution increases.
Funding is another disclosed variable. Management said it had initially planned to issue warrants to promoters and promoter groups, but now intended to raise funds through a rights issue after citing response from outside and existing investors; it said the plan had been posted on the exchange without specifying an amount or timetable on the call.
Conclusion
Viviana's FY27 outlook combines its Rs 850 crore to Rs 900 crore revenue target with management's expectation of a less back-loaded sales pattern. H1 FY27 revenue of Rs 189.07 crore was about 173% above the prior-year comparable period, while the unexecuted order book excluding BESS exceeded Rs 1,800 crore. The central change is management's forecast of a 30:70 H1-H2 mix in FY27, from 20:80 last year.
The next disclosures to watch are whether H2 delivers the indicated turnover of around Rs 650 crore, how much of the more than Rs 1,900 crore bid pipeline converts, and the technical and commercial opening of BESS bids by the end of Q3 or in January. Management's proposed rights issue and its stated expectation for H1 to contribute 40% to 45% of revenue from next year will also indicate how the planned execution cadence develops.