










Waa Solar H1 FY27 revenue nearly doubled, consolidated profit fell
Key highlights
- H1 FY27 consolidated revenue from operations rose 93.9% to Rs 17.09 crore from Rs 8.81 crore a year earlier.
- Consolidated EBITDA increased to Rs 12.54 crore from Rs 7.91 crore, while EBITDA margin declined to 68.5% from 76.1%.
- Consolidated profit after tax fell to Rs 68.12 lakh from Rs 1.82 crore as associate profit dropped to Rs 35.57 lakh from Rs 1.74 crore.
- Consolidated net debt increased to Rs 165.81 crore at September 30, 2026, from Rs 135.16 crore at March 31, 2026.
powered by IRIS
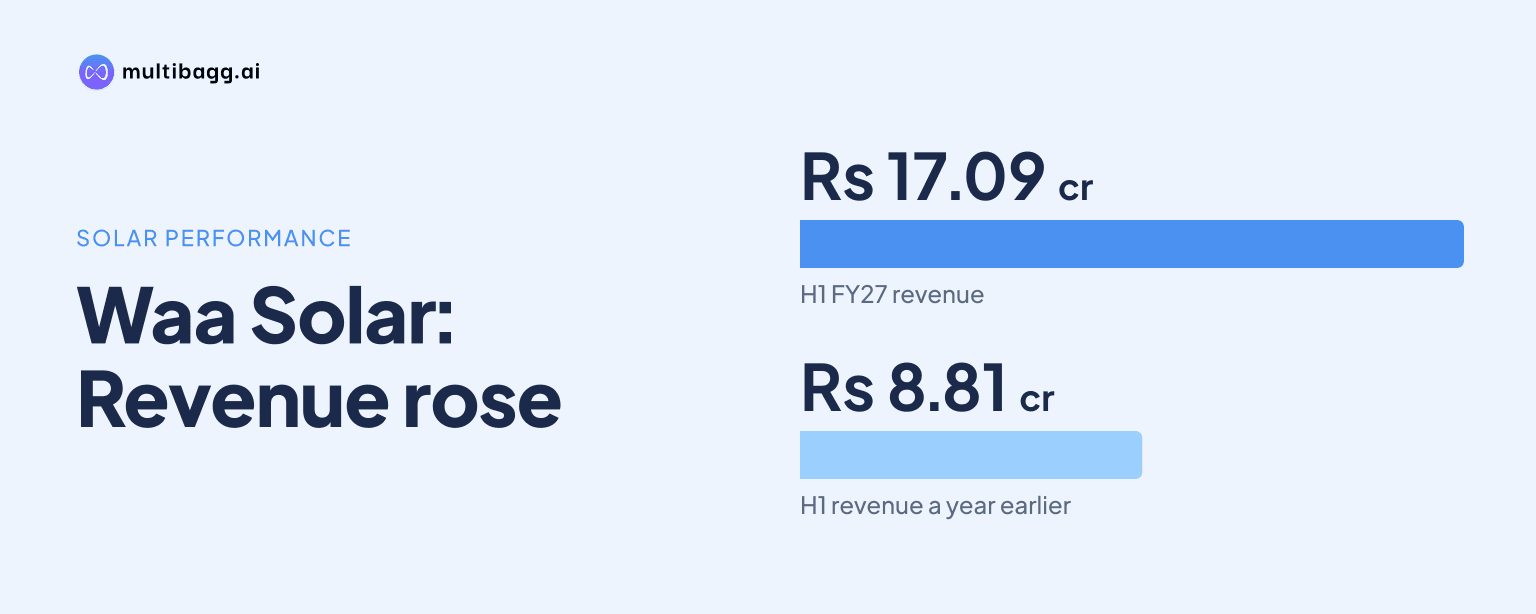
Waa Solar Limited reported H1 FY27 consolidated revenue from operations of Rs 17.09 crore, up 93.9% from Rs 8.81 crore in H1 FY26, while profit after tax declined to Rs 68.12 lakh from Rs 1.82 crore. The share of profit from associates fell to Rs 35.57 lakh from Rs 1.74 crore, despite higher EBITDA.
Know Waa Solar inside out
Results, valuation, peers and who's buying, in one view.
How did Waa Solar’s H1 FY27 operating performance change?
Waa Solar’s operating performance improved year on year, with consolidated revenue from operations rising 93.9% to Rs 17.09 crore in H1 FY27 from Rs 8.81 crore in H1 FY26. Consolidated total income, including other income, increased to Rs 18.32 crore from Rs 10.40 crore. Other income declined to Rs 1.22 crore from Rs 1.58 crore, so revenue from operations accounted for the expansion in total income.
Consolidated EBITDA, defined by the presentation as profit before interest, depreciation and tax including other income, rose to Rs 12.54 crore from Rs 7.91 crore. EBITDA margin, calculated on total income, declined to 68.5% from 76.1%. The margin change shows that EBITDA increased by less than total income over the two first-half periods.
Waa Solar’s H1 FY27 revenue was below the Rs 18.96 crore reported in H2 FY26, while EBITDA exceeded the preceding half’s Rs 10.28 crore. EBITDA margin was 68.5% in H1 FY27, compared with 51.2% in H2 FY26. This places the first-half operating result above H2 FY26 on EBITDA and margin, although not on revenue.
Why did Waa Solar’s consolidated profit fall despite revenue growth?
Waa Solar’s consolidated profit after tax fell because its share of profit from associates declined sharply, while finance costs and depreciation were higher. Share of profit from associates was Rs 35.57 lakh in H1 FY27, versus Rs 1.74 crore in H1 FY26. Consolidated profit after tax therefore fell to Rs 68.12 lakh from Rs 1.82 crore, even as revenue and EBITDA rose.
Consolidated profit before tax, shown before the separately reported associate contribution, increased to Rs 38.56 lakh from Rs 9.35 lakh. Finance costs rose to Rs 7.36 crore from Rs 4.81 crore, and depreciation and amortisation increased to Rs 4.80 crore from Rs 3.00 crore. Tax and earlier-year adjustments were Rs 6.01 lakh, compared with Rs 1.67 lakh a year earlier.
The standalone figures provide a different result because they do not include associate profit. Standalone profit after tax rose to Rs 24.63 lakh in H1 FY27 from Rs 8.36 lakh in H1 FY26, while standalone profit before tax increased to Rs 29.18 lakh from Rs 10.03 lakh. Standalone revenue from operations grew 96.8% to Rs 16.79 crore and standalone EBITDA rose 59.2% to Rs 12.31 crore.
Got a follow-up? Ask IRIS
What changed in Waa Solar’s balance sheet by September 2026?
Waa Solar’s consolidated net debt increased to Rs 165.81 crore at September 30, 2026, from Rs 135.16 crore at March 31, 2026. Total borrowings rose to Rs 190.64 crore from Rs 178.12 crore, including Rs 167.72 crore of long-term borrowings and Rs 22.92 crore of short-term borrowings at the September date. Net debt to equity increased to 0.90 times from 0.73 times.
Cash and bank balances fell to Rs 24.83 crore from Rs 42.95 crore over the six-month period. Consolidated property, plant and equipment increased to Rs 193.21 crore from Rs 181.30 crore, while capital work-in-progress declined to Rs 10.32 crore from Rs 19.90 crore. These reported movements coincided with an increase in borrowings and a reduction in cash balances.
Consolidated total assets declined to Rs 384.81 crore at September 30, 2026, from Rs 412.00 crore at March 31, 2026. Consolidated net worth was Rs 184.27 crore, compared with Rs 184.62 crore at the audited March 2026 year-end. On a standalone basis, net worth was Rs 183.34 crore, versus Rs 183.10 crore, while net debt increased to Rs 141.74 crore from Rs 110.41 crore.
Which Waa Solar projects could affect future results?
Waa Solar had a 48.15 megawatt feeder-level solarisation project in Madhya Pradesh under execution as of September 30, 2026. The project was awarded under PM-KUSUM C in FY2025-26 for Madhya Pradesh Urja Vikas Nigam Ltd. The presentation says it had achieved in-principle financial closure, completed land acquisition, secured major long-lead components and begun on-ground execution.
Waa Solar also reported that its 1.5 megawatt Mitana plant in Gujarat had been commissioned, while the 4 megawatt Paddhari plant was under execution. The 5.5 megawatt package is under PM-KUSUM C for Paschim Gujarat Vij Company Ltd. The presentation additionally lists seven special purpose vehicles under the Surya Mitra Krishi Feeder Scheme in Madhya Pradesh for grid-connected solar plants selling power to Madhya Pradesh Power Management Company Ltd.
Management’s stated strategy targets 300 megawatts by 2030 across standalone solar, solar plus battery energy storage systems, standalone battery energy storage systems and commercial and industrial offtake. The plan includes firm and dispatchable renewable-energy contracts with 20-to-25-year power purchase agreements. Management also disclosed a FY28 target for a maritime decarbonisation pilot vessel, while technology tie-ups with marine original equipment manufacturers remain under evaluation.
Conclusion
Waa Solar’s H1 FY27 figures show that higher operating revenue and EBITDA did not produce comparable consolidated profit growth. Revenue from operations nearly doubled, while standalone profit after tax increased, but the reduction in associate profit and higher financing and depreciation charges accompanied a fall in consolidated profit after tax.
The next disclosed milestones are the execution of the 48.15 megawatt Madhya Pradesh project and completion of the 4 megawatt Paddhari project. Management’s 300 megawatt target for 2030 and its FY28 maritime pilot target set the stated expansion timetable, while changes in borrowings, cash and associate income remain unresolved matters to watch.