










Welspun Enterprises Sees Rs 1,000-1,200 Crore FY28 Revenue
Key highlights
- Welspun Enterprises forecasts Pune-Shirur revenue of Rs 1,000 crore to Rs 1,200 crore in FY28.
- Pune-Shirur has debt sanctions of Rs 6,334 crore from Union Bank of India and Punjab National Bank.
- Welspun Enterprises targets Pune-Shirur financial closure and its appointed date in Q4 FY27.
- Welspun Enterprises expects Pune-Shirur to contribute Rs 300 crore to Rs 400 crore of revenue in FY27.
powered by IRIS
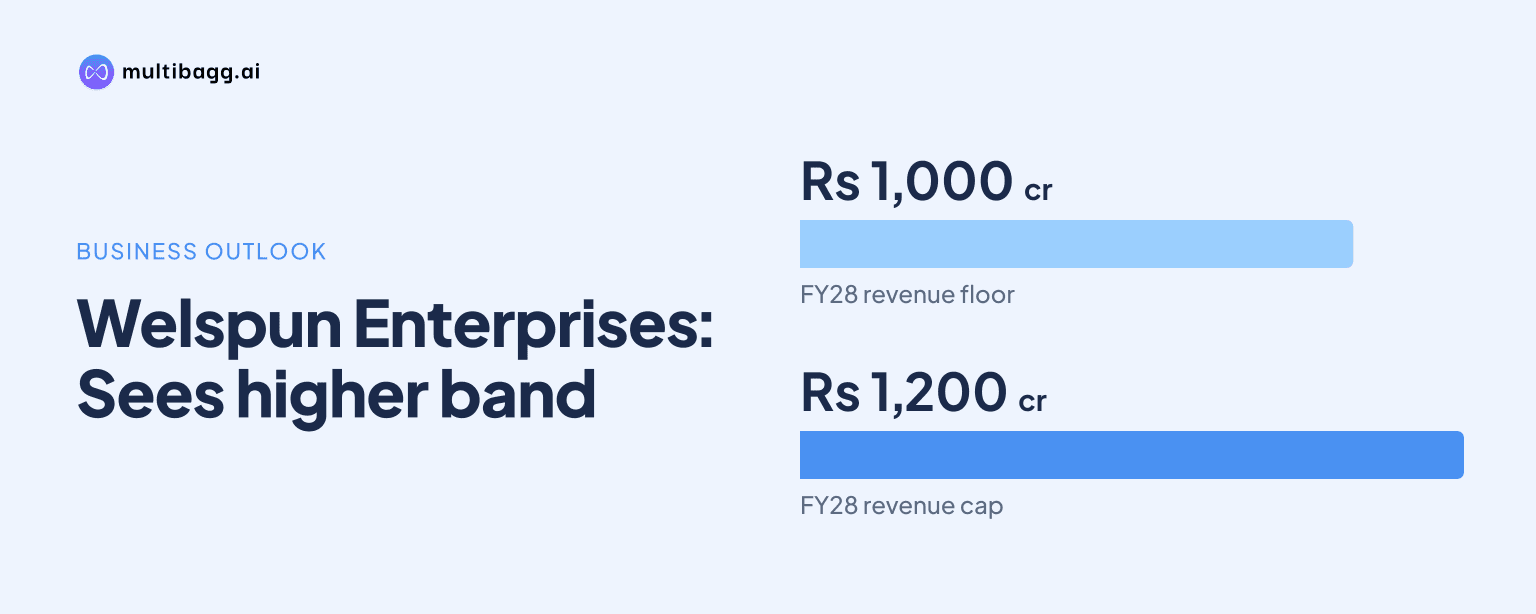
Welspun Enterprises Limited expects the Pune-Shirur Road Project to generate Rs 1,000 crore to Rs 1,200 crore of revenue in FY28, after targeting financial closure and an appointed date in Q4 FY27. The project has debt sanctions of Rs 6,334 crore and is expected to contribute Rs 300 crore to Rs 400 crore in FY27, depending on the appointed-date timing.
Know Welspun Enterprises inside out
Results, valuation, peers and who's buying, in one view.
When will Welspun Enterprises complete Pune-Shirur financial closure?
Welspun Enterprises expects financial closure and the Pune-Shirur Road Project’s appointed date in Q4 FY27. Management said Union Bank of India and Punjab National Bank had sanctioned Rs 6,334 crore of debt for the project, with construction activity expected to gather momentum toward the end of FY27 once these milestones are achieved.
The company had completed topographical surveys and geotechnical investigations by its November 6, 2026 earnings call. It was establishing casting yards at two locations, progressing design work and conducting test piling at select locations. These pre-construction activities precede the Q4 FY27 funding and appointed-date targets disclosed by management.
How much revenue does Welspun Enterprises expect from Pune-Shirur?
Welspun Enterprises forecasts Rs 300 crore to Rs 400 crore of Pune-Shirur revenue in FY27 and Rs 1,000 crore to Rs 1,200 crore in FY28. Management linked the FY27 range to receipt of the appointed date in Q4 FY27, which would leave a limited period for construction revenue during the financial year.
The FY28 range is Rs 600 crore to Rs 900 crore above the FY27 range at the respective ends. The increase reflects management’s projected transition from a late-FY27 construction start to a fuller FY28 execution period; the company did not disclose a Pune-Shirur project margin, total cost or equity commitment.
What work has Welspun Enterprises completed on Pune-Shirur?
Welspun Enterprises has completed the Pune-Shirur project’s topographical and geotechnical work, while casting yards are being established at two sites. Design activities are progressing and test piling has begun at selected locations, according to management’s Q2 FY27 update.
The project is one of several transportation assets at different stages of execution and monetisation. The Varanasi-Aurangabad Road Project had been completed and was awaiting a provisional completion certificate, while the Sattanathapuram-Nagapattinam Project was 90% complete. Separately, Welspun Enterprises expected the Aunta-Simaria Road Project divestment to be reflected in Q3 FY27 financial results.
How does Pune-Shirur fit Welspun Enterprises' order book and growth plan?
Welspun Enterprises is adding Pune-Shirur execution capacity within a consolidated order book of about Rs 18,700 crore as of September 30, 2026. Management said this order book supported visibility for the remainder of FY27 and later years, while the Pune-Shirur appointed date could begin contributing construction revenue in Q4 FY27.
Management maintained its target to add Rs 8,000 crore to Rs 10,000 crore of orders during FY27, with most awards expected in H2 FY27. It said water projects would be the primary driver of remaining FY27 orders, including transmission and treatment work, with some rehabilitation and tunnelling opportunities. Transportation orders could start arriving by year-end or early in FY28.
The company maintained FY27 consolidated revenue-growth guidance of 10% to 20% and an earnings before interest, tax, depreciation and amortisation, or EBITDA, margin target of 18% or more. H1 FY27 consolidated revenue was Rs 1,808 crore, up 11% year on year, and management said H2 has historically generated a larger share of annual revenue.
Got a follow-up? Ask IRIS
What financial position did Welspun Enterprises report before the ramp-up?
Welspun Enterprises reported cash and cash equivalents of Rs 1,432 crore, net debt of Rs 450 crore and net worth of Rs 3,581 crore as of September 30, 2026. Management also reported net debt to equity of 0.2 times and said its cash position gave it flexibility in selecting new opportunities.
In Q2 FY27, consolidated revenue from operations rose 32% year on year to Rs 1,035 crore and EBITDA rose 122% to Rs 425 crore. The EBITDA margin was 39.5%, compared with 23.9% in Q2 FY26, and included a Rs 194 crore gain from completing the sale of a 51% stake in the Mukarba Chowk-Panipat Road Project.
For H1 FY27, EBITDA rose 53% year on year to Rs 610 crore and the EBITDA margin increased to 32.4% from 23.9% in H1 FY26. CRISIL upgraded Welspun Enterprises’ long-term rating to AA with a stable outlook during the quarter, while ICRA maintained its AA stable rating, according to management.
How does Pune-Shirur compare with Welspun Enterprises' other projects?
Welspun Enterprises expects Pune-Shirur to ramp up alongside water and specialised-engineering projects with different completion schedules. The 418 million litres per day Dharavi Wastewater Treatment Facility remains targeted for commissioning by July 2027, followed by a 15-year operations and maintenance contract.
The Panjarpur 910 million litres per day water-treatment plant, secured in December 2025, had completed initial mobilisation and started excavation, with targeted completion in April 2030. In Uttar Pradesh Jal Jeevan Mission work, more than 80% physical completion had been achieved and over 450 of 1,068 schemes were in trial or operations and maintenance phases.
Welspun Michigan Engineers Limited, a specialised engineering business, had an order book of Rs 2,279 crore as of September 30, 2026, including a Rs 995 crore Dharavi-Ghatkopar Tunnel project. Management described this as about three years of revenue at the current run rate, with tunnelling representing 53% of the order book, pumping 21% and rehabilitation 19%.
Conclusion
Pune-Shirur is positioned by Welspun Enterprises as a material transportation-project contributor, with Rs 6,334 crore of debt sanctions supporting its planned transition from preparatory work to construction. Management’s Rs 1,000 crore to Rs 1,200 crore FY28 revenue forecast would represent a substantial increase from the Rs 300 crore to Rs 400 crore expected in FY27.
The next disclosed milestone is financial closure and the appointed date in Q4 FY27, since management tied the FY27 revenue forecast and construction ramp-up to that timing. The company also expects most of its Rs 8,000 crore to Rs 10,000 crore FY27 order additions in H2 FY27, led primarily by water, rehabilitation and tunnelling opportunities.