










Yatharth occupancy reaches 72% as stay falls to 3.3 days
Key highlights
- Yatharth reported 72% occupancy in Q2FY27, up from 66% in Q2FY26.
- Yatharth's Q2FY27 ARPOB was Rs 35,948, compared with Rs 32,426 a year earlier.
- Yatharth reduced ALOS to 3.3 days in Q2FY27 from 4.0 days in Q2FY26.
- Yatharth's total patient volumes rose to 194,000 in Q2FY27 from 130,000 a year earlier.
powered by IRIS
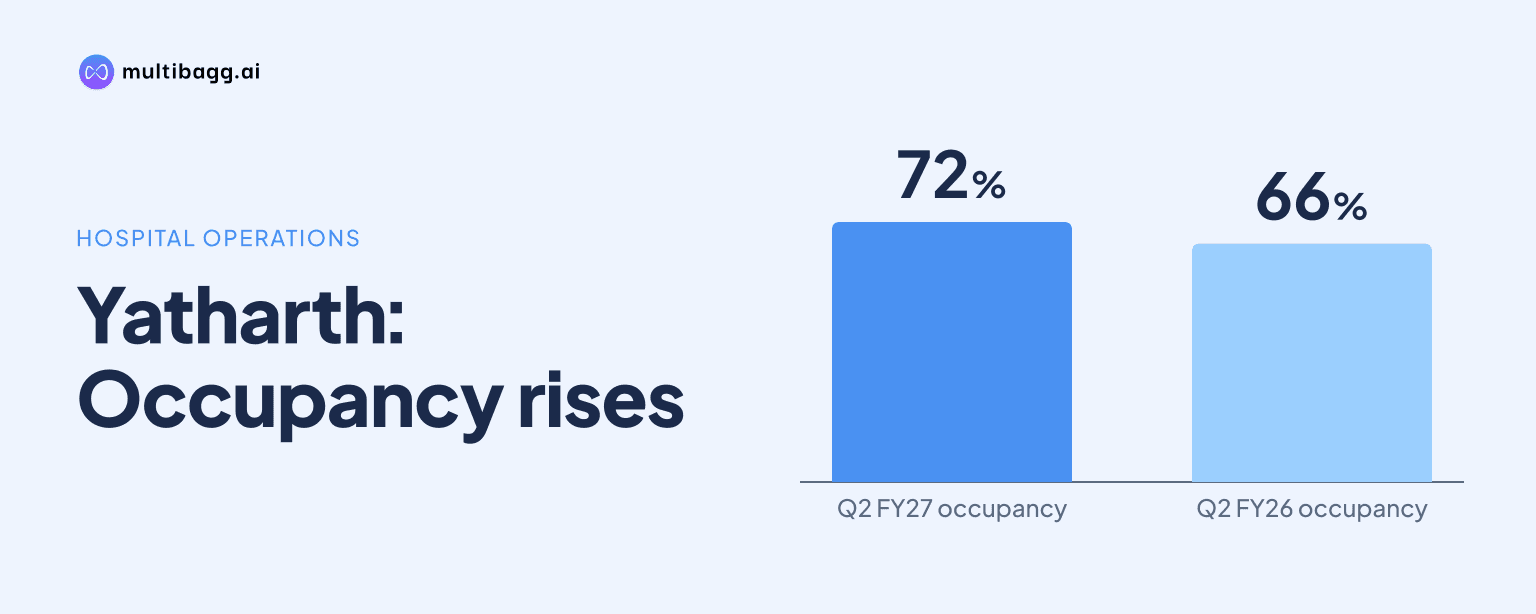
Yatharth Hospitals reached 72% occupancy in Q2FY27, up from 66% a year earlier, as average length of stay fell to 3.3 days from 4.0 days and average revenue per occupied bed rose 11% to Rs 35,948. Total inpatient and outpatient volumes increased to 194,000 from 130,000 in Q2FY26.
Know Yatharth Hospital & Trauma Care Services inside out
Results, valuation, peers and who's buying, in one view.
How did Yatharth reach 72% occupancy in Q2FY27?
Yatharth reached 72% occupancy in Q2FY27, compared with 66% in Q2FY26 and 68% in Q1FY27. The measure was based on 1,820 operational census beds in Q2FY27, up from 1,535 in Q2FY26, while total bed capacity increased to 2,555 from 2,305. Occupancy therefore increased despite the addition of 285 operational census beds over the year.
The distinction between total capacity and operational census beds is material because Yatharth calculates occupancy on beds currently operational for census purposes. The company said its New Delhi, Faridabad Sector-20, Agra and Gurugram hospitals were yet to be fully ramped up, and that census beds would increase progressively. H1FY27 occupancy was 70%, versus 66% in H1FY26, on 1,820 census beds compared with 1,535.
Why did Yatharth's average length of stay decline?
Yatharth reported an average length of stay, or ALOS, of 3.3 days in Q2FY27, down from 4.0 days in Q2FY26 and 3.7 days in Q1FY27. The presentation describes the network trend as faster discharges occurring alongside increasing patient volumes and rising average revenue per occupied bed, or ARPOB. H1FY27 ALOS was 3.5 days, compared with 4.1 days in H1FY26.
The lower ALOS coincided with higher activity in both inpatient departments, or IPD, and outpatient departments, or OPD. IPD volume rose to 36,000 in Q2FY27 from 22,000 in Q2FY26, while OPD volume increased to 158,000 from 108,000. Combined volumes were therefore 194,000 in the quarter, compared with 130,000 a year earlier.
The first-half comparison shows a similar change. Yatharth reported 66,000 IPD volumes and 297,000 OPD volumes in H1FY27, for total volume of 363,000, compared with 41,000, 213,000 and 254,000 respectively in H1FY26. The company consequently reported 109,000 more total patient volumes in H1FY27 while ALOS declined by 0.6 days.
How much did Yatharth raise revenue per occupied bed?
Yatharth raised ARPOB to Rs 35,948 in Q2FY27 from Rs 32,426 in Q2FY26, an 11% year-on-year increase. The Q2FY27 figure was also above Rs 34,758 in Q1FY27. ARPOB is presented by the company alongside occupancy and ALOS as a network operating measure.
For H1FY27, ARPOB increased to Rs 35,371 from Rs 32,500 in H1FY26, while ALOS declined to 3.5 days from 4.1 days. Over the same half-year comparison, occupancy rose to 70% from 66%. The reported measures show higher revenue per occupied bed alongside shorter stays and greater use of operational census beds.
Got a follow-up? Ask IRIS
How did higher volumes translate into Yatharth's revenue?
Yatharth reported revenue of Rs 431.4 crore in Q2FY27, up 52% from Rs 283 crore in Q2FY26 and 10% from Rs 392.7 crore in Q1FY27. IPD revenue increased to Rs 373.9 crore from Rs 251 crore a year earlier, while OPD revenue rose to Rs 57.5 crore from Rs 32 crore. The reported IPD and OPD figures add to the quarterly total in both periods.
In H1FY27, total revenue was Rs 824.1 crore, compared with Rs 542.3 crore in H1FY26. IPD revenue accounted for Rs 714.9 crore in H1FY27 versus Rs 479.8 crore a year earlier, and OPD revenue was Rs 109.1 crore versus Rs 62.5 crore. Thus, both treatment settings recorded higher reported revenue during the half year.
Earnings before interest, tax, depreciation and amortisation, or EBITDA, was Rs 102 crore in Q2FY27, compared with Rs 68.1 crore in Q2FY26. Reported EBITDA margin was 23.6%, versus 24.1% a year earlier, while adjusted EBITDA margin was 28.2% in Q2FY27. Yatharth defines adjusted EBITDA margin as excluding ramp-up losses from Model Town and Faridabad Sector-20.
What role are newer hospitals playing in Yatharth's growth?
Yatharth said newer hospitals contributed Rs 120.5 crore of revenue in Q2FY27 and represented 28% of revenue mix, compared with 11% in Q2FY26. The company defines newer hospitals as Greater Faridabad, New Delhi Model Town, Faridabad Sector-20 and Agra. Existing hospitals represented 72% of Q2FY27 revenue mix, down from 89% a year earlier, while delivering 24% year-on-year revenue growth according to the presentation.
Faridabad Sector-20 generated Rs 40 crore of Q2FY27 revenue, approximately 9% of Yatharth's total, and its latest monthly revenue was about Rs 15 crore. The 400-bed hospital reported latest ARPOB of about Rs 40,000 and was EBITDA-profitable in Q2FY27 after reaching EBITDA breakeven in nine months. Management expects radiation oncology to begin from H2FY27, after the transplant programme went live in H1FY27.
Model Town, New Delhi, contributed Rs 26 crore in Q2FY27, or about 6% of total revenue, with latest monthly revenue of about Rs 10 crore and latest ARPOB of about Rs 50,000. Management expects its EBITDA breakeven in H2FY27. Agra generated Rs 20 crore, about 5% of Q2FY27 revenue, was EBITDA-profitable in the quarter and reported latest ARPOB of about Rs 33,000.
Conclusion
Yatharth's Q2FY27 data shows occupancy, throughput and revenue per occupied bed increasing at the same time. Occupancy rose by 6 percentage points year on year to 72%, total volumes rose by 64,000 to 194,000, and ARPOB increased by Rs 3,522 to Rs 35,948 as ALOS declined by 0.7 days. These operating changes coincided with quarterly revenue of Rs 431.4 crore.
The next disclosed capacity milestone is the proposed 250-bed Gurugram hospital in Sector 40, which Yatharth expects to operationalise in H1FY28. The proposed outlay is Rs 200 crore, including a Rs 100 crore acquisition and Rs 100 crore of additional outlay including medical equipment, with ARPOB potential of about Rs 50,000 or more. Before then, management's disclosed milestones include Model Town's expected EBITDA breakeven and Faridabad Sector-20's planned radiation oncology launch in H2FY27.