










Advait Energy Transitions Q2 FY27 Revenue Rises 40.8%
Key highlights
- AETL reported Q2 FY27 revenue of ₹220.94 crore, up 40.8% year on year.
- Q2 FY27 EBITDA rose 84.4% to ₹32 crore and EBITDA margin improved to 14.5%.
- Q2 FY27 PAT increased 88.5% to ₹19 crore, with PAT margin at 8.7%.
- H1 FY27 revenue reached ₹400 crore, up 45.4% from ₹275 crore in H1 FY26.
powered by IRIS
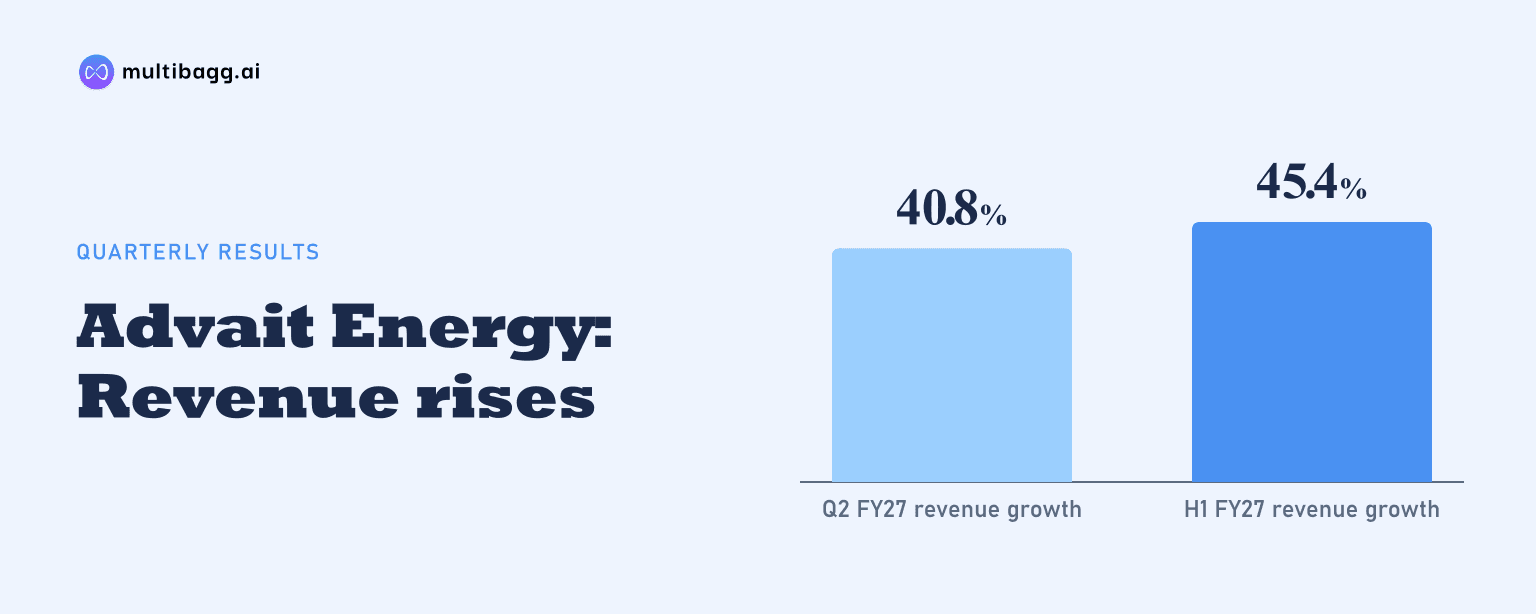
Advait Energy Transitions Limited reported Q2 FY27 revenue of ₹220.94 crore, a 40.8% year-on-year increase from ₹156.87 crore, and said the audio recording of its November 2, 2026 post-results conference call is available on its website. The company also reported EBITDA growth of 84.4% to ₹32 crore.
Know Advait Energy Transitions inside out
Results, valuation, peers and who's buying, in one view.
What did Advait Energy Transitions report for Q2 FY27?
Advait Energy Transitions Limited, referred to as AETL, reported consolidated revenue from operations of ₹220.94 crore for the quarter ended September 30, 2026. The figure was 40.8% higher than ₹156.87 crore reported in Q2 FY26. The quarterly update was discussed in the company’s Q2 and H1 FY27 earnings conference call held on November 2, 2026.
AETL said quarterly EBITDA stood at ₹32 crore, up 84.4% from the corresponding quarter a year earlier. EBITDA margin improved to 14.5% from 11.0% in Q2 FY26. Profit after tax rose 88.5% year on year to ₹19 crore from ₹10 crore, while PAT margin increased to 8.7% from 6.5%.
The company announced under Regulation 30 of the Listing Obligations and Disclosure Requirements regulations that the audio recording of the post-results call on unaudited financial results for the quarter and half year ended September 30, 2026 had been made available on its website. The call was hosted by Concept Investor Relations and included AETL’s founder and managing director Shalin Sheth, chief financial officer Narayan Singh, and other senior executives.
How did AETL perform in the first half of FY27?
AETL reported H1 FY27 consolidated revenue from operations of ₹400 crore, a 45.4% increase from ₹275 crore in H1 FY26. The first-half figures indicate that the company maintained revenue growth through the September quarter after reporting its audited FY26 results earlier in the year.
First-half EBITDA was ₹57 crore, up 82.6% year on year, with the EBITDA margin improving to 14.2% from 11.3% in the comparable prior-year period. H1 FY27 profit after tax was ₹34 crore, up 77.9% from ₹19 crore a year earlier. The reported profit growth exceeded revenue growth for the half year, alongside the improvement in operating and PAT margins.
What is driving AETL’s business activity?
AETL identified India’s investment in transmission capacity, grid modernisation and renewable-energy evacuation as areas creating opportunities across the product segments in which it operates. The company provides solutions in power transmission, telecommunication infrastructure and renewable-energy transitions.
Management also said the company is engaged with hydrogen and ammonia developers, as well as certain public-sector undertakings working on hydrogen, ammonia and related-molecule projects for India and export markets. The statement describes AETL’s business engagement in these areas, but the available call material does not quantify potential orders, revenue or project awards from them.
The company’s reported revenue growth comes against a broader need for transmission infrastructure as renewable generation capacity is added and requires grid connectivity. AETL linked its operating opportunities to constraints in expanding the transmission network and the need for grid modernisation. No separate segment-wise revenue contribution was provided in the supplied call extracts.
Got a follow-up? Ask IRIS
How do the Q2 FY27 margins compare with earlier targets?
AETL’s Q2 FY27 EBITDA margin of 14.5% was higher than the 11.0% reported in Q2 FY26, but it remained below the 15% to 17% EBITDA-margin range referenced in the company’s earlier Q3 FY25 earnings-call target. The margin improvement nevertheless accompanied a substantial rise in quarterly EBITDA and profit after tax.
For FY26, AETL had reported consolidated revenue of ₹714.52 crore, up 80% year on year. That result exceeded both the earlier 50% compound annual growth target and the subsequently referenced 40% to 45% revenue-growth guidance. In Q4 FY26, however, consolidated EBITDA margin was 12.61%, below the stated 15% to 17% range.
The company had also previously said the first 300 MW of electrolyser manufacturing capacity should be completed by 2026. In the Q4 FY26 call, management said a multi-integrated manufacturing facility would be operational by Q4 FY27, representing a later timetable than the previously revised end-March 2027 expectation. The Q2 FY27 material supplied does not provide a fresh commissioning update for that facility.
What does the announcement mean for investors and industry participants?
The audio-recording disclosure gives investors access to management’s discussion following the release of AETL’s September-quarter results. The company’s reported numbers show faster growth in EBITDA and PAT than in revenue, supported by higher operating and net profit margins. The source material does not provide a share-price reaction, valuation data, order-book figure or fresh financial guidance.
For customers and industry participants, AETL’s comments underline its focus on transmission, grid-modernisation and renewable-energy-related opportunities. Its references to hydrogen and ammonia developers indicate engagement with potential project participants, but should not be treated as confirmed commercial wins because the company did not disclose contract values, execution schedules or awarded projects in the available extract.
The available material also distinguishes between reported results and management commentary. The Q2 FY27 figures were cited from the investor presentation, while the company’s disclosure concerned the availability of the conference-call audio. AETL had not published a separate earnings-call transcript for the quarter in the material provided.
Conclusion
AETL reported a 40.8% rise in Q2 FY27 revenue to ₹220.94 crore, while EBITDA increased 84.4% to ₹32 crore and PAT rose 88.5% to ₹19 crore. The results showed improved margins across the quarter and first half, with the company connecting its operating activity to transmission expansion, grid modernisation and renewable-energy evacuation.
Investors will watch for further information on the multi-integrated electrolyser manufacturing facility, which management had previously targeted to become operational by Q4 FY27. Other points to monitor include whether AETL provides fresh guidance, discloses project wins in hydrogen or ammonia, and sustains its improved EBITDA margin in subsequent quarters.