










Advait Energy Transitions seeks orders before 150-MW ramp
Key highlights
- Advait's 30-MW electrolyser assembly line was inaugurated in March 2026 and is assembling its first 1-MW in-house unit.
- Management cited active electrolyser inquiries exceeding 1 GW but did not disclose commercial orders for the 30-MW line.
- Advait targets 150 MW of electrolyser capacity to be operational by nearly Q4 2027.
- Management estimates 150 MW could generate Rs 600 crore to Rs 1,000 crore of revenue, depending on scope.
powered by IRIS
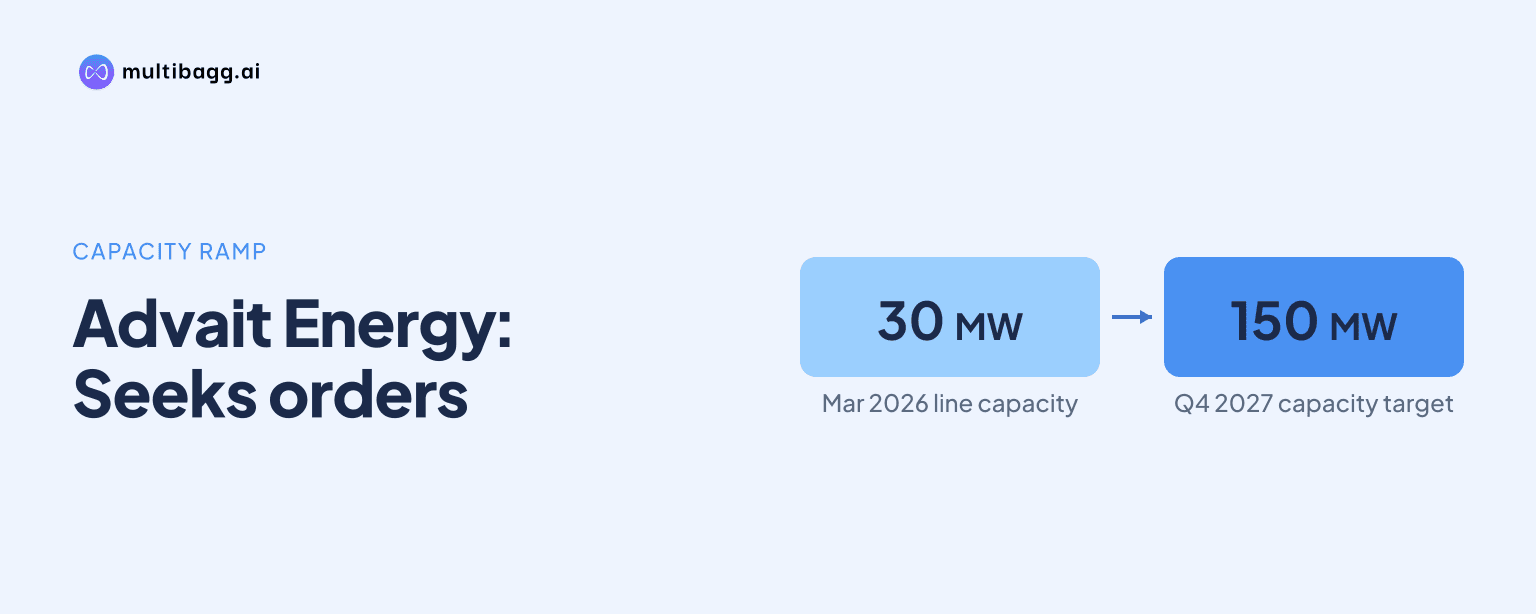
Advait Energy Transitions has disclosed more than 1 GW of active electrolyser inquiries but no commercial orders for its 30-MW assembly line, and management targets 150 MW of capacity to be operational by nearly Q4 2027. The line, inaugurated in March 2026, is assembling its first in-house 1-MW electrolyser for engineering development.
Know Advait Energy Transitions inside out
Results, valuation, peers and who's buying, in one view.
What is the status of Advait's 30-MW electrolyser line?
Advait's 30-MW assembly line is being used as a technology-transfer demonstration while the company seeks initial commercial opportunities. Management said the facility was inaugurated in March 2026 to showcase its capabilities, and that it is assembling a first 1-MW electrolyser at its own facility as part of engineering development.
Advait has also completed work on two hydrogen-related projects outside the stated in-house 1-MW development. It completed a 300-kilowatt project for THDC in Rishikesh for green-hydrogen cell applications, while a separate 1-MW private-client project in Gujarat, covering engineering, procurement and construction (EPC) and supply, was completed and was expected to be commissioned during the quarter.
These completed projects demonstrate execution of smaller hydrogen assignments, but management did not identify them as commercial orders booked for the 30-MW assembly line. Its stated immediate task is to complete the in-house unit while exploring orders that could support utilisation of the line.
When will Advait have 150 MW of electrolyser capacity?
Advait is targeting 150 MW of electrolyser capacity to be operational by nearly Q4 2027, rather than putting the full planned 300-MW facility into operation in that year. Management said it intends initially to activate half the planned capacity because it is carefully watching for the market to open.
Management separately said it believes the 30-MW operation will be utilised in 2027-28 with more than 150 MW of orders to be booked. It also described the facility as becoming operational in FY28 in numerical terms. These references point to a ramp spanning late 2027 and FY28 rather than a disclosed fixed commissioning schedule.
The longer-term construction capability is larger than the near-term target. Management said the plant could go up to 1 GW by 2028-29, but did not state that the full 1-GW scale would be installed or operational by then. The 150-MW target is therefore the nearer capacity milestone against which order conversion can be measured.
How large is Advait's electrolyser order pipeline?
Advait said it has active electrolyser inquiries exceeding 1 GW, but it did not disclose the number of inquiries, their value, counterparties, tender stages or expected conversion rate. Management said it was in the market looking for suitable opportunities after inaugurating the 30-MW line in March 2026.
The 150-MW target is equivalent to 15% of 1 GW, although inquiries are not orders and are not necessarily comparable with annual manufacturing capacity. Management's decision to initially operationalise 150 MW rather than the full planned 300 MW indicates that the pace of expansion is being tied to expected demand rather than preliminary inquiry volumes.
Management linked potential demand to the development of green-hydrogen and green-ammonia projects. It said green-ammonia purchase and sale agreements signed at the start of the financial year indicated potential offtake, with the Solar Energy Corporation of India and the Ministry of New and Renewable Energy involved in bringing private and export off-takers toward ammonia and hydrogen developers. Those comments describe market development, not confirmed electrolyser contracts for Advait.
Got a follow-up? Ask IRIS
What revenue could Advait's 150 MW generate?
Management estimated that 150 MW of electrolyser capacity could book revenue of Rs 600 crore to Rs 1,000 crore, depending on the scope of work. The range implies that the revenue outcome could differ between equipment supply and projects with additional work, but management did not disclose a per-megawatt realisation, margin or production period.
This revenue potential should be separated from Advait's wider FY27 expectations. Management said it was looking for revenue growth of 55% to 60% from the prior year and revenue above Rs 1,000 crore in FY27, while an analyst referred to an earlier Rs 1,100 crore target. Management did not assign FY27 revenue from the 30-MW electrolyser line, and linked the 150-MW milestone to nearly Q4 2027 and FY28.
What could determine expansion beyond 150 MW?
Order conversion and market readiness will determine whether Advait expands beyond 150 MW toward the 300-MW phase and the stated potential 1-GW construction capability by 2028-29. Management said it was monitoring market development before activating the whole 300 MW, while describing the current 30-MW line as a technology-transfer demonstration.
Capital allocation and cash flow are also relevant to the expansion plan. Management said it was managing the manufacturing-and-solutions business toward a debt-to-equity ratio of about 0.5 times to 0.7 times, while noting the ratio could change as the business model develops. It also said it was considering an equity fund raise in Q3 or Q4 for working-capital needs, without stating the amount or identifying electrolyser expansion as a direct use of proceeds.
The electrolyser strategy forms part of a broader business mix change. Management expects the new and renewable energy (NRE) and power transmission solutions (PTS) divisions each to contribute 50% after two to three years. It also said NRE earnings before interest, taxes, depreciation and amortisation (EBITDA) margins were about 7% to 8%, with improvement expected from manufacturing and product solutions rather than solely from EPC work.
Conclusion
Advait's disclosed electrolyser position remains at an engineering-development and market-building stage. Its 30-MW line has been inaugurated, it is assembling a 1-MW in-house unit, and it has completed a 0.3-MW THDC project and a 1-MW Gujarat assignment. However, converting more than 1 GW of active inquiries into disclosed commercial orders is necessary for the planned 150-MW scale to translate into manufacturing utilisation and revenue.
The next items to watch are management's target to have 150 MW operational by nearly Q4 2027, its expectation of more than 150 MW of orders in 2027-28, and any disclosure on the proposed Q3 or Q4 equity raise. Updates on firm orders, project scope and commissioning dates would provide the clearest evidence of progress because the Rs 600 crore to Rs 1,000 crore revenue estimate depends on scope and is not tied to disclosed bookings.