










AHEL targets Rs 25,000 crore revenue and Rs 1,500 crore EBITDA
Key highlights
- AHEL expects the proposed New Co to reach Rs 25,000 crore annualised revenue and Rs 1,500 crore EBITDA in Q4 FY27.
- The proposed combined business reported Rs 11,201.5 crore revenue and Rs 624.7 crore EBITDA after stated costs in H1 FY27.
- Combined FY26 revenue was Rs 19,036.6 crore, up from Rs 16,377.2 crore in FY25.
- AHEL and its shareholders are expected to hold an effective 59.6% of the proposed New Co.
powered by IRIS
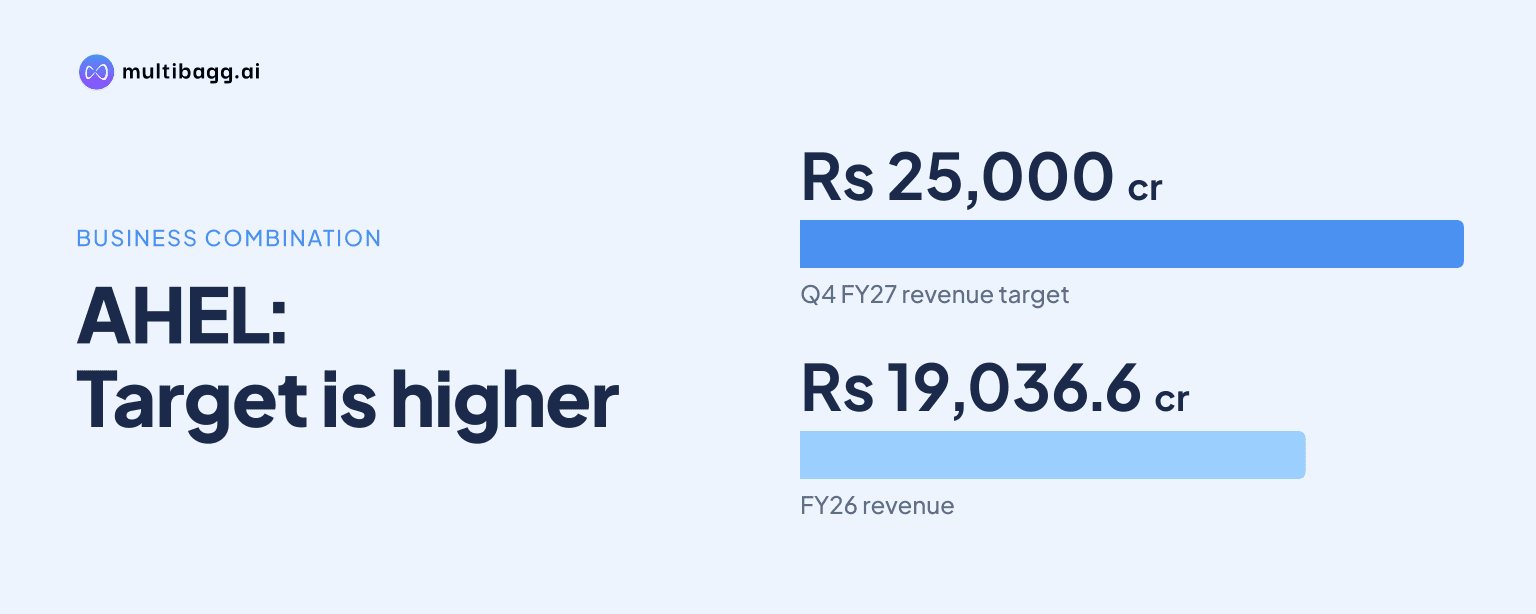
Apollo Hospitals Enterprise Ltd expects its proposed New Co to achieve annualised revenue of Rs 25,000 crore and EBITDA of Rs 1,500 crore in Q4 FY27. AHEL's combined pro forma business reported Rs 11,201.5 crore of revenue and Rs 624.7 crore of EBITDA after Apollo 24|7 operating costs and ESOP charges in H1 FY27.
Know Apollo Hospitals Enterprise inside out
Results, valuation, peers and who's buying, in one view.
What is AHEL proposing under the composite scheme?
AHEL is proposing a New Co through a sequential demerger and amalgamations under its composite scheme, which shareholders approved on 24 June 2026. The first step would demerge omnichannel pharmacy distribution, the Apollo 24|7 digital platform held through Apollo HealthCo Ltd, and AHEL's remote telehealth division into the New Co.
AHEL would next amalgamate Apollo HealthCo Ltd into the New Co, followed by Keimed Private Limited. Upon the scheme becoming effective after shareholder and National Company Law Tribunal approval, the New Co is intended to become an Indian Owned and Controlled Company and apply for stock-exchange listing.
The proposed New Co would include offline and online pharmacy distribution, Apollo 24|7, remote telehealth and Keimed. It would also hold 25.5% of AMPL, described as the 100% holding company of Apollo Pharmacies Ltd. The Apollo Pharmacy platform had 7,662 stores in Q2 FY27, after adding 223 stores and closing one during the quarter.
What financial target has AHEL set for the New Co?
AHEL expects the New Co to reach annualised revenue of Rs 25,000 crore and EBITDA of Rs 1,500 crore in Q4 FY27. The presentation identifies these figures as the company's expectation for the proposed combination, rather than reported results of a completed listed entity.
The combined pro forma business reported revenue of Rs 19,036.6 crore in FY26, compared with Rs 16,377.2 crore in FY25. EBITDA before Indian Accounting Standards, or Ind AS, effects rose to Rs 1,374.9 crore from Rs 1,118 crore over the same period, while EBITDA after Apollo 24|7 operating costs and employee stock option plan, or ESOP, non-cash charges increased to Rs 908.3 crore from Rs 532.2 crore.
Revenue increased by Rs 2,659.4 crore between FY25 and FY26, while EBITDA after the stated digital operating and ESOP charges rose by Rs 376.1 crore. The corresponding margin increased from 3.2% in FY25 to 4.8% in FY26 and was 5.6% in H1 FY27. The presentation separately reports EBITDA margins excluding digital of 6.4% in FY25, 6.5% in FY26 and 6.3% in H1 FY27.
Got a follow-up? Ask IRIS
Which businesses generated the combined H1 FY27 revenue?
Keimed generated Rs 8,656.7 crore of revenue in the combined H1 FY27 pro forma figures, exceeding Total HealthCo's Rs 6,262.8 crore. Keimed reported EBITDA before Ind AS of Rs 273.9 crore, representing a 3.2% margin, while Total HealthCo reported Rs 532.8 crore, or an 8.5% margin, on the same basis.
Offline pharmacy distribution accounted for Rs 5,513.2 crore of Total HealthCo revenue and Rs 385.6 crore of EBITDA before Ind AS in H1 FY27, at a 7.0% margin. Online pharmacy distribution and Apollo 24|7 generated Rs 749.6 crore of revenue and Rs 147.3 crore of EBITDA before Ind AS, producing a 19.6% margin before Apollo 24|7 operating costs.
Apollo 24|7 operating costs of Rs 158.1 crore and ESOP charges of Rs 24 crore reduced Total HealthCo's H1 FY27 EBITDA to Rs 350.8 crore in the combined pro forma presentation. The online pharmacy distribution and Apollo 24|7 segment recorded a Rs 34.8 crore EBITDA loss after these charges, while offline pharmacy distribution retained Rs 385.6 crore of EBITDA.
The digital platform had about 51 million registrations and more than 17,000 doctors as presented in Q2 FY27. Its operating activity included about 8.7 lakh daily active users, more than 57,400 daily medicine orders, about 16,400 daily consultations and about 3,000 daily sample collections.
How did HealthCo perform before the proposed combination?
Total HealthCo's revenue increased 22% to Rs 6,262.8 crore in H1 FY27 from Rs 5,132.4 crore in H1 FY26, while reported profit after tax rose 70% to Rs 222.2 crore from Rs 130.4 crore. AHEL said H1 FY27 revenue growth excluding the closure of a non-profitable corporate partner was 23%, including 23% for offline pharmacy distribution and 28% for online pharmacy distribution plus Apollo 24|7.
Reported Total HealthCo EBITDA increased to Rs 364.4 crore in H1 FY27 from Rs 204 crore in H1 FY26, and the reported margin moved to 5.8% from 4.0%. EBITDA before Apollo 24|7 costs increased 21% to Rs 546.4 crore, although its margin was 8.7% compared with 8.8% a year earlier. AHEL attributed the lower offline EBITDA percentage to planned manpower costs and a one-time long-term incentive plan for pharmacy, private-label and generics growth.
Digital cash loss, defined by AHEL as EBITDA after Ind AS excluding ESOP expense, narrowed to Rs 8.3 crore in H1 FY27 from Rs 87.4 crore in H1 FY26. Total HealthCo cash profit on the same basis increased to Rs 388.4 crore from Rs 260.8 crore. In Q2 FY27, digital was cash positive by Rs 1.3 crore, compared with a cash loss of Rs 38.6 crore in Q2 FY26.
AHEL and its shareholders would have an effective combined 59.6% holding in the resultant New Co. The indicated allocation comprises 15% for AHEL, about 2.5% effective economic interest through AHEL's 49% holding in Family Health Plan Ltd, and 42.1% for AHEL shareholders; Keimed promoters and other shareholders would hold 25.3%, Advent 12.1% and ESOP holders 3.0%.
Conclusion
The proposed New Co would combine AHEL's pharmacy distribution, digital and remote telehealth activities with Keimed, creating a pro forma business with Rs 11,201.5 crore revenue in H1 FY27. FY26 revenue was Rs 2,659.4 crore higher than FY25, while EBITDA after the disclosed Apollo 24|7 and ESOP charges rose by Rs 376.1 crore and the margin increased to 4.8% from 3.2%.
The next disclosed milestones are the scheme becoming effective following the required approvals, the New Co's application for listing and AHEL's estimated Q4 FY27 listing timetable. Progress toward AHEL's Q4 FY27 annualised targets of Rs 25,000 crore in revenue and Rs 1,500 crore in EBITDA, alongside the digital business's cash-profit trajectory after its Rs 1.3 crore Q2 FY27 result, remains the stated operating measure to watch.