










Ahluwalia Contracts sees Central Vista and CSMT ramp up
Key highlights
- Central Vista is targeted to deliver close to Rs 150 crore of turnover in Q3 FY27 and more than Rs 200 crore in Q4 FY27.
- CSMT billing is projected at about Rs 150 crore in Q3 FY27 and close to Rs 200 crore in Q4 FY27.
- Jewellery Park had not received a notice to proceed and was not expected to generate Q3 FY27 turnover.
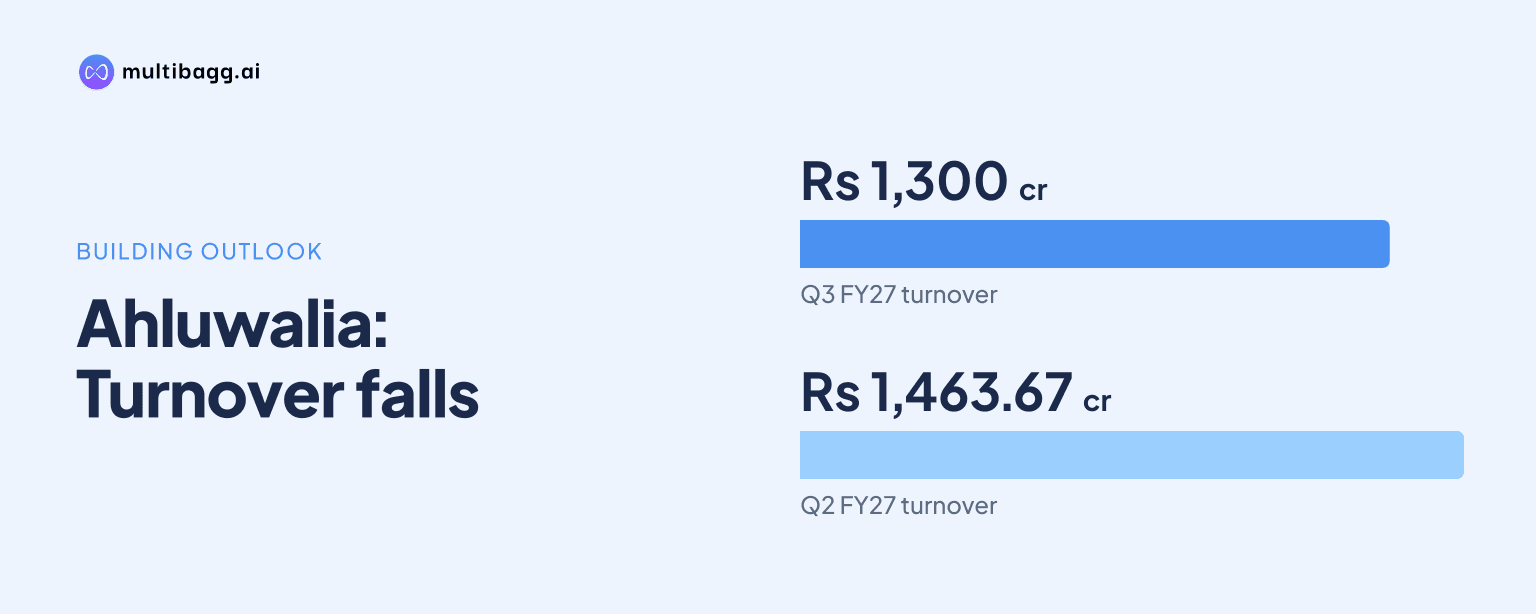
- Ahluwalia Contracts expects Q3 FY27 turnover of about Rs 1,300 crore, versus Rs 1,463.67 crore in Q2 FY27.
powered by IRIS
Ahluwalia Contracts (India) Limited expects Central Vista turnover to exceed Rs 200 crore in Q4 FY27 and CSMT billing to approach Rs 200 crore, helping offset National Capital Region disruption, while Jewellery Park had not started and was not expected to record Q3 FY27 turnover.
Know Ahluwalia Contracts (India) inside out
Results, valuation, peers and who's buying, in one view.
How is Central Vista expected to support Ahluwalia Contracts in FY27?
Central Vista is expected to provide close to Rs 150 crore of turnover in Q3 FY27 and more than Rs 200 crore in Q4 FY27, according to Ahluwalia Contracts management. The project was continuing at full speed because it is in Delhi and exempt from the Graded Response Action Plan, or GRAP, restrictions that had halted construction at other National Capital Region, or NCR, sites.
Management said Central Vista generated about Rs 43 crore of turnover in October 2026. It expected turnover of about Rs 60 crore in November and a further Rs 60 crore to Rs 70 crore in December, which would support the close to Rs 150 crore Q3 target. For Q4 FY27, management described more than Rs 200 crore as the project’s initial turnover target.
The projected Q3 contribution is meaningful because Ahluwalia Contracts expects company turnover of about Rs 1,300 crore for the quarter, up from about Rs 1,100 crore in Q3 of the previous financial year but down from Rs 1,463.67 crore in Q2 FY27. Management attributed the sequential decline of up to 10% to GRAP-related disruption and said Central Vista would partly make up for lost NCR work.
Central Vista’s ramp is also consistent with management’s earlier project outlook, which it reaffirmed during the November 16, 2026 call. The company had previously indicated about Rs 700 crore of Central Vista turnover for FY27 and about Rs 1,000 crore in the following year. Those figures remain management targets rather than reported project revenue.
What is changing at the CSMT railway station project?
CSMT activity has picked up, with about Rs 80 crore of billed turnover in the month before the November 16 call, compared with about Rs 50 crore previously. Ahluwalia Contracts said most designs had been approved, and management said the project was on track to meet targets it had discussed in the preceding earnings call.
The company expects CSMT billing of about Rs 150 crore in Q3 FY27 and close to Rs 200 crore in Q4 FY27. This puts the project’s Q4 billing plan broadly alongside Central Vista’s target of more than Rs 200 crore of turnover, though the two figures are not identical measures because management specifically described CSMT’s figures as billing.
Reported CSMT billing can lag work completed because railway payment processes differ from those on standard engineering, procurement and construction, or EPC, contracts. Management said actual work completed in the prior month was about Rs 100 crore to Rs 110 crore, compared with registered and billed turnover of about Rs 80 crore. That gap means the project’s site progress and revenue recognition may not move in the same month.
Got a follow-up? Ask IRIS
Why will Jewellery Park not add near-term revenue?
Jewellery Park was not expected to contribute turnover in Q3 FY27 because Ahluwalia Contracts had not received a notice to proceed from the client. Management said the project had theoretically not started as of November 16, 2026, while the client was sorting permissions and other internal matters.
Even after the notice to proceed, actual work would take about three months to begin, according to management. The client still needs to clear land above the site, and management said a Mumbai restriction on some earthwork and dumping activities was also being sorted out. These prerequisites distinguish Jewellery Park from Central Vista, where October turnover was Rs 43 crore, and CSMT, where recent billing was Rs 80 crore.
Management declined to assign a January or Q4 FY27 revenue number to Jewellery Park. As a result, the call provided no disclosed FY27 revenue target for the project, unlike the Rs 150 crore Q3 and more than Rs 200 crore Q4 targets for Central Vista and the Rs 150 crore and close to Rs 200 crore CSMT billing plans.
The absence of a start notice does not indicate that the contract has left Ahluwalia Contracts’ order book. The company reported a net order book of Rs 19,627.92 crore as of September 30, 2026, scheduled for execution over the next three to three-and-a-half years. However, management’s comments show that Jewellery Park cannot be counted on for near-term turnover until client permissions, site clearance and the notice to proceed are resolved.
What does the project mix mean for Ahluwalia Contracts' outlook?
Ahluwalia Contracts maintained FY27 revenue-growth guidance of 15%, with management saying growth would be “definitely 15%+,” while its FY28 growth outlook remained 15% to 20%. Turnover rose to Rs 1,463.67 crore in Q2 FY27 from Rs 1,125.81 crore in Q1 FY27, but Q2 turnover was also affected by the uneven start-up of major projects in the first quarter.
For the first half of FY27, turnover was Rs 2,589.48 crore, compared with Rs 2,182.18 crore in the first half of FY26. Management expects Q4 FY27 to be the company’s best quarter, while Q3 is likely to be lower sequentially because of GRAP. Central Vista’s exemption from those restrictions is therefore a project-specific support, rather than a full offset for constraints elsewhere in NCR.
Management expects second-half earnings before interest, tax, depreciation and amortisation, or EBITDA, margin to be similar to Q2 FY27’s 7.58%. That was higher than 4.29% in Q1 FY27 but below 10.92% in Q2 FY26. For FY28, management said it was targeting EBITDA margin expansion of at least one percentage point and indicated a range of 8.5% to 9%, while saying a 10% outcome was difficult to assess at present.
The two accelerating projects also affect reported cost mix because both are EPC contracts. Management said material costs were higher by about 4 to 5 percentage points due primarily to the project mix, as material arrivals on Central Vista and CSMT can initially be matched by billing that largely covers those materials. It expects the material-cost share of revenue to decline over the next six to nine months as structural items are fully billed.
Ahluwalia Contracts also said about 50% of clients without labour-escalation clauses had agreed to future escalation based on the minimum-wage index. The company said it now seeks labour and material escalation clauses when bidding for new orders. That policy is relevant after higher labour costs in NCR, alongside the execution timing of Central Vista, CSMT and Jewellery Park.
Conclusion
Central Vista and CSMT are the disclosed late-FY27 execution drivers for Ahluwalia Contracts. Central Vista’s exemption from GRAP supports its close to Rs 150 crore Q3 and more than Rs 200 crore Q4 turnover targets, while CSMT’s billing plan rises from about Rs 80 crore in the recent month to about Rs 150 crore in Q3 and close to Rs 200 crore in Q4. Jewellery Park remains unavailable for near-term revenue.
The next items to watch are Central Vista’s planned Rs 60 crore to Rs 70 crore December turnover, its more than Rs 200 crore Q4 target, and CSMT’s projected Rs 150 crore Q3 billing. Management has not set a revenue target for Jewellery Park and said work would still take about three months to begin after a notice to proceed, leaving client approvals and site clearance as the unresolved milestones.