










Astra Microwave Products Ltd targets 15%-20% revenue growth
Key highlights
- AMP targets 15%-20% revenue growth over the next three to five years.
- AMP’s standalone order book was Rs 3,937 crore at September 30, 2026.
- H1FY27 standalone revenue was Rs 437 crore, EBITDA was Rs 120 crore and PAT was Rs 57 crore.
- Research and development expenditure rose to Rs 58 crore in FY26 from Rs 23 crore in FY21.
powered by IRIS
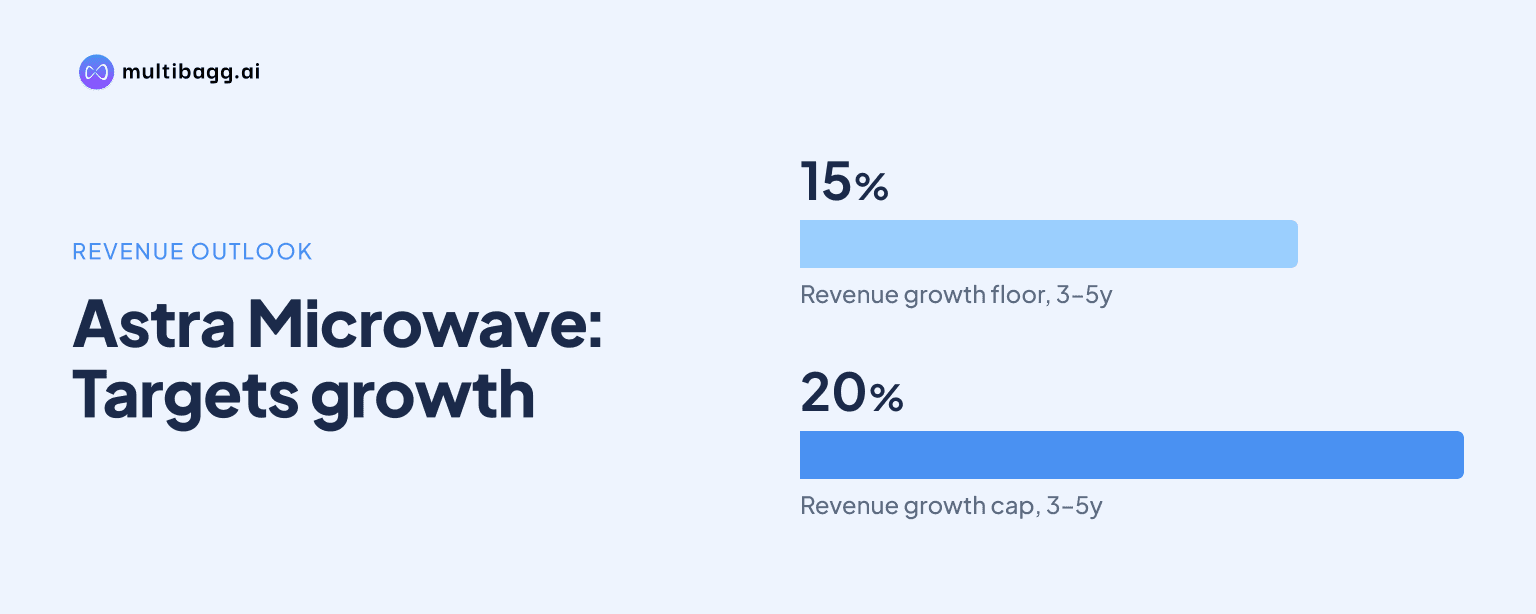
Astra Microwave Products Ltd targets 15%-20% revenue growth over the next three to five years by raising the contribution from complex-system fabrication, with a standalone order book of Rs 3,937 crore as of September 30, 2026. The company reported H1FY27 standalone revenue of Rs 437 crore and earnings before interest, tax, depreciation and amortisation of Rs 120 crore.
Know Astra Microwave Products inside out
Results, valuation, peers and who's buying, in one view.
What revenue growth target has AMP set?
AMP targets 15%-20% revenue growth, with complex-system fabrication expected to contribute a higher share of revenue within three to five years. Management links the planned mix change to revenue growth, margins and capital efficiency, but the presentation does not set out an annual growth path, a targeted systems-revenue share or a separate revenue target for the fabrication activity.
The disclosed standalone order book was Rs 3,937 crore at September 30, 2026. AMP also says it has delivered more than 10 successive years of revenue growth alongside increased profitability, although the presentation does not provide the revenue figures for each of those years. The order-book figure is the reported backlog measure accompanying management’s medium-term growth target.
AMP’s reported H1FY27 standalone revenue was Rs 437 crore, compared with Rs 1,156 crore for the full FY26. H1FY27 earnings before interest, tax, depreciation and amortisation (EBITDA) were Rs 120 crore, or 27.4% of revenue, while profit after tax (PAT) was Rs 57 crore, or 13.0%; FY26 EBITDA was Rs 324 crore, or 28.0%, and PAT was Rs 178 crore, or 15.4%.
How will complex-system fabrication change AMP’s business mix?
AMP plans to increase the proportion of revenue from complex-system fabrication while continuing to make systems, radio-frequency products, microwave super-components and sub-systems. The presentation identifies radar, electronic warfare and strategic electronics as its core domains, where AMP says it has more than 30 years of experience.
The source does not quantify the current or intended revenue mix between complex systems and other products. It does, however, report cumulative delivery experience of 35 radars, 25 satellites and 15 strategic programmes, as well as 25 years of participation in India’s space programme. These figures describe AMP’s operating history rather than future orders or recognised revenue.
AMP’s stated product scope extends beyond defence and space to metrology, homeland security and systems. Its listed offerings also include antennas, Global Navigation Satellite System solutions, unmanned ground vehicles and radio-frequency printed-circuit-board production. The broad product list indicates that the planned systems mix is being pursued alongside component and sub-system capabilities rather than as a disclosed exit from those activities.
What capabilities support AMP’s systems strategy?
AMP supports the strategy through four manufacturing facilities in Hyderabad, one research and development facility in Hyderabad and one research and development facility in Bengaluru. The company lists design and engineering, functional testing, quality control and environmental testing among its infrastructure capabilities, which are relevant to its built-to-specification and built-to-print work.
Research and development expenditure rose to Rs 58 crore in FY26 from Rs 23 crore in FY21, an increase of Rs 35 crore across the disclosed comparison. As of September 30, 2026, AMP reported 699 research and development professionals, including 93 with master’s degrees, nine with doctorates and 100 with more than a decade of experience.
AMP says it is among the few Indian private-sector players able to develop and supply gallium nitride and gallium arsenide monolithic microwave integrated-circuit products up to 40 gigahertz. It also says it is participating in multiple MAKE-II programmes of the Indian Air Force and Indian Army for radar systems, without specifying the number of programmes, their value or their expected timing.
Got a follow-up? Ask IRIS
What role do joint ventures play in AMP’s strategy?
AMP’s joint-venture activity provides exposure to communications, electronic-warfare and sensing systems alongside its standalone operations. Astra Rafael Comsys Pvt. Ltd. is described as India’s first private-sector military-grade software-defined radio manufacturing facility, operating from a 48,000-square-foot site at Hardware Tech-Park in Hyderabad.
The joint venture’s stated end markets include the Indian Army, Indian Air Force, Navy and exports. Its planned production scope includes tactical radio communication systems, software-defined radio, electronic warfare and signals-intelligence systems. Product examples listed in the presentation include BNET radio variants, SKY SHIELD, LITE SHIELD, X-GUARD and electro-optics offerings.
AMP says its joint ventures are receiving a steady influx of orders from global markets and that their high-end technology systems have worldwide potential. The presentation does not disclose joint-venture revenue, order book, ownership percentage, profit contribution or individual contract values, so their financial contribution to the 15%-20% growth target is not quantified.
What financial factors accompany AMP’s growth plan?
AMP’s consolidated total assets rose to Rs 2,206 crore in Sep-26 from Rs 1,988 crore in Mar-26. Current assets increased to Rs 1,792 crore from Rs 1,620 crore, while inventories rose to Rs 807 crore from Rs 616 crore. Over the same period, trade receivables declined to Rs 676 crore from Rs 688 crore and cash and cash equivalents declined to Rs 124 crore from Rs 175 crore.
Consolidated current borrowings increased to Rs 412 crore in Sep-26 from Rs 224 crore in Mar-26, while non-current borrowings rose to Rs 74 crore from Rs 63 crore. Current liabilities were Rs 703 crore in Sep-26, compared with Rs 518 crore in Mar-26, including Rs 122 crore of trade payables and Rs 118 crore of contract liabilities.
The consolidated cash-flow statement reported net cash used in operating activities of Rs 148 crore in Sep-26, compared with net cash generated from operating activities of Rs 238 crore in Sep-25. Changes in working capital were negative Rs 200 crore in Sep-26 versus positive Rs 210 crore a year earlier, while net cash used in investing activities increased to Rs 65 crore from Rs 17 crore.
Conclusion
AMP’s disclosed plan combines a 15%-20% revenue-growth target with a higher contribution from complex-system fabrication over three to five years. Its Rs 3,937 crore standalone order book, H1FY27 revenue of Rs 437 crore, rising FY26 research and development expenditure of Rs 58 crore, and established radar and space programme history form the reported backdrop to that strategy.
The next items to watch are AMP’s progress toward the three-to-five-year systems-mix objective and order-book updates after September 30, 2026. The source also makes working-capital execution relevant: inventories were Rs 807 crore, current borrowings were Rs 412 crore and operating cash flow was negative Rs 148 crore in Sep-26.