










Anlon Technology Solutions Limited Q2 profit rises 231%
Key highlights
- ANLON reported Q2 FY27 PAT of Rs 11.66 crore, up 231% from Rs 3.52 crore in Q2 FY26.
- Q2 FY27 total income rose 184% to Rs 61.49 crore and EBITDA increased 216% to Rs 16.62 crore.
- H1 FY27 total income was Rs 76.48 crore and PAT was Rs 9.21 crore, up 63% and 69%, respectively.
- ANLON's paid-up equity share capital increased from about Rs 7.51 crore to Rs 10.51 crore after its 2:5 bonus issue.
powered by IRIS
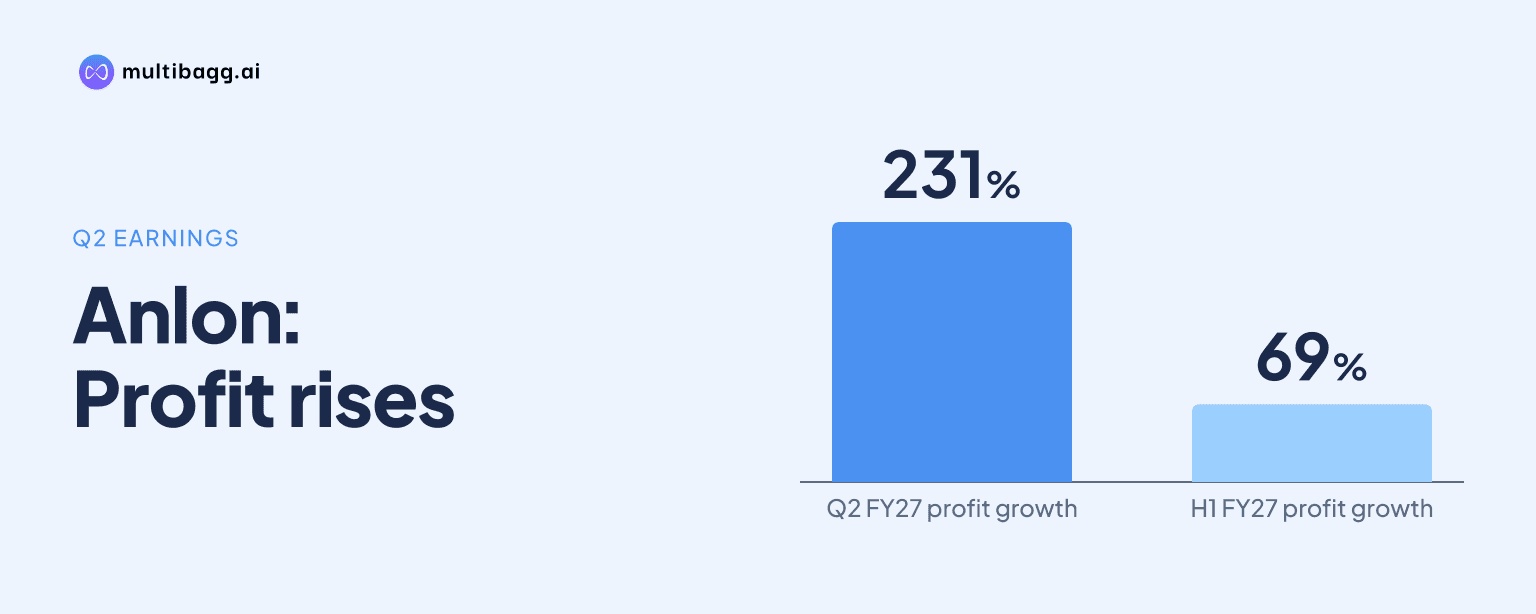
Anlon Technology Solutions Limited reported profit after tax of Rs 11.66 crore in Q2 FY27, up 231% from Rs 3.52 crore in Q2 FY26, as total income increased 184% to Rs 61.49 crore. The quarter’s EBITDA rose 216% to Rs 16.62 crore, exceeding the company’s H1 FY27 EBITDA of Rs 14.67 crore.
Know Anlon Technology Solutions inside out
Results, valuation, peers and who's buying, in one view.
Why did ANLON's Q2 FY27 profit rise?
ANLON's Q2 FY27 profit rose as total income increased by Rs 39.81 crore year on year, including a Rs 38.46 crore increase in revenue. Revenue reached Rs 59.72 crore from Rs 21.26 crore, while other income rose to Rs 1.77 crore from Rs 42.09 lakh. The presentation reported total-income growth of 184%.
Earnings before interest, tax, depreciation and amortisation, or EBITDA, increased to Rs 16.62 crore from Rs 5.26 crore. Profit before tax rose to Rs 15.59 crore from Rs 4.72 crore, while tax increased to Rs 3.93 crore from Rs 1.20 crore. This resulted in PAT of Rs 11.66 crore, compared with Rs 3.52 crore a year earlier.
The income increase exceeded the rise in total expenditure during Q2 FY27. Total expenditure grew by Rs 28.44 crore to Rs 44.87 crore, compared with the Rs 39.81 crore rise in total income. The resulting EBITDA increase was Rs 11.37 crore before interest costs of Rs 58.89 lakh and depreciation of Rs 44.18 lakh.
How did ANLON's Q2 FY27 costs and margins change?
ANLON's calculated EBITDA margin was 27.0% in Q2 FY27, compared with 24.2% in Q2 FY26, using reported EBITDA and total-income figures. Its calculated PAT margin was 19.0%, versus 16.2% a year earlier. These margins are calculations from the presentation rather than management guidance.
Purchase of stock-in-trade was the largest listed operating cost in Q2 FY27 at Rs 24.16 crore, up from Rs 2.76 crore in Q2 FY26. Raw-material consumption increased to Rs 14.02 crore from Rs 6.04 crore, and direct expenses rose to Rs 6.22 crore from Rs 5.01 crore. These movements occurred alongside revenue growth to Rs 59.72 crore.
Changes in inventories of work-in-progress and stock-in-trade provided a Rs 5.44 crore credit in Q2 FY27, compared with a Rs 3.00 crore credit in Q2 FY26. Employee costs rose to Rs 4.15 crore from Rs 3.63 crore, while other expenses fell to Rs 1.76 crore from Rs 1.99 crore. Interest cost rose to Rs 58.89 lakh from Rs 27.66 lakh.
What does ANLON's H1 FY27 statement show?
ANLON reported H1 FY27 total income of Rs 76.48 crore, up 63% from Rs 46.84 crore in H1 FY26, while PAT increased 69% to Rs 9.21 crore from Rs 5.46 crore. H1 revenue rose to Rs 74.34 crore from Rs 45.95 crore, and other income increased to Rs 2.14 crore from Rs 88.98 lakh.
H1 FY27 EBITDA rose 75% to Rs 14.67 crore from Rs 8.37 crore. Profit before tax increased to Rs 12.43 crore from Rs 7.33 crore, while tax rose to Rs 3.22 crore from Rs 1.87 crore. Calculated H1 PAT margin was 12.0%, compared with 11.7% in H1 FY26.
The reported Q2 PAT of Rs 11.66 crore was higher than the H1 FY27 PAT of Rs 9.21 crore. Arithmetic using the two reported figures implies a Q1 FY27 PAT loss of Rs 2.45 crore. Q2 total income of Rs 61.49 crore was about 80% of H1 income of Rs 76.48 crore, indicating that the half-year result was concentrated in the second quarter.
Got a follow-up? Ask IRIS
Which businesses does ANLON identify as its main segments?
ANLON identifies distribution as its largest segment at about 51%, followed by manufacturing and assembly at about 30% and annual maintenance contract, or AMC, and services at about 18%. The stated percentages total about 99% because the presentation uses approximate segment shares.
Within manufacturing and assembly, crash fire tenders account for about 41% of the product mix, followed by emergency responsible vehicles at about 24%. Emergency crash foam tenders represent about 15%, runway sweeping and moss or algae cleaning machines about 14%, and compact battery-operated sweeping machines about 5%.
Managing Director Unnikrishnan Nair P M said ANLON was winning repeat business from airport and industrial customers in spare parts, AMC services and Make in India assembly. He also cited a refurbishment order from GMR Hyderabad International Airport, saying refurbishment has faster turnaround and can help work around import delays linked to Red Sea disruption. These are management comments and the presentation does not quantify associated revenue or order-book value.
What corporate actions and plans has ANLON disclosed?
ANLON completed a 2:5 bonus issue, issuing two bonus equity shares of Rs 10 each for every five fully paid-up shares held on the record date. Capitalisation of the securities premium account increased paid-up equity share capital from about Rs 7.51 crore to Rs 10.51 crore. The bonus issue is separate from Q2 FY27 operating income.
Shareholders approved migration from NSE Emerge to the National Stock Exchange of India Main Board through a postal ballot dated 18 October 2026. The presentation says the migration process is underway and gives no completion date. Management also said Miron Harri Thoms had joined as chief executive officer, citing his Volvo Group experience in discussing plans for operations and partnerships in India and overseas.
Conclusion
ANLON’s Q2 FY27 figures show a substantial increase in income, EBITDA and PAT, with total income rising to Rs 61.49 crore and PAT reaching Rs 11.66 crore. The H1 FY27 statement recorded Rs 76.48 crore of total income and Rs 9.21 crore of PAT, while the reported quarterly and half-year figures indicate that the second quarter accounted for most of the six-month outcome.
Next, readers can watch whether repeat airport and industrial business, refurbishment activity and Make in India assembly continue to support the segment mix described by management. The other disclosed event to monitor is the NSE Main Board migration, which remained underway after shareholder approval on 18 October 2026, without a stated completion date.